
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is China Chip Materials Expansion Altering The Investment Case For Nissan Chemical (TSE:4021)?
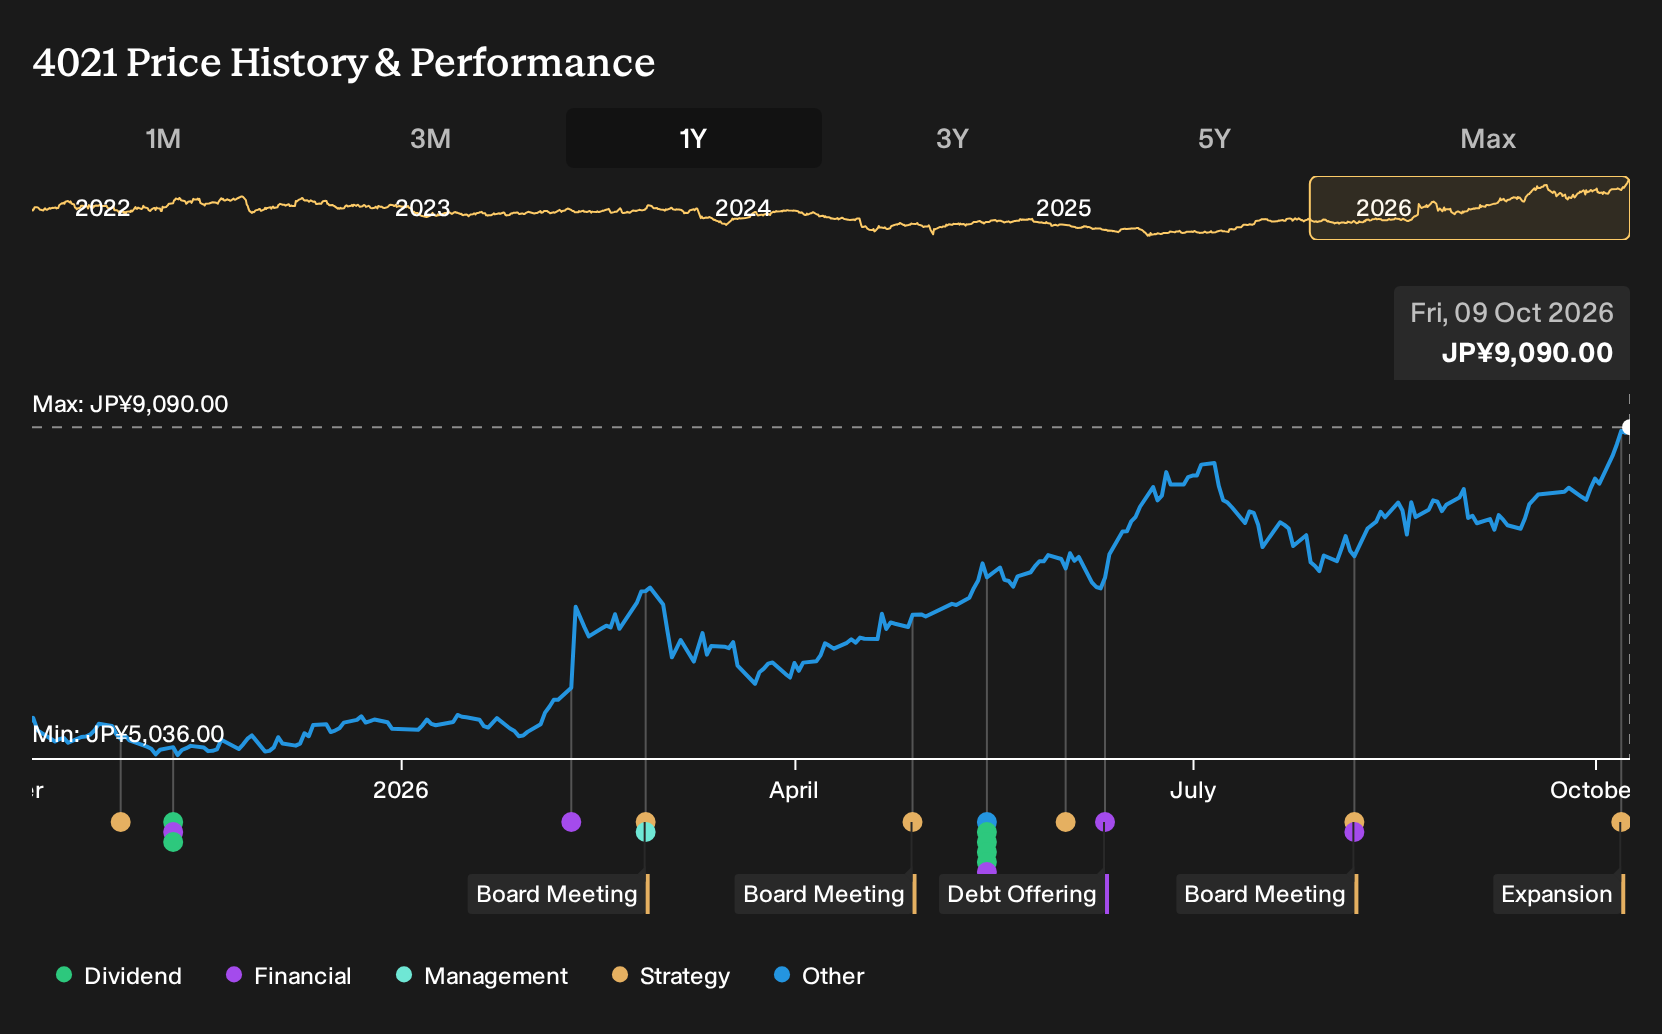
- Nissan Chemical has set up Nissan Chemical Semiconductor Materials Zhangjiagang Co., Ltd. in Jiangsu Province, China, to manufacture and sell anti reflective coatings for photoresists and multilayer semiconductor materials. The company is backed by RMB 210 million in registered capital, with an initial RMB 89 million funding planned for October 2026.
- By locating semiconductor materials production directly in Zhangjiagang City near Chinese chip customers, Nissan Chemical is reshaping its supply footing and concentrating more operational and geopolitical risk in a single, high demand market.
- The focus now is on how Nissan Chemical's investment narrative could shift as it commits on the ground capital to Chinese semiconductor materials.
Scan 92 AI infrastructure stocks to see which other chip supply chain stocks, alongside Nissan Chemical's China-focused build out, could be positioning for the next leg of semiconductor demand.
What Is Nissan Chemical's Investment Narrative?
To own Nissan Chemical, you have to believe in a fairly simple idea. A diversified chemicals and materials group with high quality earnings, a 20.9% return on equity and a 2.33% dividend is trying to compound steadily rather than shoot the lights out. The Zhangjiagang subsidiary fits that story. It looks like a focused capacity move into a growing Chinese chip market, not a bet that rewrites guidance or near term demand. Recent share gains and a price only slightly below analyst targets suggest the market already prices in a lot of that steady execution.
The short term swing factors still feel familiar. Execution on semiconductor materials orders, pricing power in higher value segments like performance materials and discipline around new capital spending. The China build out adds more fixed investment and concentrates some operational risk in a single geography, while earnings forecasts that are growing but not rapidly and a 23x P/E keep expectations reasonably high. If management mis-times that spend or if China specific conditions shift, the current share price and DCF implied upside could look less generous.
Yet alongside the Zhangjiagang opportunity and the recent share strength, one awkward concentration risk still hangs over the story.
There's only one way to know the right time to buy, sell or hold Nissan Chemical. Head to Simply Wall St's company report for the latest analysis of Nissan Chemical's Fair Value.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community range from 0.33 up to a very large 12,445.31, which highlights how widely opinions on Nissan Chemical can differ. Those views were set before the Zhangjiagang decision, so you are looking at pre-expansion numbers. Use that gap to explore several alternative viewpoints on the stock.
Explore 2 other Nissan Chemical fair value estimates, including one that suggests as much as 37% upside from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nissan Chemical research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Nissan Chemical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nissan Chemical's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nissan Chemical?
If you want to balance your view on Nissan Chemical with a wider watchlist, it helps to see how other businesses stack up on value, quality and resilience. The Simply Wall St Screener lets you scan a broad set of listed companies through different lenses so you can build a line up that fits your own return and risk preferences.
- For investors who want income to do more of the work, check out 28 dividend fortresses that may appeal if you are hunting for yield with substance behind it.
- If capital preservation sits higher on your priority list, filter for steadier profiles through a 23 resilient stocks with low risk scores that may suit a more cautious approach.
- When you are searching for under researched opportunities, widen the field with a 74 high quality undiscovered gems and see which lesser known businesses fit your criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com