
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
British Undervalued Stocks To Own In October 2026
UK government borrowing costs have climbed since March as global bond markets react to higher inflation and policy rates. That has pushed many British high quality cash generators out of favour, even when their balance sheets look healthy. For long term investors, this dislocation can create rare entry points into strong businesses priced as if trouble is permanent. This article highlights three such undervalued UK stocks that score well on our quality and value tests.
The three stocks below are just a first cut from our High Quality Undervalued Stocks idea. The full screen surfaced 4 more businesses with equally compelling stories that are not covered here. To go straight to the source and identify, compare, and analyze potential high conviction candidates, jump into the High Quality Undervalued Stocks screener.
Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings manages renewable-focused infrastructure funds and diversified private equity and venture strategies for institutional and retail investors worldwide.
Operations: Foresight generates about £114.8 million from Real Assets and £50.1 million from Private Equity, with £126.4 million earned in the United Kingdom and £25.7 million in Australia.
Market Cap: £491 million
Foresight Group’s renewable infrastructure management franchise gives this High Quality Undervalued Stocks pick a clear connection to long term, fee-based cash flows.
"Market underpenetration and strategic expansion into new products and relationships signal much greater AUM growth potential than consensus expects."
What matters next for Foresight Group is how one underappreciated shift in its fee mix plays out against rising cost pressures.
To see how that fee mix shift could accelerate or stall future cash generation, read the full narrative for Foresight Group Holdings for the full context on risks and upside drivers.

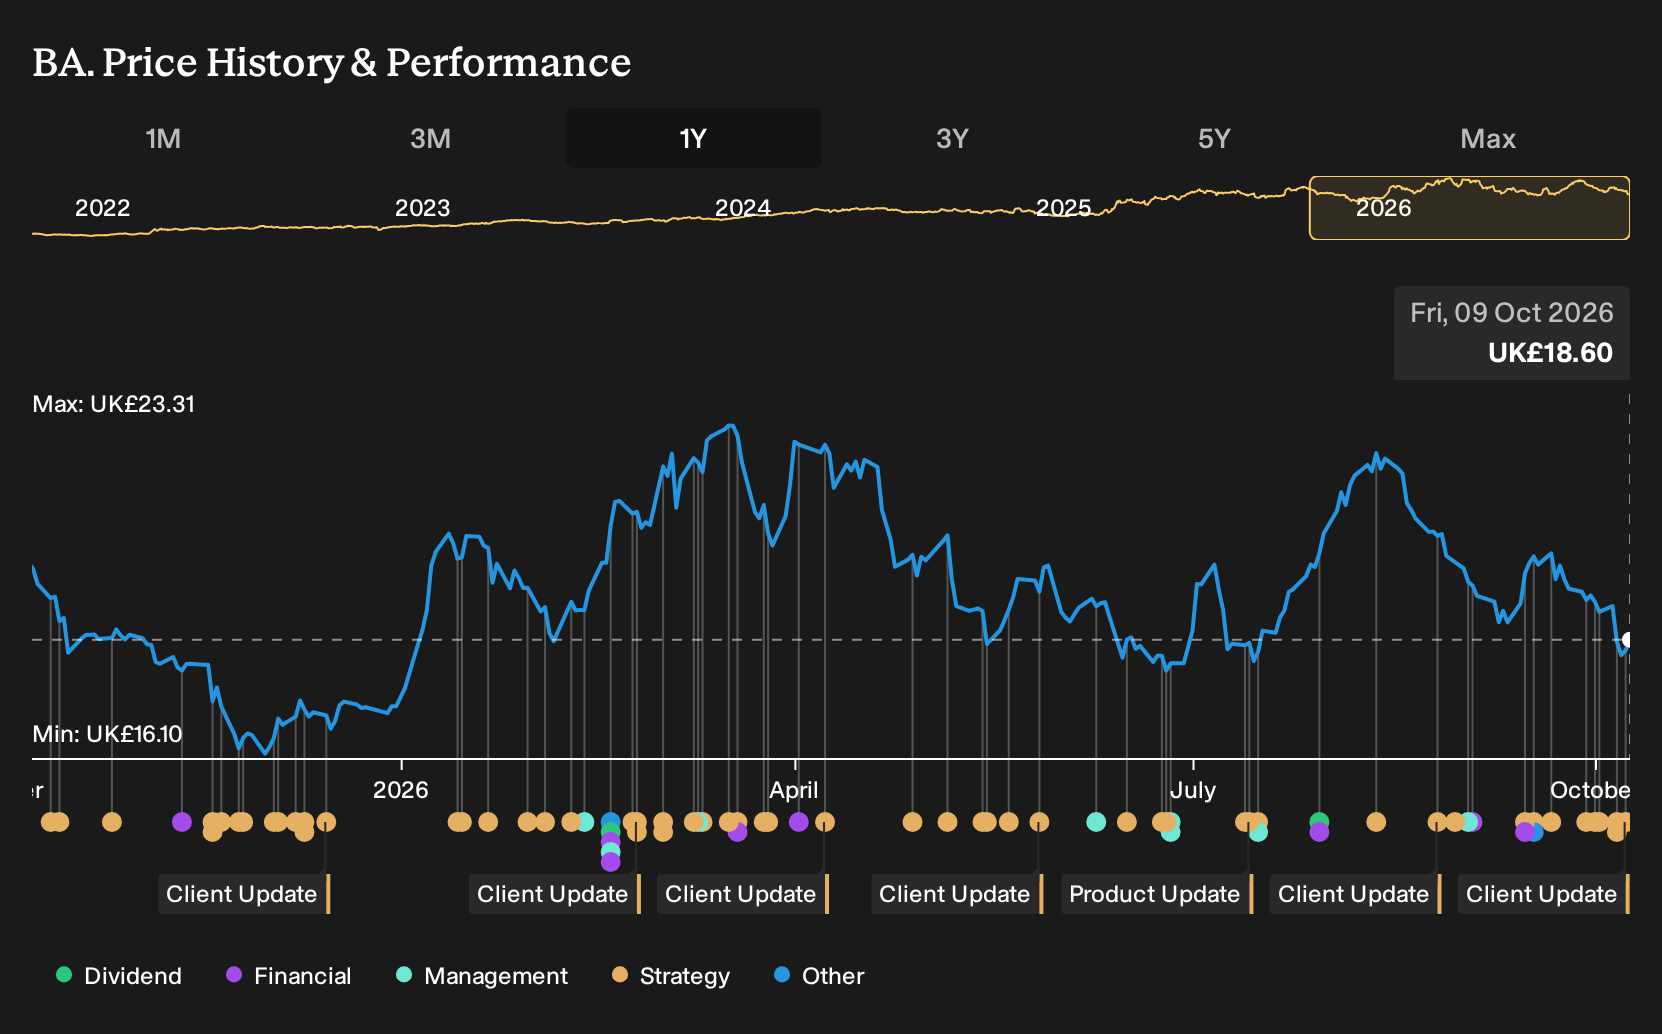
BAE Systems (LSE:BA.)
Overview: BAE Systems is a global defence and aerospace contractor supplying high-value platforms, munitions, electronics and security services under long-term government contracts.
Operations: The group generates about £7.8b from Electronic Systems, £7.7b from Air, and £5.3b from Platforms & Services across primarily US and UK customers.
Market Cap: £52.6b
BAE Systems fits the High Quality Undervalued Stocks theme through its cash-generative Platforms & Services and Air franchises anchored on multi-year government programmes, which supports steady contract inflows even as the broader defence cycle shifts.
"The company's order backlog has surged to £75 billion, with a pipeline of new opportunities partly fueled by higher defense spending commitments across NATO, the US, UK, Europe, and Indo-Pacific, providing exceptional visibility on future revenues and supporting strong topline growth for multiple years."
One potential variable for investors is how unseen pressures on profitability and cash conversion might tilt toward either stronger margins or tighter funding costs.
Those shifting profitability and funding pressures are exactly what the full narrative for BAE Systems unpacks, showing where BAE Systems cash generation could decouple from headline contract wins.
Smith & Nephew (LSE:SN.)
Overview: Smith & Nephew develops orthopaedic implants, trauma devices, sports medicine tools and advanced wound care products for hospitals worldwide.
Operations: Smith & Nephew generates about $2.46b from Orthopaedics, $2.03b from Sports Medicine & ENT and $1.82b from Advanced Wound Management.
Market Cap: £8.58b
Smith & Nephew fits the High Quality Undervalued Stocks theme through its orthopaedics franchise, where knee and hip implants plus trauma systems create durable, high-margin cash flows that can support the broader medical device portfolio.
"Acceleration in new product innovation, such as expanded robotic-assisted surgery (CORI, CORIOGRAPH), new implants (CATALYSTEM Hip, TRIGEN MAX Tibia Nailing), and significantly increased contributions from recent product launches (75% of H1 growth from products <5 years old), positions the company to capture greater market share and sustain higher long-term revenue growth as global demand for advanced orthopaedic and minimally invasive solutions rises."
What really matters is how one unresolved pressure on future pricing and profitability collides with this push into higher value procedures.
That pressure point is exactly what the full narrative for Smith & Nephew unpacks, showing where pricing risk, procedure mix and execution could turn Smith & Nephew into an accelerating recovery story.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. By the time a story hits headlines, early entry points may be gone and momentum already flying. Scan these curated shortlists while it matters and get in early.
- Spot income streams and review payouts by scanning a curated set of higher yielding payers with the 1 dividend fortresses.
- Review developments in computing power and shortlist potential beneficiaries of rising data demand using the focused 92 AI infrastructure stocks.
- Explore businesses operating outside the spotlight and build a watchlist from the curated 5 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com