
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Adient (ADNT) Could Be 41% Undervalued On Its Turnaround Narrative
Adient (ADNT) has drawn fresh attention after its recent share move, with the stock now around $17.42 and its trailing 1-year total return showing a decline of 22.7%.
That recent pullback leaves Adient trading at $17.42, with the share price return down 9.5% over the past three months and 8.5% year to date. The 1-year total shareholder return has declined 22.7%, signalling fading momentum despite occasional short-term rebounds.
Scan how Adient compares to other turnaround candidates by reviewing the hand picked 29 high quality undervalued stocks with resilient balance sheets and room for sentiment to shift.
After that slide and a long stretch of weak total returns, Adient now poses a simple question to new investors: Does the current valuation still compensate you for the turnaround risk, or has the easy part of the opportunity already passed?
Most Popular Narrative: 41% Undervalued
Adient’s most followed valuation story pegs fair value at $29.55, well above the last close at $17.42. This highlights what would need to go right in the underlying business for that gap to be justified.
Americas onshoring wins, including incremental volumes on Chevrolet Equinox and Volkswagen programs along with an estimated US$400 million backlog for FY27 and US$630 million for FY28, combined with the added Romulus foam plant, are cited as factors that could support future revenue growth and a potential uplift in regional earnings as higher margin vertically integrated components scale.
See why 5 investors see Adient as 41% undervalued.
Result: Fair Value of $29.55 (UNDERVALUED)
Still, persistent cost pressure and the multi year EMEA restructuring bill could easily blunt the Adient margin story if execution slips.
Find out about the key risks to this Adient narrative.
Another View: What Adient’s P/E Is Signalling
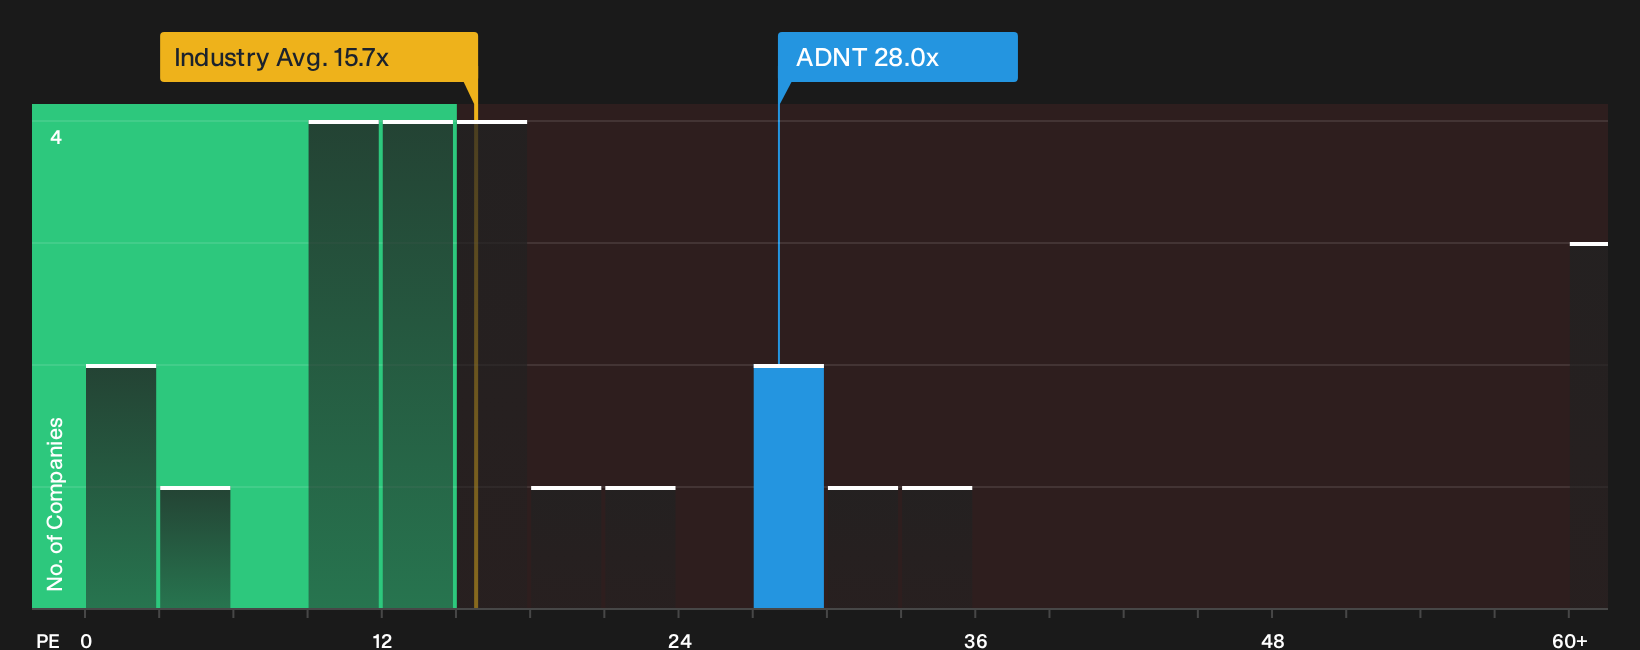
The story looks different when you stop using fair value models and just look at what the market is paying for Adient today. The shares trade on a P/E of roughly 28x, compared with about 15.7x for the US Auto Components group, 27x for peers, and a fair ratio of 25.7x. That richer multiple suggests investors already price in a decent amount of improvement, so the real question is how much execution risk you are comfortable owning at this entry point.
For a closer look at how this valuation gap stacks up against industry and peer data, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Adient is mixed, so take this as your prompt to move quickly. Review both sides of the story and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Adient?
If Adient has you thinking harder about risk, reward and timing, broaden your watchlist with fresh ideas that match your style and discipline.
- Target higher income potential by reviewing 8 dividend fortresses that can help anchor your portfolio with consistent cash flow.
- Hunt for quality on sale through the 20 high quality undiscovered gems before wider market attention tightens the opportunity set.
- Prioritise staying power by checking the 31 resilient stocks with low risk scores that aim to keep drawdowns in check when conditions turn rough.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com