
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Arm Holdings (ARM) On Jury Verdict Watch And A Valuation Debate
Jury verdict looms over Qualcomm dispute
Arm Holdings (NasdaqGS:ARM) is back in focus as investors watch a Delaware jury weigh Qualcomm’s claims of breached licensing deals and withheld design tools, a dispute tied closely to Arm’s royalty income.
Arm Holdings has seen momentum cool in recent weeks, with the share price falling 3.27% over the last day and 12.09% across seven days, even though the year to date share price return of 132.09% and three year total shareholder return above 4x still signal a strong longer term run.
Spot fresh ideas around Arm’s licensing and AI themes by scanning a handpicked set of resilient chip designers and enablers in the 31 resilient stocks with low risk scores.Arm Holdings now trades only modestly below the average analyst target, yet the implied intrinsic value points the other way. Where does a reasonable fair value anchor for this stock actually land after the recent pullback?
Most Popular Narrative: 38% Undervalued
The narrative fair value for Arm Holdings sits at $430 per share, well above the last close of $266.28. This frames the current pullback as a potential mispricing rather than just a sentiment swing.
Arm may be one of the most strategically important companies in computing, but the stock already assumes a very large part of that future. The business is exceptional. The entry point is the debate.
See why 43 investors see Arm Holdings as 38% undervalued.
Result: Fair Value of $430 (UNDERVALUED)
Still, that story can break if AGI CPU execution disappoints, or if regulatory and customer pushback on Arm Holdings’ new role in data center chips intensifies.
Find out about the key risks to this Arm Holdings narrative.
Another view on Arm Holdings’ valuation
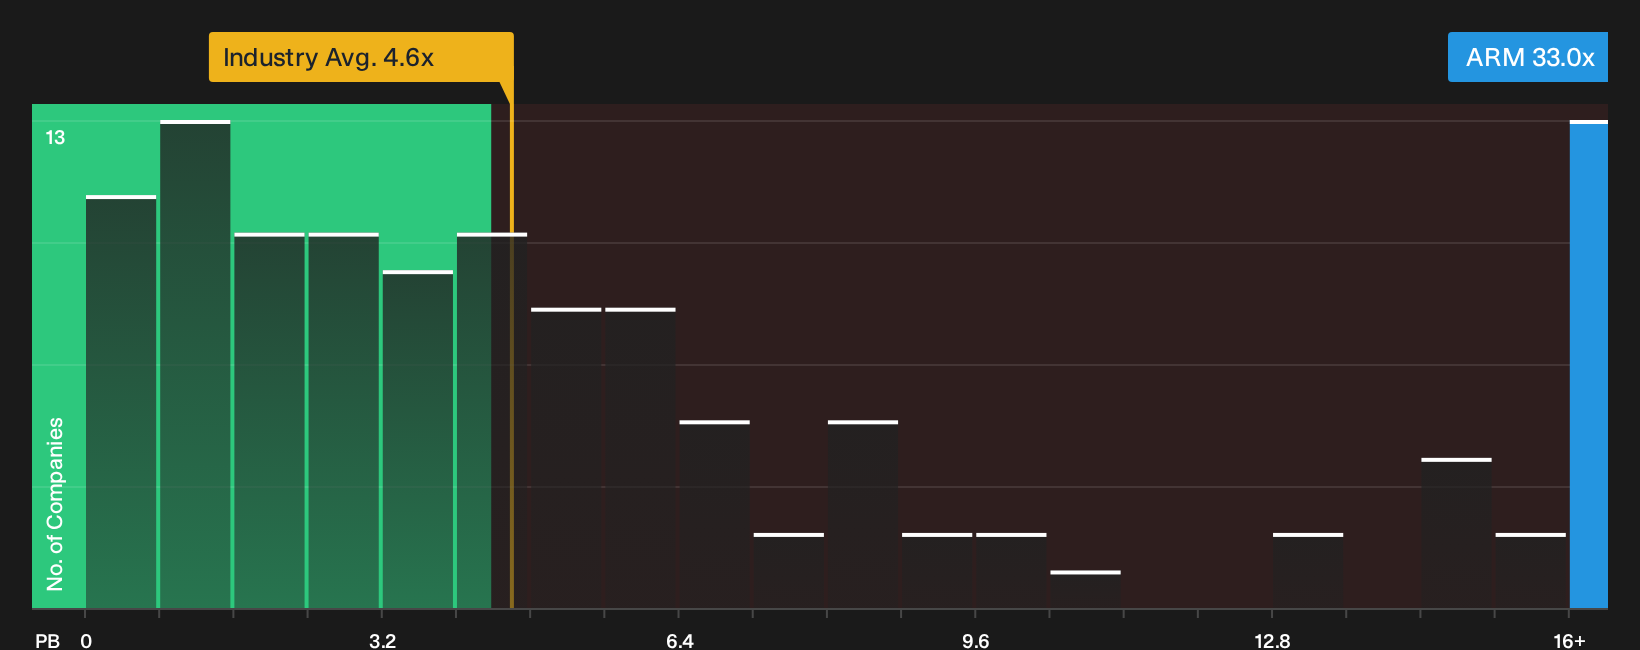
The earlier fair value story painted Arm Holdings as 38% undervalued around $430 per share. A different lens tells a harsher story. On P/B, the stock trades at 33x, while peers sit closer to 10x and the wider US semiconductor group around 4.6x.
That kind of premium suggests investors are already paying upfront for a lot of future execution and leaves less room for disappointment if growth or margins stumble. The question for you is simple: Is that gap a risk worth carrying or a premium you would rather avoid?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Arm Holdings can be confusing, so move quickly, review the numbers yourself, and pressure test both sides of the story with 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Arm Holdings?
Do not stop with one ticker. Use focused stock lists to spot fresh setups, balance your portfolio, and avoid missing pockets of quality that the market overlooks.
- Target potential mispricings by shortlisting companies that combine solid fundamentals with attractive valuations through the 29 high quality undervalued stocks.
- Strengthen the defensive side of your holdings by zeroing in on businesses with robust finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for future leaders hiding in plain sight by filtering for quality smaller players via the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com