
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hollywood Bowl Group And 2 British Undervalued Stocks To Watch
Bond yields in the UK have jumped this year, and the Institute for Fiscal Studies is warning that the budget could look unrealistic without a clear plan to handle rising costs. When borrowing feels more expensive and policy looks uncertain, cash flowing businesses trading below what careful models suggest they are worth can draw extra interest. This piece highlights three UK stocks screening as undervalued on their future cash flows.
The three examples below are only a sample of what this idea can look like in a portfolio, and the full screen surfaced 24 more businesses with similarly cash rich stories that are not covered here.
To go beyond the shortlist and put this theme to work, head straight into the Undervalued Stocks Based On Cash Flows screener to identify, filter, and analyze the highest conviction cash flow opportunities.
Hollywood Bowl Group (LSE:BOWL)
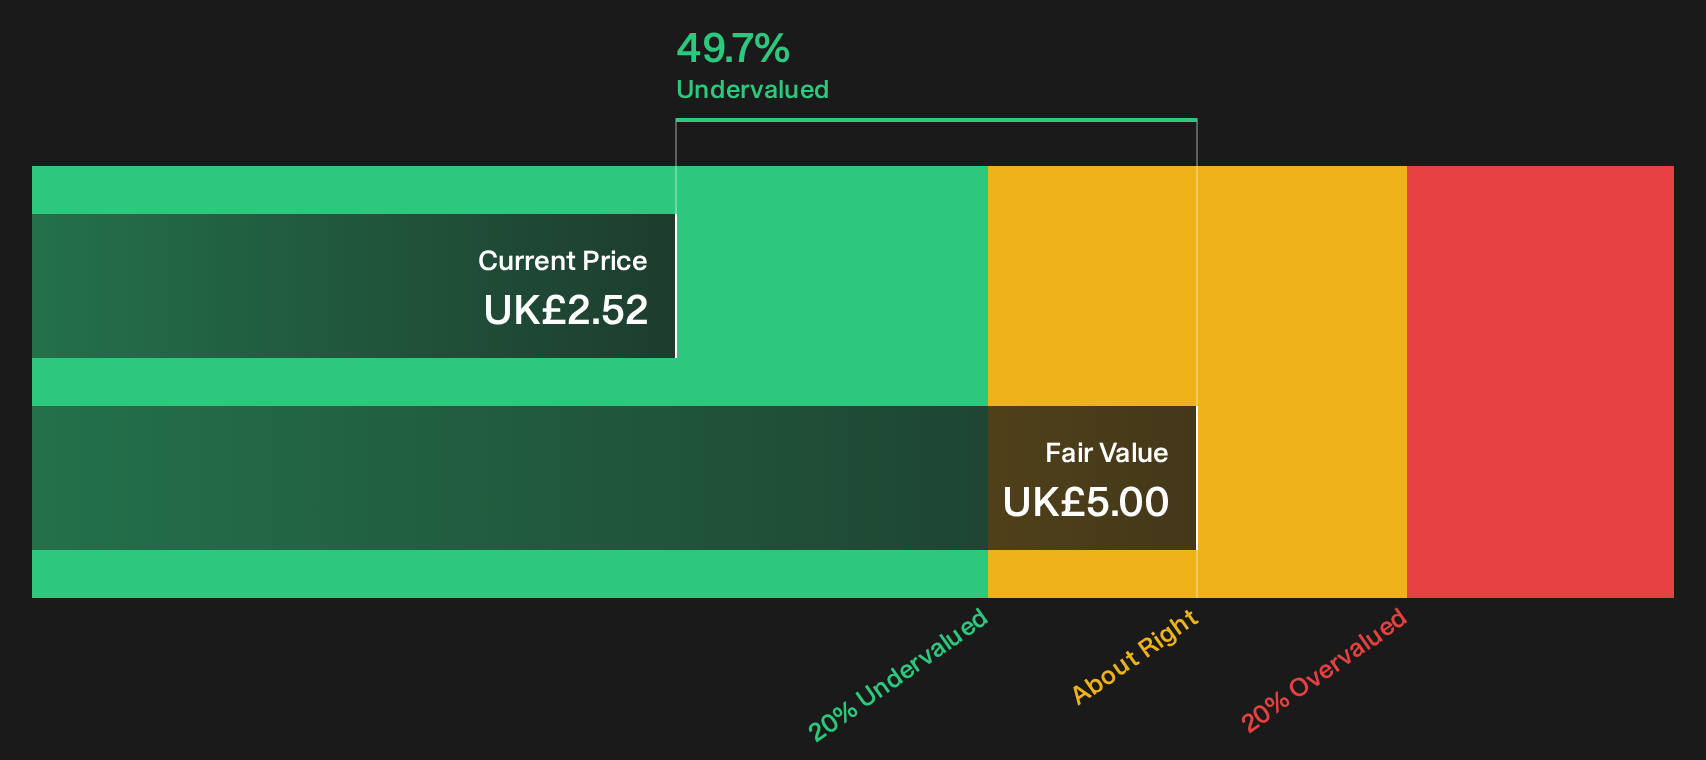
Hollywood Bowl Group runs ten pin bowling, mini golf and family entertainment centres under the Hollywood Bowl and Splitsville brands, with cash generative leisure operations that fit neatly with a discounted cash flow led value screen. It generated about £263 million from recreational activities and has a market value of roughly £419 million.
Hollywood Bowl Group currently trades on a P/E of about 12.5x versus roughly 17.3x for the wider UK hospitality sector, with analysts expecting double digit earnings growth and reporting margins around 12.7%. The gap between share price and cash flow estimates means much depends on how resilient visitor spending and pricing prove to be.
That resilience question is exactly what the DCF valuation analysis for Hollywood Bowl Group is built to stress test, so you can see how much headroom the current P/E gap really leaves.
Foresight Group Holdings (LSE:FSG)
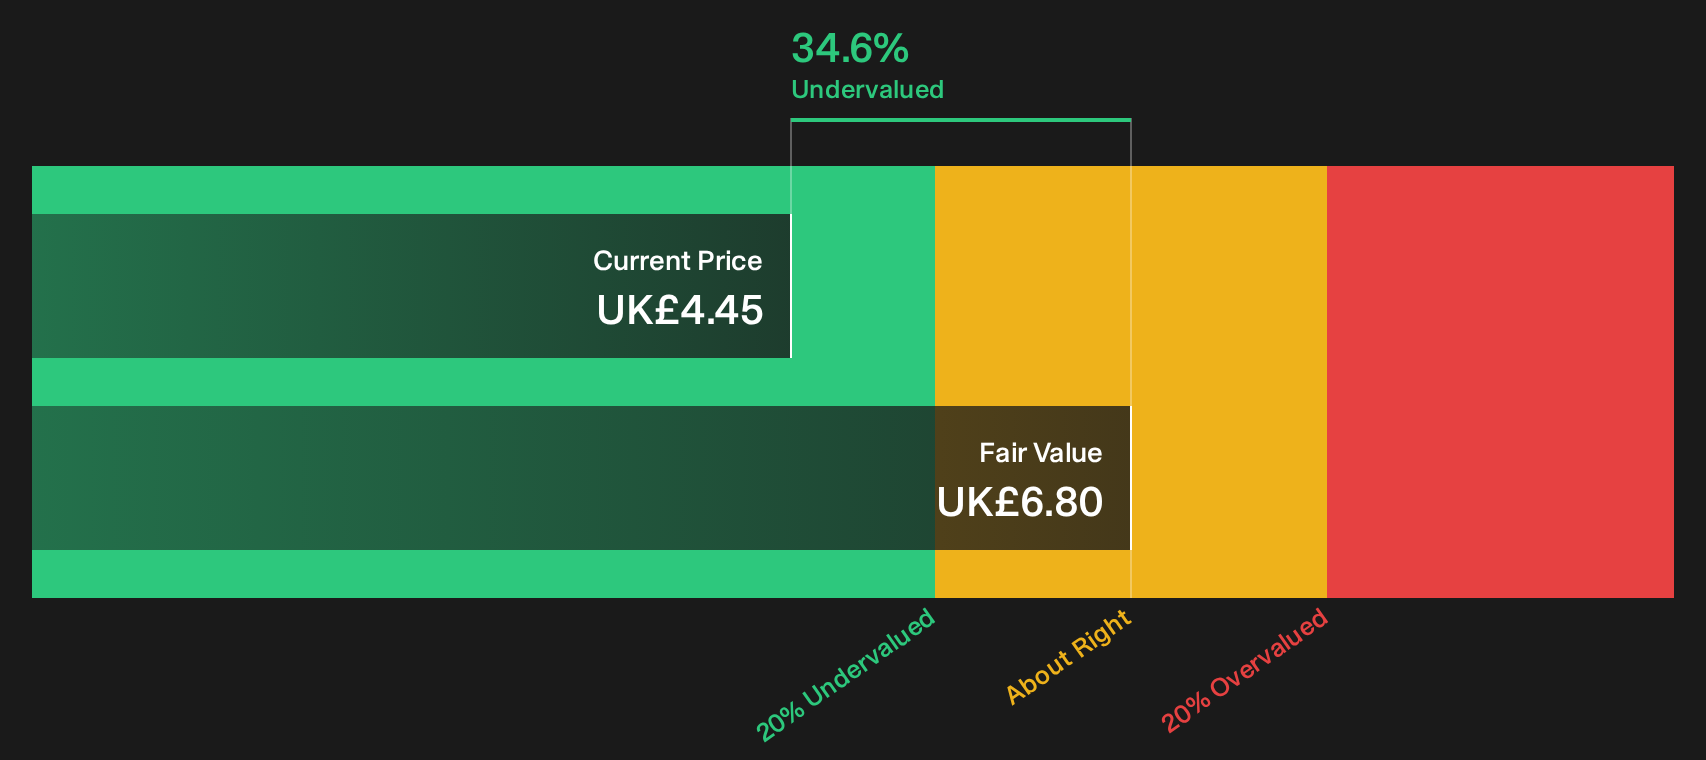
Foresight Group Holdings is an infrastructure and private equity manager whose renewable energy infrastructure funds link it directly to the undervalued cash flow theme. Real Assets generate about £115 million of revenue versus roughly £50 million from Private Equity, and the group is valued at around £491 million.
For investors focused on cash flow visibility, Foresight Group Holdings brings something different to this screen, because many of its renewable energy infrastructure mandates are already structured around long term cash streams that slot neatly into discounted cash flow models.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is described as a potential driver of compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and the return of capital accelerates."
What really matters next is how one pressure on future fee margins and reinvestment capacity ultimately resolves.
That margin pressure question is exactly what sits at the centre of the full narrative for Foresight Group Holdings, where the full story weighs fee resilience against accelerating capital recycling.
Smiths News (LSE:SNWS)
Smiths News runs wholesale distribution, warehousing, and final mile delivery for newspapers and magazines, giving it recurring cash flows that fit the undervalued cash flow theme. The group generated about £1.0b from its Smiths News (Including DMD) segment, is focused on the UK, and has a market value near £180 million.
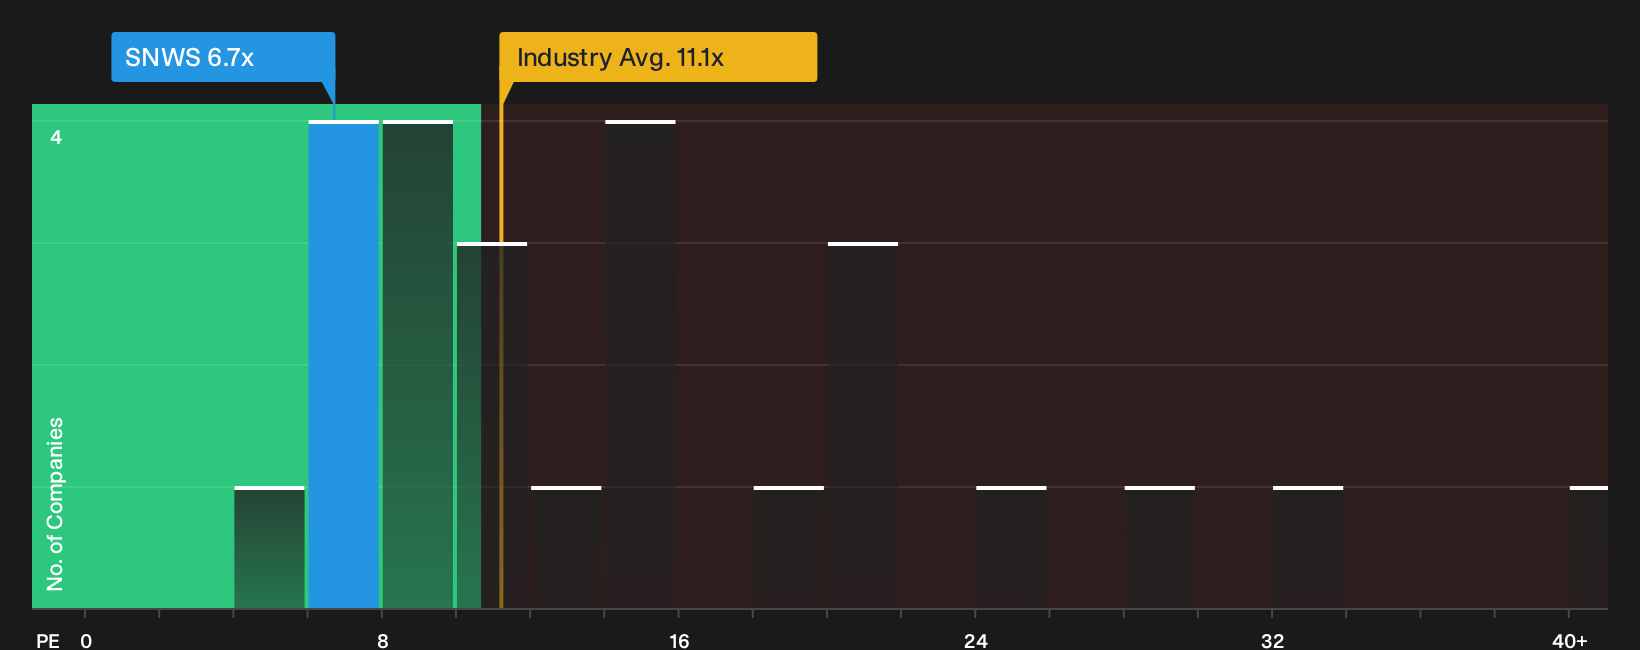
Smiths News connects cleanly to a cash flow led value screen because its print media logistics network produces recurring distribution income while the stock trades on a low P/E of about 6.7x compared with roughly 11.1x for European retail distributors. Forecast revenue and earnings declines mean the investment case depends heavily on how pressure on future volumes and pricing plays out.
That volume and pricing tension makes the 2 key rewards and 2 important warning signs (1 is major!) especially useful for spotting where Smiths News could quietly decouple from low expectations.
Seeking Alternatives Before The Crowd?
Fresh ideas can move fast. Screens fill with companies building breakout momentum while prices are still under the radar for now. Momentum rarely waits, so consider acting early when appropriate for your strategy.
- Spot income workhorses built for consistency by scanning the 1 dividend fortresses before yields change and the crowd chases the same payouts.
- Track early movers connected to tomorrow's grids through the 43 power grid technology and infrastructure stocks while infrastructure spending stories may still be flying under most radars.
- Explore potential automation leaders on the 91 robotics and automation stocks while their order books may be developing and before robotics headlines draw broader attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com