
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Solvay (ENXTBR:SOLB) Rare Earth Plant Expansion
- Solvay is drawing more attention to its La Rochelle rare earths facility, as global buyers look for production capacity outside China following export controls.
- The rare earth push highlights how Solvay can reuse existing processing expertise to pursue higher value revenue streams without building entirely new assets.
- We will look at how Solvay's investment narrative is shaped by La Rochelle's rare earth role in localized, non-Chinese supply chains.
Scan how Solvay's rare earths push compares with other potential beneficiaries of supply chain reshoring by reviewing our curated list of 33 best rare earth metal stocks.
Solvay Investment Narrative Recap
To own Solvay, you need to believe the heavy lifting in commodities like soda ash can coexist with higher value niches such as rare earth processing. The short term story still revolves around stabilizing margins after a year of weak profitability, one off losses, and pressure in key segments where demand and pricing have been soft.
The La Rochelle rare earth news matters mainly because it could improve asset utilization rather than change the investment case overnight. The biggest near term swing factor remains whether management can keep costs in check while capacity is underused. The key risk is that pricing pressure and high debt drag on any operational progress.
In this context, the push to position La Rochelle as a rare earth hub looks like the operational announcement that ties closest to today’s news. It builds directly on Solvay’s existing formulations for auto and electronics customers, so investors can track a single site to judge whether specialty materials can offset softness elsewhere.
For catalysts, it gives you a concrete yardstick. If customer contracts and production volumes at La Rochelle scale up, the potential outcome is better asset productivity and a richer mix of high value revenue. If take up disappoints or external competition and trade barriers intensify, the risk is that rare earth ambitions stay underutilized while the core chemicals portfolio still faces margin pressure.
Solvay Rare Earths Story Through The Numbers
Solvay's narrative projects €4.3 billion revenue and €239.3 million earnings by 2029. Analysts are assuming revenue will decline 2.4% per year to reach that top line. Earnings would need to swing by about €264 million from a loss of €25.0 million today to reach the 2029 consensus figure.
Uncover why Solvay's fair value aligns with its current price.
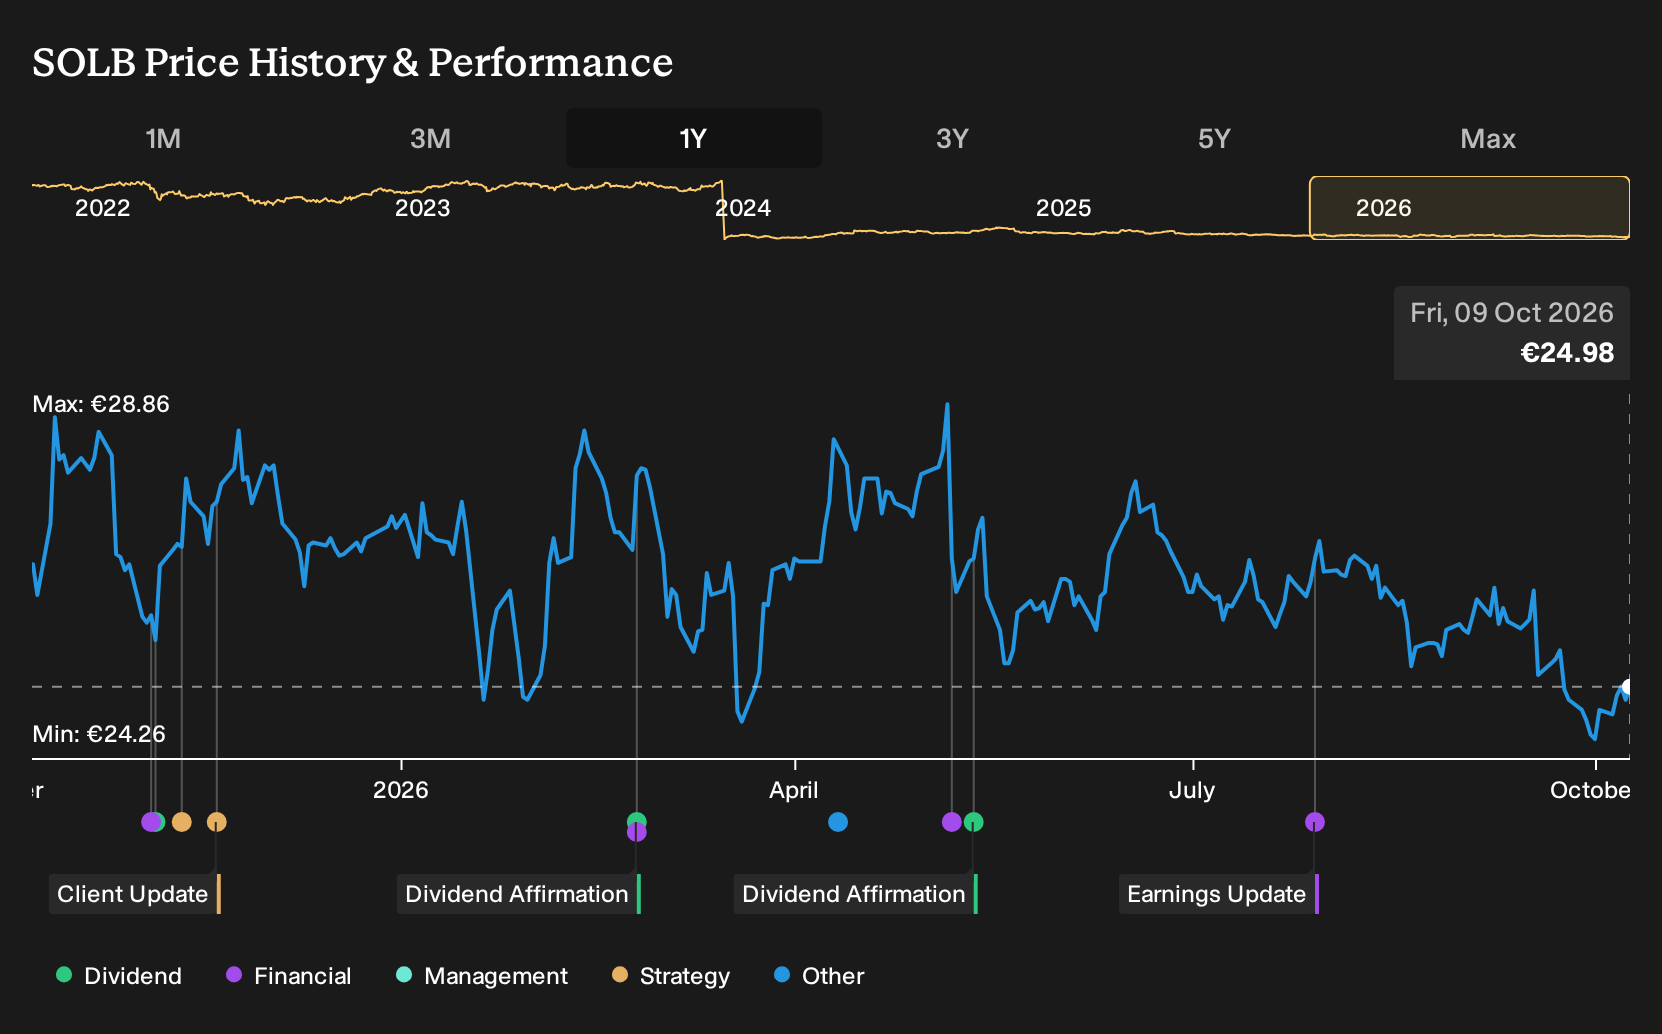
Exploring Other Perspectives
One alternate angle focuses less on Solvay’s La Rochelle rare earths opportunity and more on pressure from soda ash exports. The most bearish analysts were assuming revenue would trend toward about €4.4 billion and earnings near €223.0 million by 2029, which is more cautious than consensus. These views were set before this latest rare earths news, so you can treat them as a baseline and explore how your own expectations might differ.
Explore 3 other Solvay fair value estimates, including one that suggests it could be worth just €25.10.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Solvay research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Solvay. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Solvay's overall financial health at a glance.
Looking for more investment ideas beyond Solvay?
If the Solvay story has sharpened your thinking about risk, cash flows and balance sheet strength, it can help to line that up against a wider set of potential opportunities using the Simply Wall St Screener.
- If you care most about resilient businesses with fewer red flags, start by reviewing 223 resilient stocks with low risk scores that may better fit your risk tolerance.
- For investors who want quality at a reasonable entry point, scan a curated 179 high quality undervalued stocks that pair healthier fundamentals with more modest pricing.
- If you would rather focus on sturdier finances first and upside second, filter for a list of solid balance sheet and fundamentals (202 results) to compare against Solvay's profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com