
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
European Growth Stocks With Insider Ownership And Earnings Up To 49%
The European stock market has experienced volatility recently, influenced by geopolitical tensions in the Middle East and a more hawkish stance from the European Central Bank. Despite these challenges, investors continue to seek out growth opportunities, particularly in companies where high insider ownership may suggest confidence from those closest to the business.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.8% |
| Kuros Biosciences (SWX:KURN) | 23.7% | 65.8% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Gold Road International (OB:GOLDR) | 35.9% | 89.8% |
| Egetis Therapeutics (OM:EGTX) | 18.4% | 49.5% |
| CTT Systems (OM:CTT) | 17.4% | 55.3% |
| Clavister Holding AB (publ.) (OM:CLAV) | 19.4% | 41.1% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.2% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 30.2% |
Let's uncover some gems from our specialized screener.
Lectra (ENXTPA:LSS)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Lectra SA offers industrial intelligence solutions for the fashion, automotive, and furniture markets globally, with a market cap of €775.99 million.
Operations: The company's revenue is derived from three main regions: €160.58 million from the Americas, €103.62 million from the Asia-Pacific, and €220.89 million from EMEA (Europe, Middle East and Africa).
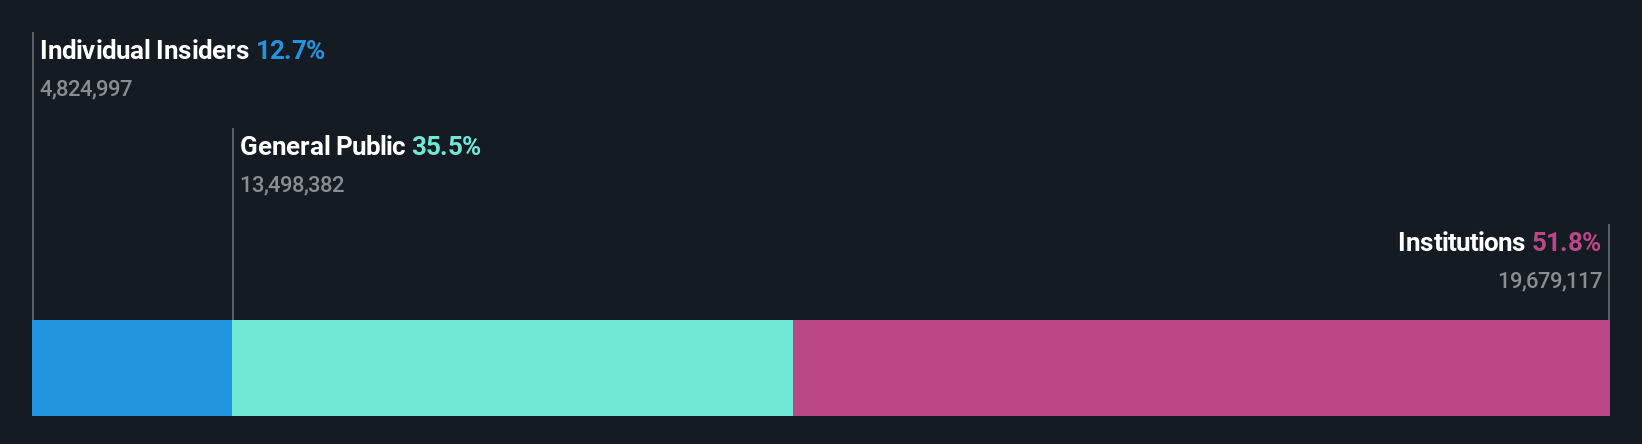
Insider Ownership: 13%
Earnings Growth Forecast: 22.7% p.a.
Lectra's earnings are forecast to grow significantly at 22.71% annually, outpacing the French market, although revenue growth is slower. Despite trading below estimated fair value, its Return on Equity is expected to remain low. Recent product innovation with Apogy, a cloud-based solution leveraging artificial intelligence for product development, highlights Lectra's strategic focus on enhancing operational efficiency and creativity in the fashion industry. However, recent financial results show a decline in sales and net income compared to last year.
- Take a closer look at Lectra's potential here in our earnings growth report.
- Upon reviewing our latest valuation report, Lectra's share price might be too optimistic.
Vaisala Oyj (HLSE:VAIAS)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Vaisala Oyj specializes in providing weather, environmental, and industrial measurement solutions across various global markets including North and South America, Europe, the Middle East, Africa, and the Asia Pacific with a market cap of €2.32 billion.
Operations: The company's revenue segments include Industrial Measurements, which generated €258.30 million.
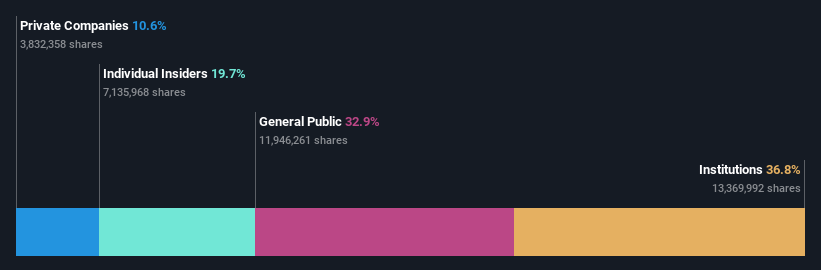
Insider Ownership: 18.2%
Earnings Growth Forecast: 14.7% p.a.
Vaisala Oyj, known for its high insider ownership, is poised for moderate growth with earnings expected to rise at 14.7% annually, slightly outpacing the Finnish market. Recent initiatives include launching Vaisala Care for Data Centers and securing a €25 million contract to modernize Indonesian airport weather systems. Trading below estimated fair value, it shows a strong Return on Equity forecast of 23.1%. While insider trading activity has been minimal recently, the company's strategic moves bolster its growth prospects.
- Get an in-depth perspective on Vaisala Oyj's performance by reading our analyst estimates report here.
- Our valuation report here indicates Vaisala Oyj may be overvalued.
Egetis Therapeutics (OM:EGTX)
Simply Wall St Growth Rating: ★★★★★★
Overview: Egetis Therapeutics AB is a pharmaceutical company focused on developing and commercializing orphan drugs in Sweden and internationally, with a market cap of approximately SEK4.62 billion.
Operations: The company's revenue primarily comes from its Emcitate segment, which generated SEK66 million.
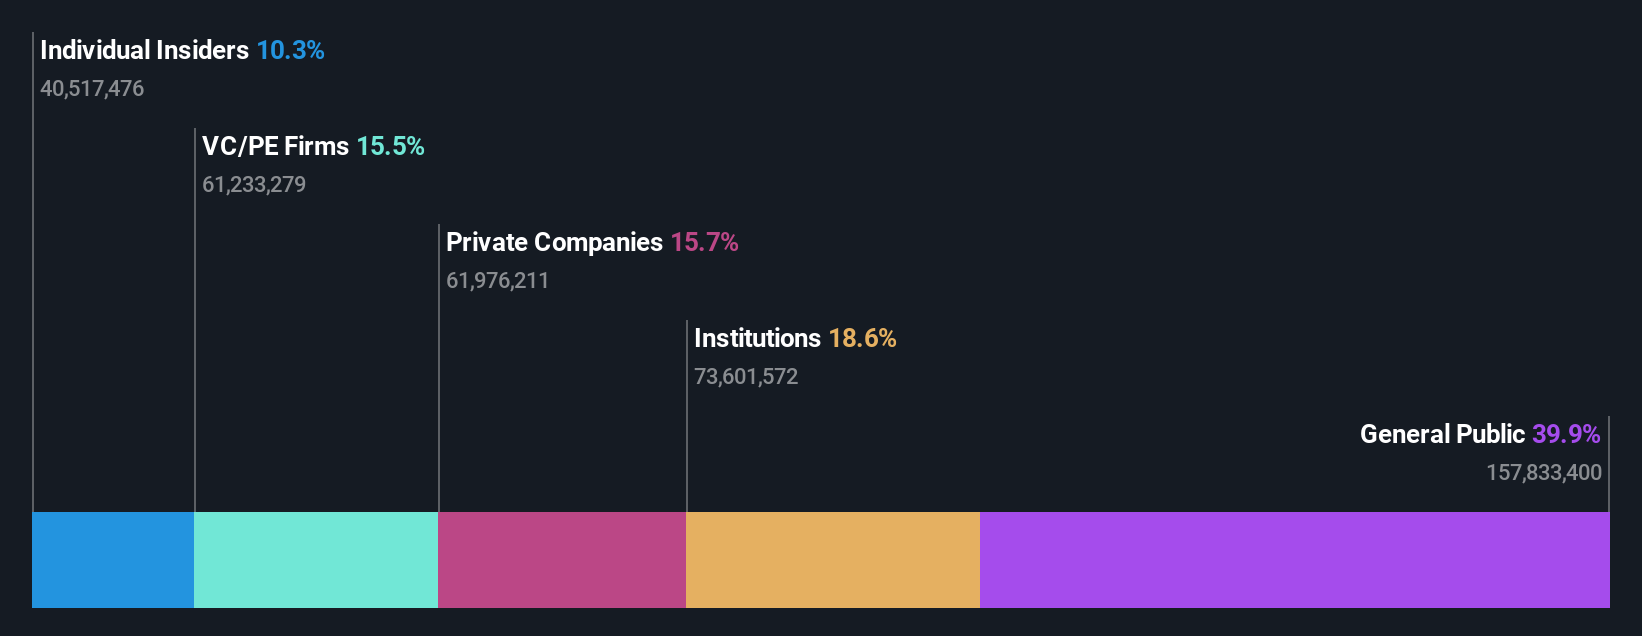
Insider Ownership: 18.4%
Earnings Growth Forecast: 49.5% p.a.
Egetis Therapeutics, with significant insider ownership, is positioned for robust growth as its revenue is forecast to rise 36.8% annually, outpacing the Swedish market. The recent FDA approval of EMCITATE for MCT8 deficiency marks a pivotal milestone, enhancing its U.S. market presence alongside strategic partnerships like PANTHERx Rare. Despite past shareholder dilution and net losses (SEK 108.9 million in Q2), Egetis trades significantly below fair value and aims for profitability within three years.
- Navigate through the intricacies of Egetis Therapeutics with our comprehensive analyst estimates report here.
- Our expertly prepared valuation report Egetis Therapeutics implies its share price may be too high.
Next Steps
- Unlock our comprehensive list of 200 Fast Growing European Companies With High Insider Ownership by clicking here.
- Ready To Venture Into Other Investment Styles? Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com