
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Nokia Oyj (HLSE:NOKIA) Could Be 39% Undervalued Following Arelion AI Network Trial
Arelion’s recent live field trial using Nokia Oyj (HLSE:NOKIA) 1830 Global Express Super C and Super L technology put fresh attention on the group’s role in high capacity optical networks for AI era data traffic.
Nokia Oyj’s recent customer wins with Arelion, ICEYE and Zain KSA come after a sharp re-rating in the shares, with the 1-year total shareholder return at 109.32% and the year-to-date share price return at 68.54%, even as the 90-day share price return has declined 11.84% and near-term momentum has cooled.
Scan for other AI infrastructure plays riding similar data traffic tailwinds with our hand-curated 92 AI infrastructure stocks as you assess how Nokia Oyj fits into your portfolio.
Nokia Oyj has more than doubled holders’ money over 12 months, even as the last quarter cooled. Is that a cue to wait for a pullback, or to value what the current price already offers?
Most Popular Narrative: 39% Undervalued
The most followed narrative values Nokia Oyj at €15.16 per share, compared with the last close at €9.31, which points to a sizeable valuation gap that investors are actively debating. That gap rests on a story about cash, AI exposure, and new end markets that goes well beyond short term share price swings.
Nokia delivered a strong second quarter, reporting revenue of €4.815 billion and earnings per share of €0.07, supported by growing demand for AI and cloud-related solutions. The company is also expanding its presence in the defense sector through AI-powered tools for 5G networks, creating additional opportunities to diversify revenue and strengthen long-term growth prospects.
See why 11 investors see Nokia Oyj as 39% undervalued.
According to TheTurntTomato, that fair value of €15.16 implies Nokia Oyj trades at roughly a 39% discount, with the narrative anchored on AI and cloud demand, a solid cash position, and expansion into defense and private networks. The implied discount rate of 7.68% in this story reflects the return hurdle used to assess those future cash flows, not a forecast of what Nokia Oyj shares will deliver.
Result: Fair Value of €15.16 (UNDERVALUED)
Still, Nokia Oyj’s recent 90 day share price decline and a 66.44x future P/E assumption leave the AI and defense narrative sensitive to sentiment reversals.
Find out about the key risks to this Nokia Oyj narrative.
Another View: Nokia Oyj Through The Earnings Lens
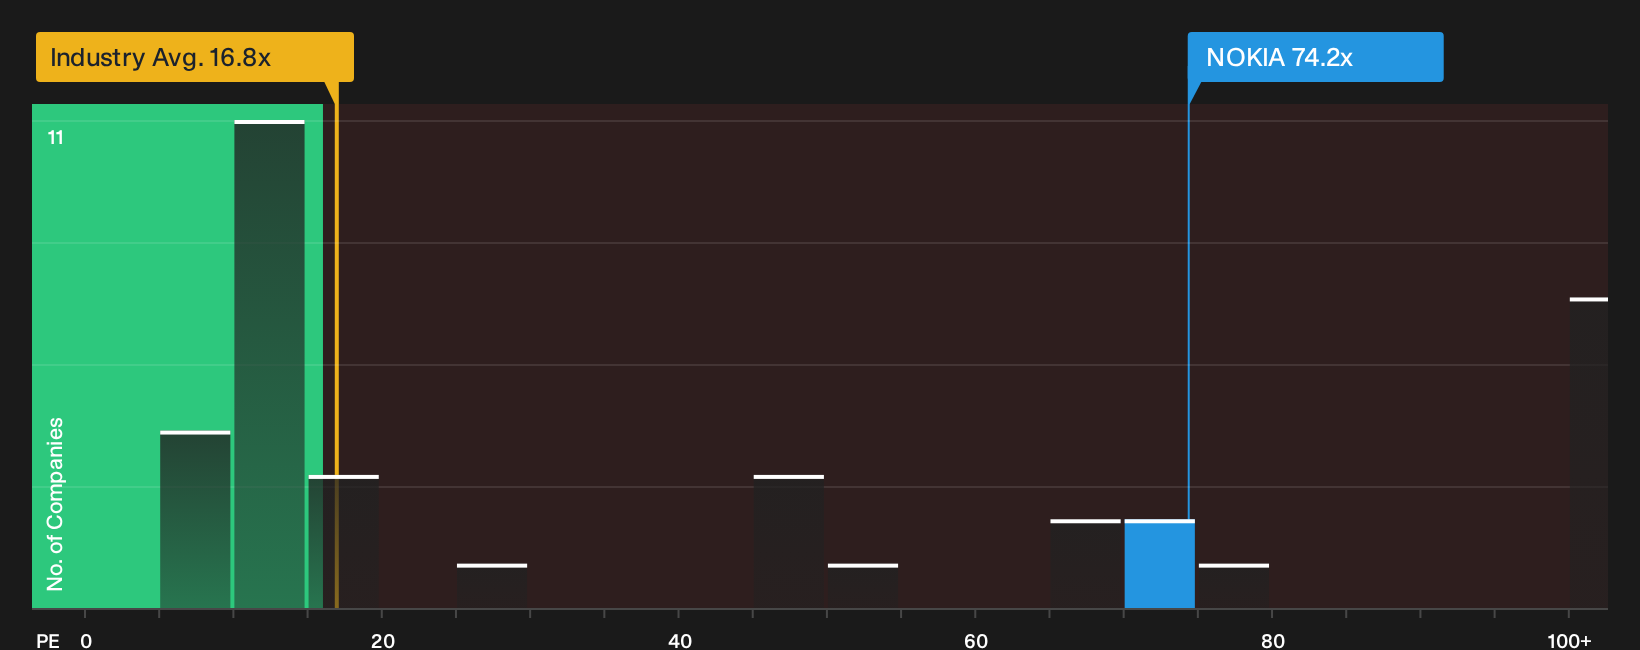
The story looks very different once the focus shifts from discounted cash flows to the P/E ratio. Nokia Oyj trades at 74.2x earnings, compared with a 42.7x peer average and a European communications sector average of 16.8x, while the fair ratio sits at 57.3x.
That mix points to a stock that screens as inexpensive on cash flow models yet carries a richer earnings multiple than both peers and the fair ratio. This raises a simple question for you: Is the market correctly pricing in Nokia Oyj’s growth forecasts, or just paying up for the current AI story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Nokia Oyj is split, which is exactly when it can be useful to move quickly and stress test the numbers yourself rather than follow the crowd. To see both sides clearly, start with the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Nokia Oyj?
If you stop with Nokia Oyj, you only see a fraction of what the market is offering. Cast the net wider so the next opportunity does not pass you by.
- Target steady cash generators by reviewing companies in our 179 high quality undervalued stocks that combine earnings power with prices that may not fully reflect their fundamentals.
- Prioritise resilience and sleep better at night by scanning the 223 resilient stocks with low risk scores for businesses with lower risk profiles and more robust financial traits.
- Hunt for future standouts early by checking the 618 high quality undiscovered gems before wider attention and fresh capital crowd into the same ideas.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com