
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
F5 (FFIV) Stock Could Be 48% Overvalued As WAAP Recognition Lands
F5 has delivered a powerful multi year run, so the key issue now is whether the cash the business can generate still lines up with where the stock trades today. With sentiment shaped by both recent gains and a busy product roadmap, the Discounted Cash Flow (DCF) view of those future streams matters more than ever.
- Over the past 3 years the share price has returned 211.7%, which puts a lot of future cash flow assumptions under the microscope for anyone coming in now.
- Recent product updates around cloud native network functions and WAAP capabilities may support expectations for more durable software like cash generation, which feeds directly into any intrinsic value estimate based on future cash flows.
- What if you looked at F5 through its earnings instead? See what F5's 37.4x P/E says about the price.
The issue now is whether the current price for F5 is adequately supported by the cash flows implied by a Discounted Cash Flow (DCF) intrinsic value estimate.
If you want to stress test this same cash flow question beyond F5, compare it with companies in the 92 AI infrastructure stocks.
Is F5 Getting Expensive on Cash Flow?
The Discounted Cash Flow (DCF) model here projects what F5 could return to shareholders through future free cash generation. F5 produced around $994 million of free cash flow over the last twelve months, and the projection set points toward a pattern of relatively steady, slightly growing cash flows over the next decade rather than a surge.
Those cash flows are being discounted back and compared with a share price of $479.83. On that basis, the DCF projections put F5's estimated intrinsic value substantially below the current share price. The recent recognition as a Leader in IDC’s WAAP assessment helps explain why the market is willing to pay a richer multiple to access that security franchise, even though the cash flow model itself screens as less generous at today’s price. Find out what F5 could be worth using our Discounted Cash Flow (DCF) estimate.
The F5 Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up exactly where this F5 valuation question leaves off by spelling out which assumptions on growth, margins and earnings would need to hold for the stock to be worth materially more or less than today, all housed on the Community page. Each narrative ties a specific fair value to a clear story about F5's potential catalysts and key risks, so you can track over time which version of events seems to be taking shape.
Community views on F5 split between those who see AI security and hybrid multicloud demand leaving more upside, and others who think expectations already bake most of that in.
Bull case: 7% undervalued
"AI inference moving into production, with F5 already tied into AI data delivery, AI factory load balancing and AI runtime security, creates additional insertion points per customer..."
Discover why this Narrative puts F5 at 7% undervalued.
Bear case: 10% overvalued
"Despite healthy hardware and product trends, F5’s annual recurring revenue grew only 3.3% year over year while some research highlighted customer reluctance to commit to long term software contracts..."
Explore why this Narrative puts F5 at 10% overvalued.
One more F5 signal to check before you move on
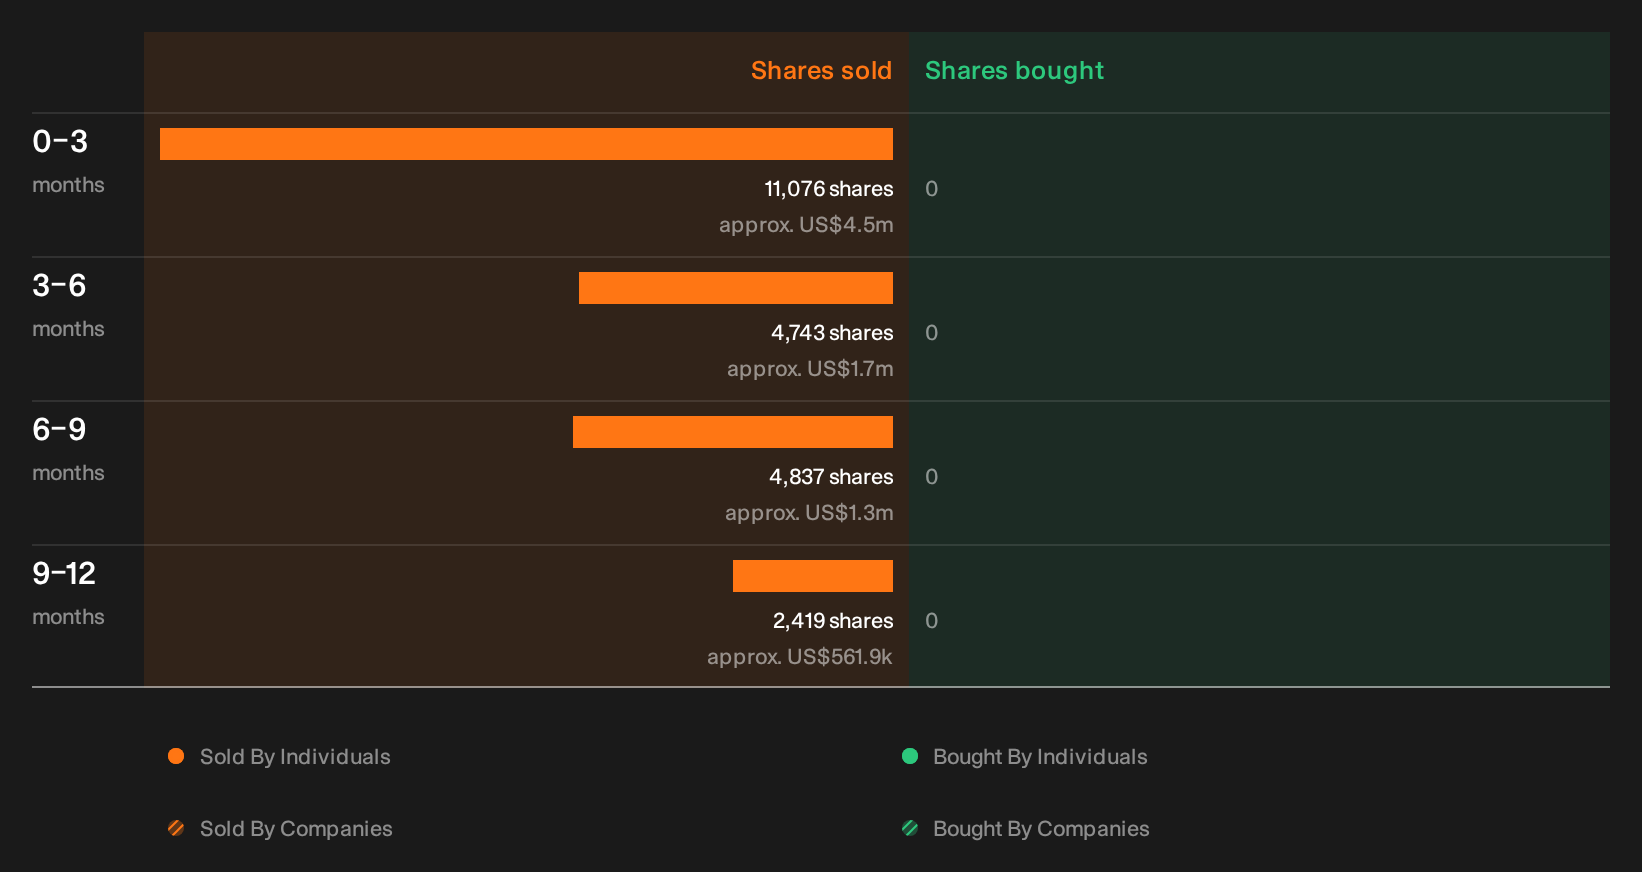
Before acting on any view of F5, it is worth knowing that recent insider activity has been flagged by our checks, with who sold, how much and what it might mean still for you to review. See the recent insider selling flagged for F5.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com