
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
EchoStar (ECHO) Stock Looks Expensive Despite Its Huge Three Year Run
EchoStar has been on a wild longer term ride, yet with the share price around US$94.84 today the real question is how well that quote lines up with the revenue the business is actually producing. For anyone looking at the stock now, the live issue is whether EchoStar's current market value can be explained by its sales rather than by headlines alone.
- EchoStar has delivered a very large gain over the past 3 years, which puts real pressure on the current value to be supported by the scale and quality of its sales base.
- The recent exit of DISH DBS from Chapter 11 after cutting US$4.35b of debt may support a cleaner capital structure for the wider group, which can influence how investors think about the relationship between EchoStar's revenue and its equity value.
- Your read on EchoStar is one view; the desks covering it have another. See what analysts think EchoStar's shares could be worth.
The issue now is whether EchoStar's present share price is adequately explained by the level of sales the business is generating.
If you want a wider set of ideas where price is weighed against sales rather than headlines, a focused screen of 29 high quality undervalued stocks can serve as a useful second starting point for your research.
Is EchoStar Getting Expensive on Sales?
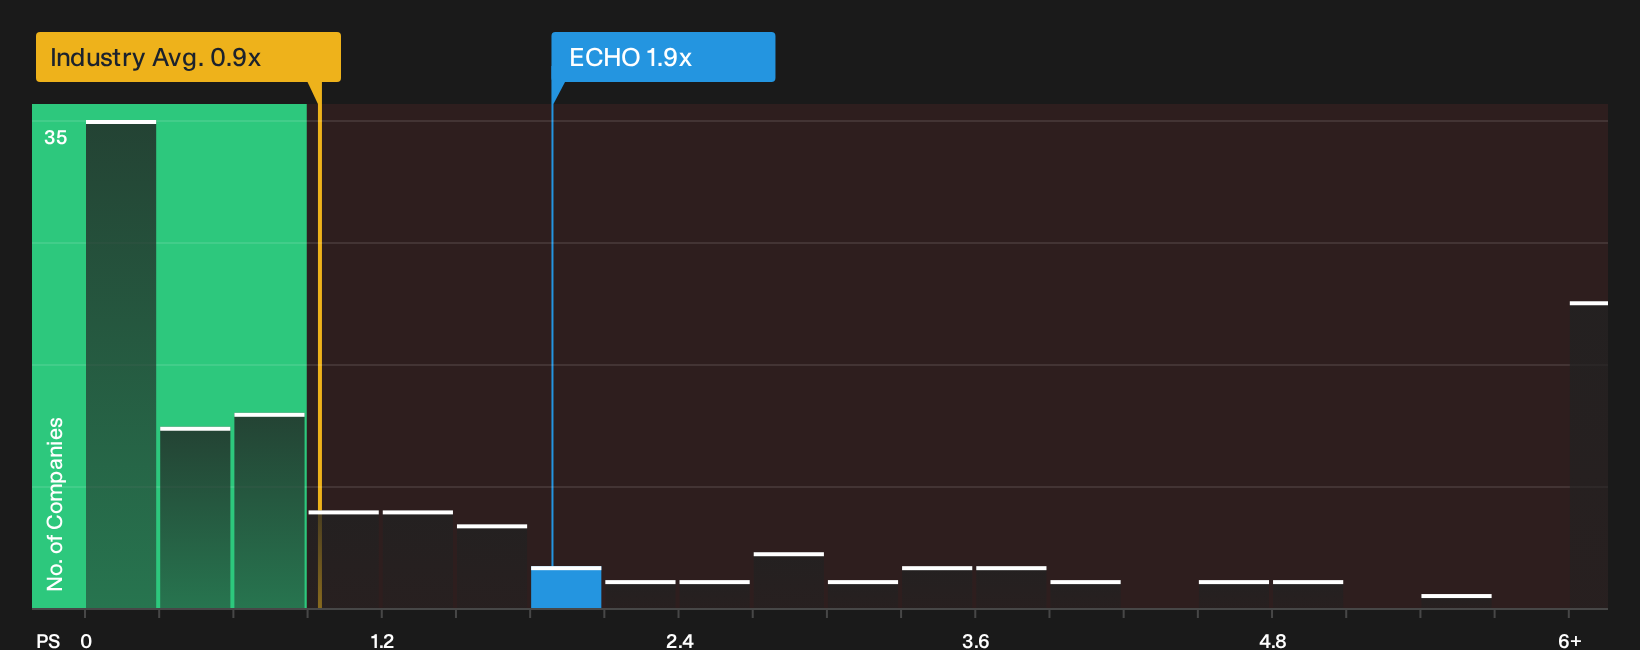
P/S fits EchoStar because investors are currently weighing the value of its revenue base more than its reported earnings or free cash flow. On that lens, the stock trades on a P/S of about 1.9x, which is higher than both the broader media industry average of roughly 0.9x and a peer group closer to 0.9x as well. The tailored fair multiple, which adjusts for EchoStar's specific mix of growth profile, margins, scale and risk, sits below the current level, so on this framework the shares screen as overvalued on sales.
Because DISH DBS recently exited Chapter 11 after cutting US$4.35b of debt, some investors may be giving EchoStar extra credit in the P/S for a cleaner group balance sheet, even though the stock already trades at a premium to sector revenue multiples. Anyone considering EchoStar now needs to decide whether the quality and durability of its revenue stream justify paying more than both industry norms and the tailored benchmark that the valuation model suggests is appropriate for the business. Explore the numbers behind EchoStar's P/S valuation.
The EchoStar Narrative: What Would Justify Today's Price?
EchoStar Narratives on Simply Wall St pick up where this pricing question leaves off and explain which paths for revenue growth, profitability and earnings would need to hold for the stock to appear meaningfully richer or cheaper than it does today. Each scenario links its figures to a specific view on how EchoStar's growth, margins and risks might change. This gives you a reference point you can return to as new information appears on the Community page.
EchoStar fans and skeptics are looking at the same bundle of spectrum, debt and SpaceX exposure and reaching very different conclusions on value.
Bull case: 26% undervalued
"Success in monetizing EchoStar's substantial spectrum assets either through launching lucrative new services, entering wholesale partnerships with global carriers, or potential spectrum sales/leases could unlock significant one-time gains or ongoing income…"
Discover why this Narrative puts EchoStar at 26% undervalued.
Bear case: 116% overvalued
"Before the big spectrum shuffle, this company was struggling, their mobile business was a non-starter, they were hemorrhaging cash for years…"
Explore why this Narrative puts EchoStar at 116% overvalued.
One more EchoStar angle that should not be ignored
Valuation only tells part of EchoStar's story, and the research checks have flagged specific risk markers that deserve your attention before you get too comfortable with the headline numbers. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com