
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Reliance (RS) Stock Looks Expensive As Its 193% Five Year Run Continues
Reliance has delivered a strong run over the past few years, and the stock now trades at a level that puts fresh attention on what investors are paying for its earnings. With that backdrop, the key issue for you is whether the recent share price fully lines up with what the company currently earns and may be expected to earn.
- Over the past 5 years, Reliance has returned 193.3%, which puts a lot of past optimism into the price and raises the stakes for what its profit stream needs to support today.
- The nomination of senior Reliance executive Dhanraj Parimal Nathwani to the Rajya Sabha suggests deeper links between the group and policymaking circles, which can influence how investors think about regulatory risk, capital allocation and the durability of earnings.
- There is a second opinion on Reliance worth weighing. See what analysts think Reliance's shares could be worth.
The issue now is whether Reliance's current share price is adequately supported by its earnings profile when judged against the Fair Ratio benchmark.
If you want to stress test Reliance's earnings question against a wider field of opportunities, line it up next to the 29 high quality undervalued stocks.
Has Reliance Run Too Far on Earnings?
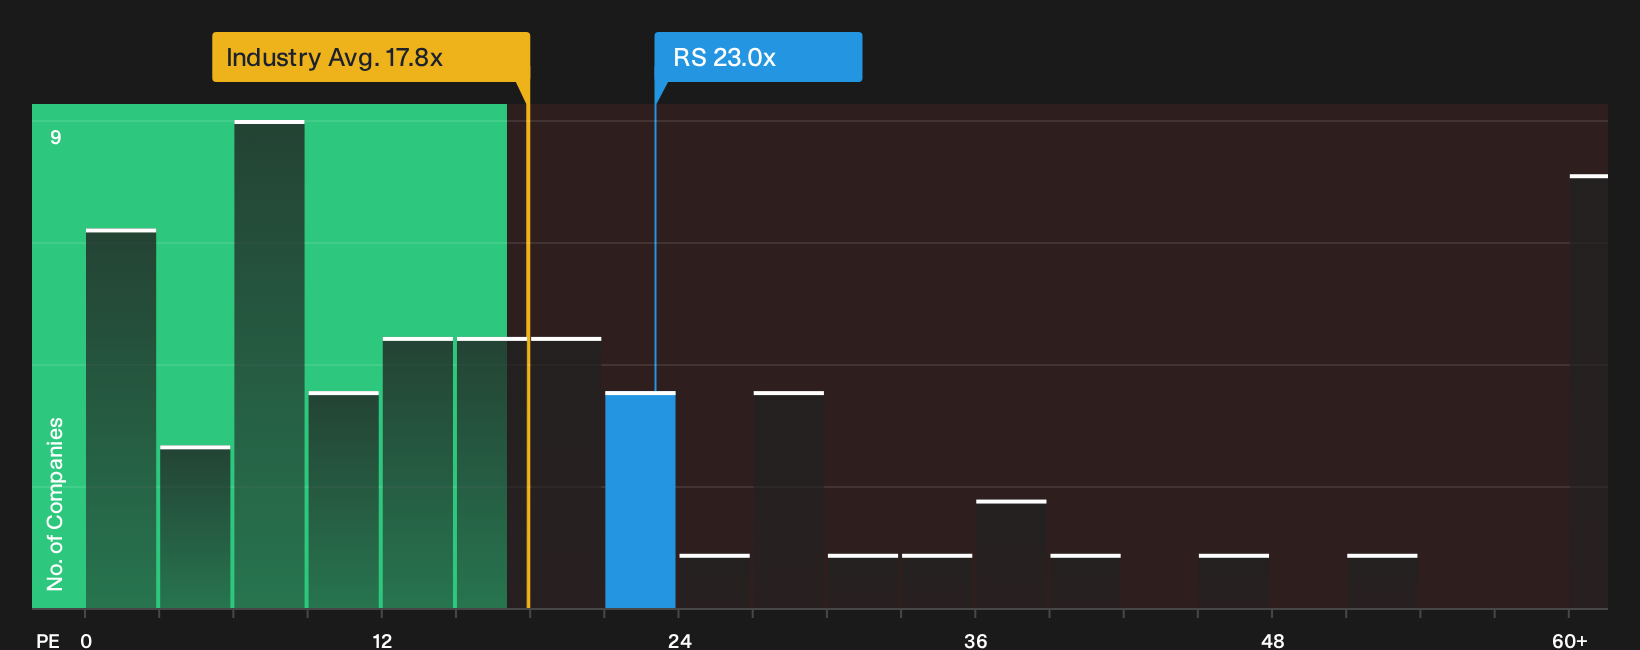
The P/E ratio is a useful lens for Reliance because earnings are a central driver of how investors value metals and mining stocks. Reliance currently trades on a P/E of 23.0x, which is higher than both the Metals and Mining industry average of 17.8x and the peer group average of 17.3x. That points to investors assigning a premium valuation to the earnings stream at today’s share price.
On this framework, the Fair Ratio model, which blends Reliance specific factors like growth profile, profitability, size and typical sector risks into a tailored benchmark, suggests the current P/E sits above where it might usually be anchored. Despite the political visibility that comes with Dhanraj Parimal Nathwani’s Rajya Sabha nomination and the potential influence investors may read into that, the stock still prices in a richer multiple than both sector norms and this Fair Ratio yardstick. Explore the numbers behind Reliance's P/E valuation.
The Reliance Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St’s Community page pick up where Reliance's valuation puzzle leaves off and spell out which paths for growth, margins and earnings would need to play out for the shares to look materially stronger or weaker than today’s level. Each view links its number to a specific take on how Reliance's growth, profitability and risks could evolve, so you have a reference point to revisit as new information emerges.
One of the top community narratives on Reliance: roughly fairly valued
"Heightened data center construction, public infrastructure work and power grid projects are currently supporting strong non residential construction demand that represents roughly one third of Reliance sales…"
Discover why this Narrative puts Reliance at roughly fairly valued.
One more Reliance check that belongs next to the valuation work
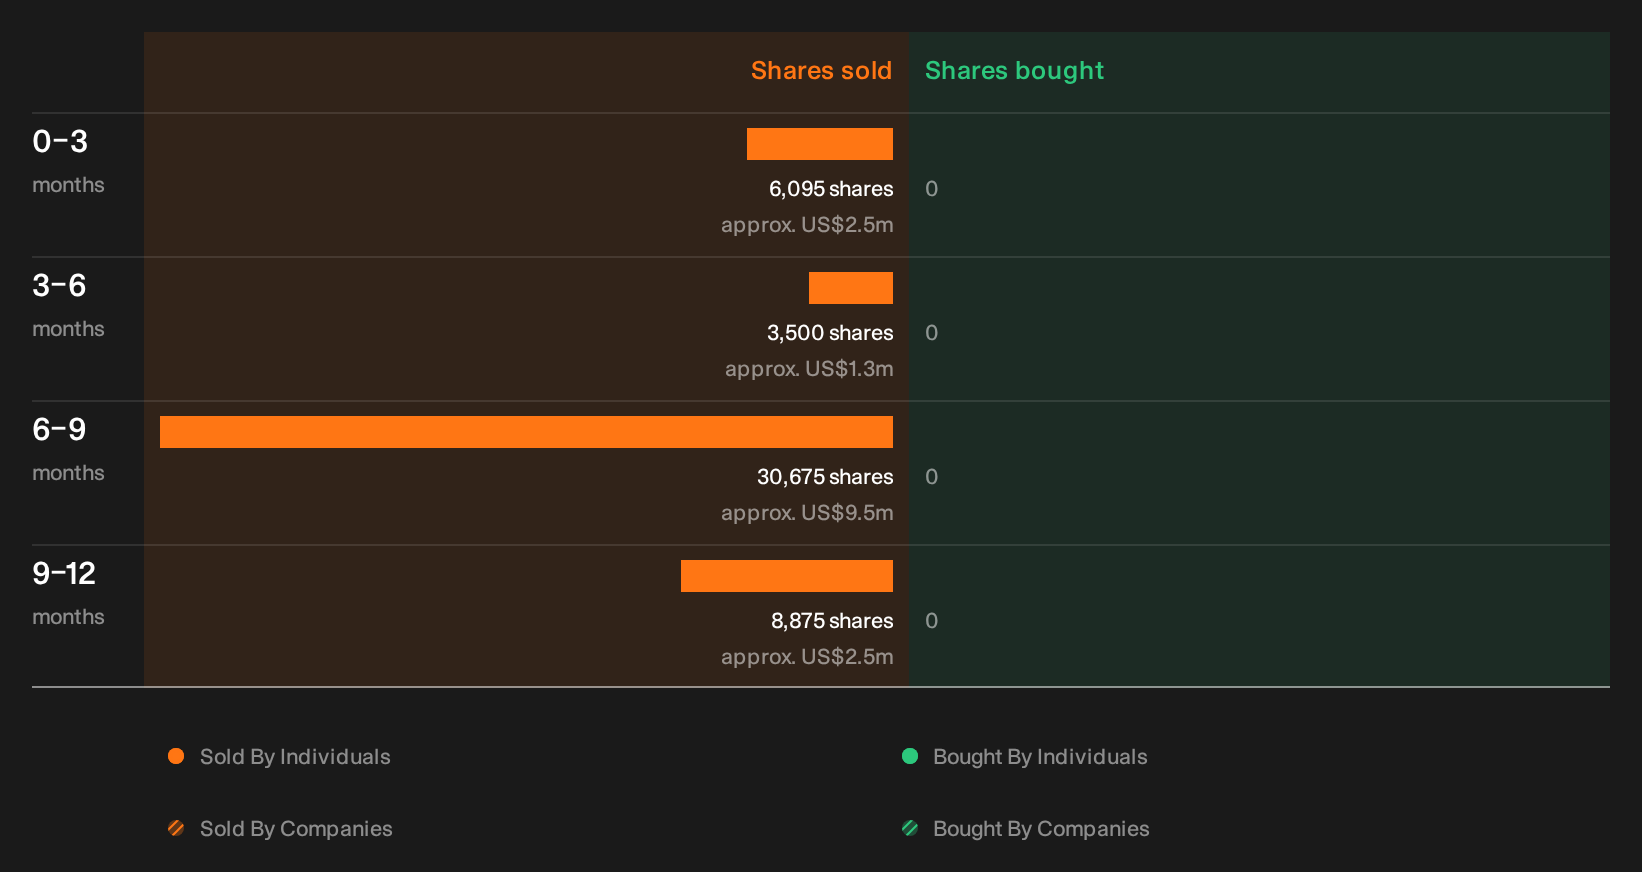
Share price comparisons tell only part of the story, because recent dealings by people inside Reliance can add a different signal about risk and confidence that you may want to inspect closely. See the recent insider selling flagged for Reliance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com