
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Western Midstream Partners (WES) Stock Still Looks Below Fair Value As 200% Run Continues
Western Midstream Partners has delivered a strong run for holders in recent years, which naturally raises a question about whether its current share price still lines up with the earnings the partnership is generating. With the stock recently closing at US$45.62, the key issue now is how much of that earnings story is already reflected in the valuation.
- The unit price has gained 200.4% over the past 5 years, which puts real weight on whether today's earnings can shoulder that kind of rerating.
- For a midstream business built around long term fee based contracts, the durability and growth of earnings may support a different valuation profile than more commodity exposed energy producers.
- The analysts covering Western Midstream Partners have run their own numbers. See what analysts think Western Midstream Partners's shares could be worth.
For investors, the debate is whether Western Midstream Partners' current price is properly anchored to the earnings power of the partnership.
If you are weighing whether Western Midstream Partners' current P/E still makes sense after a 200.4% five year return, it can help to compare it with 29 high quality undervalued stocks.
Does Western Midstream Partners Look Undervalued on Earnings?
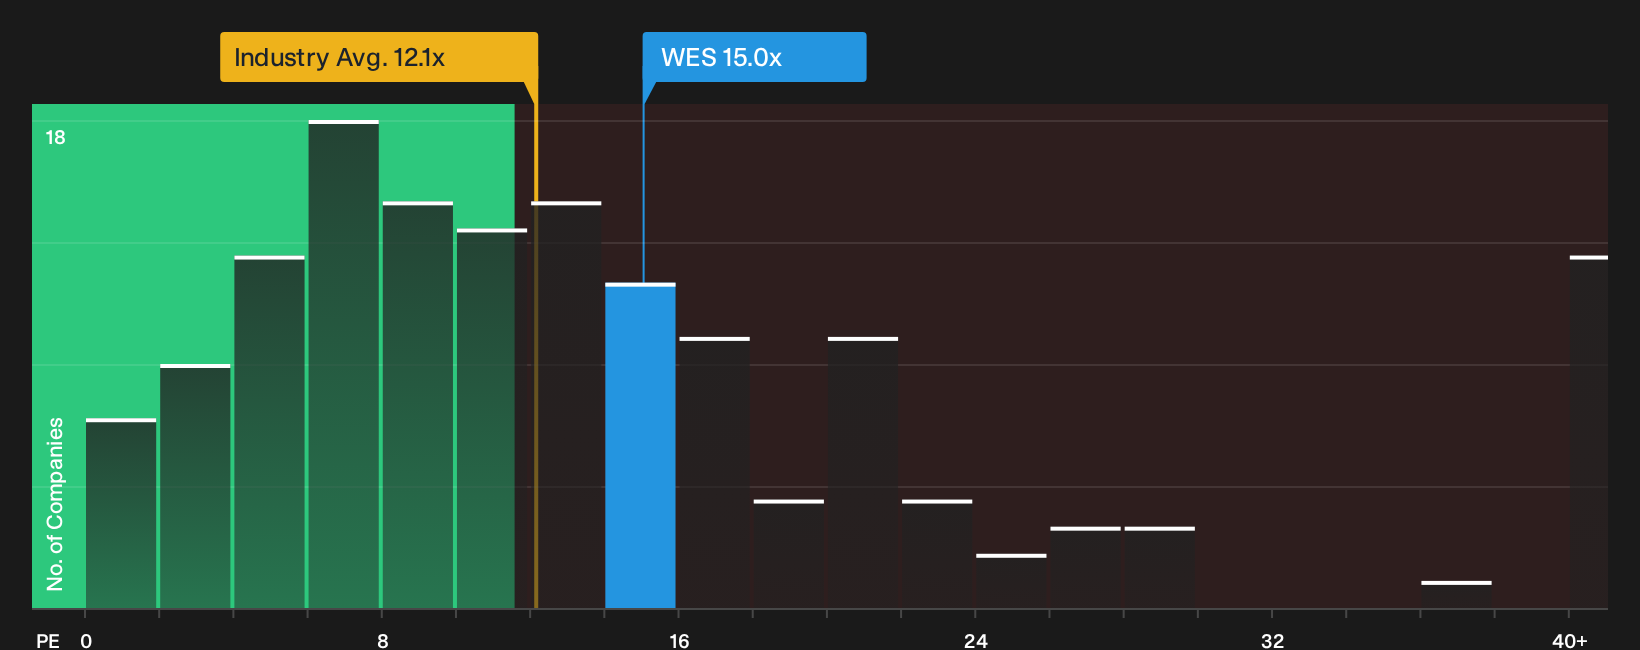
The P/E ratio suits Western Midstream Partners because earnings are a central part of how investors frame midstream valuation. From this perspective, the units trade at about 15.0x earnings, which is above the broader Oil and Gas sector average of roughly 12.1x. That indicates the partnership is priced at a premium to many commodity-exposed operators that share the same sector label but have different cash flow profiles.
Compared with closer peers, however, Western Midstream Partners trades at a lower multiple than the group, with the peer set around 20.4x. The fair P/E that screens for the partnership, which blends its growth outlook, profitability, size and risk profile, sits higher than the current 15.0x level, so the stock screens as undervalued on this framework. For anyone already following the story, the key judgment is whether the earnings that support this multiple appear robust enough to justify closing that gap or whether the discount reflects risks that matter to you. Explore the numbers behind Western Midstream Partners's P/E valuation.
The Western Midstream Partners Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off for Western Midstream Partners, explaining which combinations of growth, margins and earnings would need to occur for the units to justify a meaningfully higher or lower price than today. These narratives are available on Simply Wall St's Community page. Rather than centering on a single multiple or model line, each one sets out the assumptions behind its view of fair value so you can compare them with future results.
One of the top community narratives on Western Midstream Partners: 8% undervalued
"The main factor that has to go right is continued execution on integrating Brazos, building Pathfinder and North Loving II on budget…"
Discover why this Narrative puts Western Midstream Partners at 8% undervalued.
One more angle on Western Midstream Partners that could change how you see today’s price
Valuation tells you what Western Midstream Partners costs today, but the analyst models looking a few years out offer a different lens on where profits and cash generation might land. Explore where analysts expect Western Midstream Partners to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com