
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Free Cash Flow Strength Just Shift Coeur Mining's (CDE) Investment Narrative?
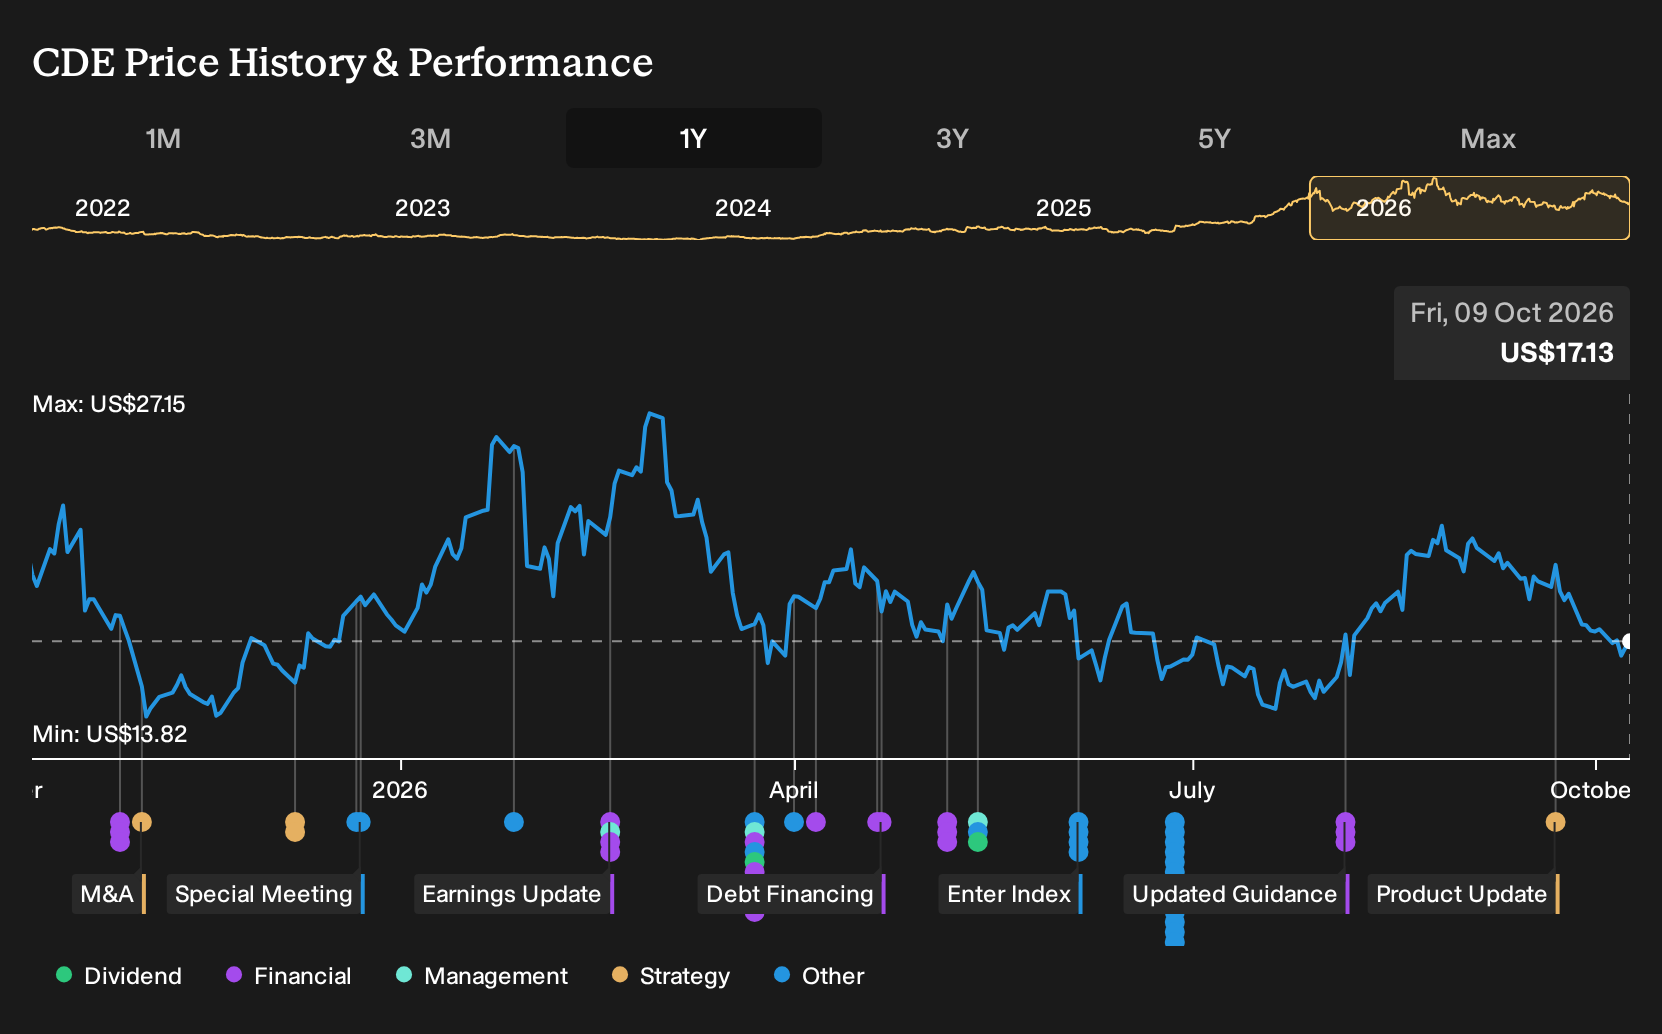
- Coeur Mining recently reported free cash flow of US$1.2b over the last twelve months, supported by stronger operating margins and the integration of two Canadian mines. At the same time, the company reduced its 2026 gold output guidance because Rainy River and New Afton are scaling up more slowly than planned.
- The combination of higher free cash flow and lower near term gold production guidance requires investors to weigh improved cash generation against execution risk at newly integrated assets and the timing of the production ramp up.
- This article examines how Coeur Mining's investment narrative is influenced by stronger free cash flow alongside slower scaling at key Canadian mines.
Compare Coeur Mining's free cash flow story with other producers by scanning a curated list of 36 elite gold producer stocks that may also be reshaping their guidance and capital priorities.
Coeur Mining Investment Narrative Recap
To be a shareholder in Coeur Mining, you need to be comfortable with a story built around free cash flow from a multi asset gold and silver portfolio and the operational progress of its Canadian mines. The jump to US$1.2b in free cash flow sets expectations that these operations can fund heavy capital needs without constant balance sheet strain.
The near term catalyst now sits in how quickly Rainy River and New Afton can move closer to planned output after slower scaling and lower 2026 guidance. The key risk is execution slippage at these assets, which could expose Coeur Mining to timing mismatches between cash generation, sustaining capex and future project development.
The most relevant recent update is management’s expectation of about US$1.5b in free cash flow for 2026 alongside reduced 2026 gold production guidance. That pairing matters because it suggests Coeur Mining is leaning on margin efficiency and existing operations to keep cash flowing even while two Canadian mines lag their original ramp up plans.
For you, the operational question is whether that cash flow outlook holds if scaling at Rainy River and New Afton remains slower than intended. Any persistent delay could constrain how aggressively Coeur Mining funds exploration, manages high capital intensity across assets like Rochester and Las Chispas, and addresses prior shareholder dilution without adding further financial pressure.
Coeur Mining's current analyst narrative points to about US$5.1b in revenue and US$1.5b in earnings by 2029, based on expectations for roughly 17.0% yearly revenue growth and an earnings rise of about US$649.6m from US$850.4m today.
Discover why Coeur Mining's fair value indicates a 40% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on Rainy River and New Afton and more on Las Chispas and Rochester. Before this update, they were penciling in about US$5.9b of revenue and US$2.5b of earnings by 2029 for Coeur Mining. That is a far more upbeat story. Use this gap in expectations to compare different forecasts and decide which camp feels closer to your own view, knowing this new free cash flow news could lead both narratives to evolve.
Explore 5 other Coeur Mining fair value estimates, including one that suggests as much as 90% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Coeur Mining research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Coeur Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coeur Mining's overall financial health at a glance.
Looking for more investment ideas beyond Coeur Mining?
If the Coeur Mining story has sharpened your sense of risk, cash flow and production timing, it can be useful to compare it with other businesses that line up more closely with your own preferences on quality, balance sheet strength or income.
- If you want quality at a discount, scan a curated 29 high quality undervalued stocks that pair stronger fundamentals with prices that may not fully reflect them.
- For sturdier balance sheets and less financial strain, filter companies through a list of solid balance sheet and fundamentals (25 results) that keeps an eye on debt, liquidity and funding flexibility.
- If resilience matters more than excitement right now, focus your attention on a 31 resilient stocks with low risk scores that tilts toward steadier business profiles and fewer red flags.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com