
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Energy Stocks To Watch As Oil Prices Shake Global Producers
Energy markets rarely move on headlines alone. When conflict in the Middle East lifts oil benchmarks and higher UK inflation squeezes government budgets at the same time, the ripple effects can reshuffle winners and laggards across global producers. Investors risk missing important shifts in pricing power and cash flow resilience if they look away now. This article walks through three energy stocks exposed to these shocks and explains why they merit a closer look.
The three stocks below are just a sample of what rises to the surface when energy markets get stressed, and the full screen turned up 50 more large producers with equally compelling stories that are not covered here. To sort through that wider group by size, region, balance sheet strength and income profile, head straight into the Global Energy Producers and Oil & Gas Majors screener.
Subsea 7 (OB:SUBC)
Overview: Subsea 7 delivers large offshore engineering, construction and installation projects that connect seabed oil, gas and wind assets to energy markets.
Operations: The group generates most of its revenue from Subsea and Conventional projects at US$6.1b, with Renewables contributing about US$1.3b.
Market Cap: NOK100.3b
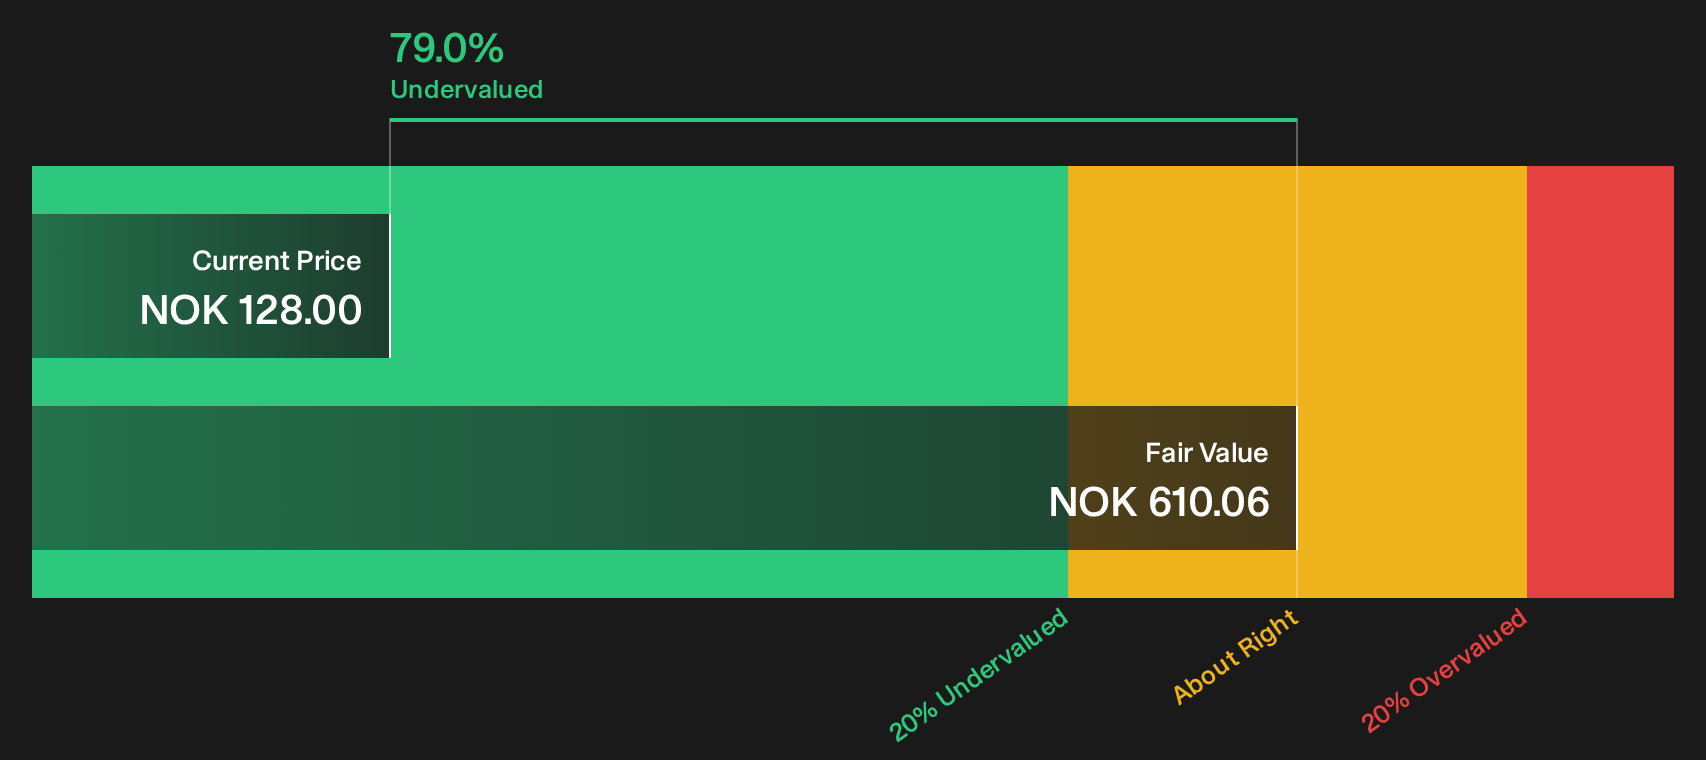
Subsea 7 matters in this screener because it sits where huge offshore oil and gas developments meet the need for dependable long-cycle project execution.
"The continued robustness of Subsea 7's order intake ($2.5 billion this quarter, 1.4x book-to-bill) and rising backlog (nearly $12 billion) reflect high global demand for offshore oil & gas and brownfield redevelopments, underpinned by persistent growth in energy needs and the push to maximize output from existing infrastructure, supporting revenue visibility and long-term earnings growth."
The real swing factor for Subsea 7 now is how one concentrated pressure on future offshore activity shapes margins and contract pricing.
That margin pressure is exactly what Subsea 7’s full narrative for Subsea 7 unpacks, including where contract terms could decouple earnings power from headline oil price swings.

Topaz Energy (TSX:TPZ)
Overview: Topaz Energy is a Canadian royalty and infrastructure company that collects fees and royalties from upstream oil and gas production.
Operations: Topaz Energy generates about CA$274.9 million from royalties and CA$94 million from infrastructure services, all sourced from Canada.
Market Cap: CA$4.5b
Topaz Energy gives you exposure to large scale oil and gas output through royalties and midstream assets. It sits alongside traditional producers in this global energy majors screen without taking on full drilling or operating risk itself.
"The asset-light royalty model with high cash conversion (91% free cash flow margin) and low operating expenses positions Topaz to maintain strong net margins and resilient earnings as investors continue to seek reliable, high-yielding income sources in a moderate interest rate environment."
What happens to that income profile if a single key assumption about future operator activity and volumes starts to shift?
If that assumption is starting to wobble, read the full narrative for Topaz Energy to see how Topaz Energy’s royalty engine could either keep income accelerating or expose hidden volume risk.

Constellation Oil Services Holding (OB:COSH)
Overview: Constellation Oil Services Holding owns and operates offshore drilling rigs that support oil and gas exploration and production activity in Brazil.
Operations: The business generates about US$789 million from offshore drilling rigs, with all reported revenue currently tied to Brazilian projects.
Market Cap: NOK10.8b
Constellation Oil Services Holding provides direct exposure to offshore drilling within a major producing country, so revenue is closely linked to upstream spending rather than consumer demand. Recent index inclusion, higher recent sales and an 8.84% dividend yield may make it an eye catching option for investors assessing the impact of oil prices, depending on how one unseen pressure on its funding costs evolves.
Those funding pressures are exactly what the 4 key rewards and 1 important warning sign maps out, highlighting where Constellation Oil Services Holding’s yield could be masking either sturdier cash flows or fragile leverage.
Seeking Fresh Alternatives Beyond Oil?
Energy names often move first when headlines hit, but rapid price action can also emerge in less crowded areas of the market. Review potential ideas before momentum accelerates and prices adjust higher.
- Identify under-the-radar resilience in companies with stronger balance sheets by running the list of solid balance sheet and fundamentals (202 results) while these quieter compounders remain less widely followed.
- Explore exposure to infrastructure supporting AI demand with the 92 AI infrastructure stocks as investors evaluate power and data enablers.
- Assess opportunities related to metal supply constraints using the 33 best rare earth metal stocks while demand themes develop and valuations incorporate evolving conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com