
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Montage Gold (TSX:MAU) Koné Funding Plan Keeps Fair Value In Focus
Montage Gold (TSX:MAU) drew fresh attention after CEO Martino De Ciccio outlined how the Koné project is moving toward production, with a clear focus on financing, shareholder dilution, and long term expansion.
Recent trading has been choppy for Montage Gold, with the share price up 2.12% on the day to CA$17.35 but down 9.4% over the past month, even as the 90 day share price return of 12.44% sits against a year to date share price gain of 75.79% and a very large 3 year total shareholder return that is close to 30x. This suggests that investors are weighing the Koné development update against an already strong run and reassessing both growth potential and project risk.
Scan beyond Montage Gold and see how other producers are priced for growth, balance sheet strength, and potential rerating in our hand picked 36 elite gold producer stocks.
After a move that has already turned a small explorer into a multi billion dollar gold developer, the question around Montage Gold is simple. Is the bigger share of the upside still ahead, or already in the rear view mirror once valuation is in focus?
Most Popular Narrative: 26% Undervalued
At a last close of CA$17.35, the leading narrative on Montage Gold points to a fair value of CA$23.50. This frames the recent pullback as a valuation reset rather than the end of the story.
The market already understands that Montage is a serious developer. This is not an undiscovered microcap anymore. The company has re-rated strongly, and the valuation is now pricing in a lot of future success. So the key question is not whether Koné is a real project. It is. The key question is whether Montage can execute construction, start production on schedule, control costs, and keep adding higher-grade satellite ounces to improve the mine plan.
See why 18 investors see Montage Gold as 26% undervalued.
Result: Fair Value of CA$23.50 (UNDERVALUED)
Still, the story around Montage Gold can change quickly if Koné construction slips, or if cost pressures force extra funding that increases dilution.
Find out about the key risks to this Montage Gold narrative.
Another View On Montage Gold’s Valuation
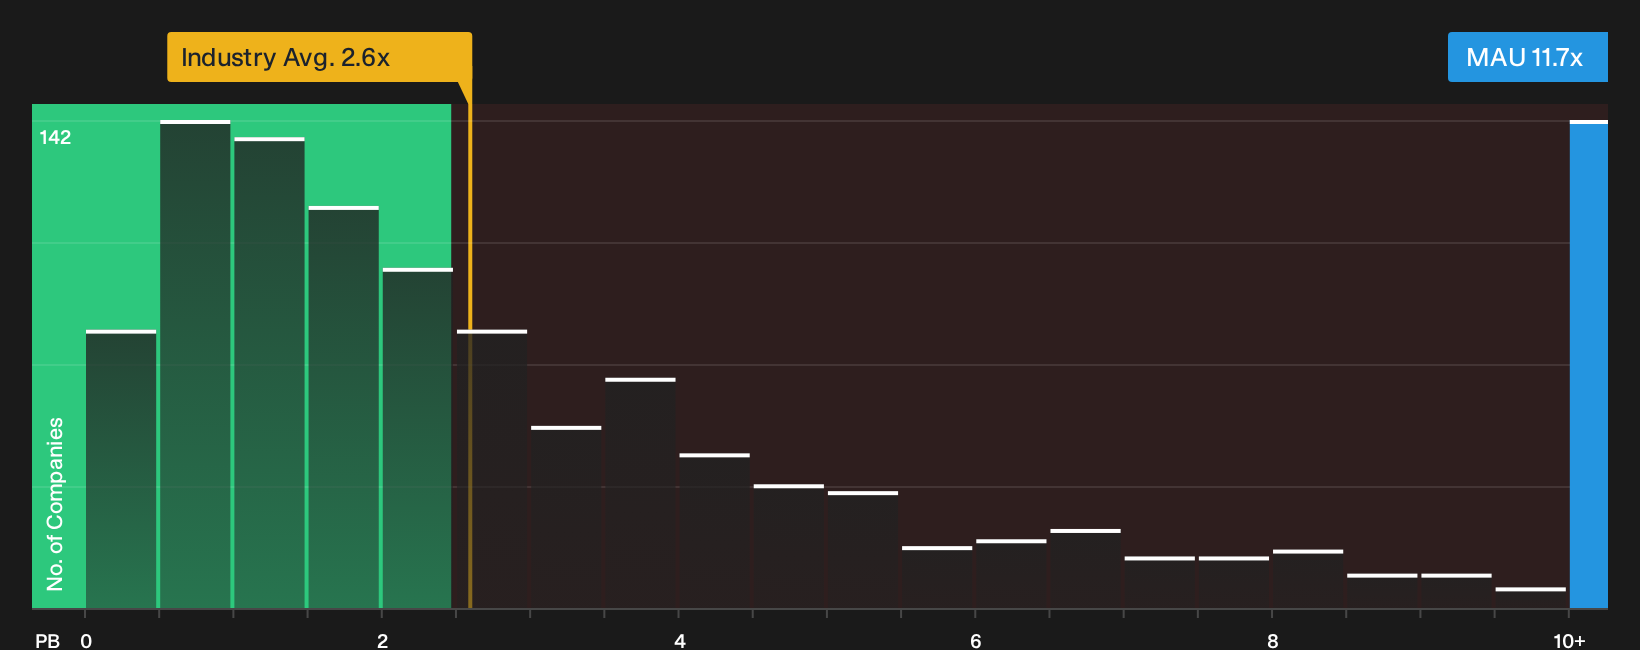
Looking at Montage Gold through its P/B ratio tells a different story. The shares trade at 11.7x book value compared with 2.6x for the wider Canadian metals and mining group and 10.8x for peers. That rich premium points to valuation risk if expectations around Koné slip even slightly.
Investors weighing that premium against the earlier fair value work may want to see what the numbers imply when book value is put under the microscope in more detail, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed sentiment around Montage Gold is clear, with both bullish and cautious voices being prominent. Act quickly, review the data, and weigh the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Montage Gold?
If Montage Gold has sharpened your focus on opportunity and risk, do not stop here. Use the Simply Wall Street Screener to look for your next potential idea.
- Target robust value by scanning companies with strong cash flows and supportive fundamentals through the 8 high quality undervalued stocks.
- Strengthen your income strategy by reviewing high yield opportunities that feature resilient payouts using the 3 dividend fortresses.
- Prioritise resilience by filtering for businesses with healthier finances and sturdier balance sheets in the list of solid balance sheet and fundamentals (7 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com