
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Record Defense Orders Change The Bull Case For Allient (ALNT)?
- Allient recently reported that demand from data center and defense customers is driving momentum in orders, with record booking levels signaling heavy interest in its motion control and power quality products.
- The surge in high value orders suggests Allient’s shift toward more complex industrial and defense applications is starting to reshape how its backlog is composed.
- We will now look at how Allient’s investment narrative could be influenced by this record data center and defense driven order strength.
Scan how Allient’s surge in high value data center and defense orders compares with other infrastructure plays by running through the hand picked 92 AI infrastructure stocks.
Allient Investment Narrative Recap
To own Allient, you need to be comfortable with a story built around higher value motion and power solutions for data centers, industrial automation and defense, supported by record bookings and a US$298 million backlog that is scheduled to ship over the next 3 to 9 months. The short term swing factor is how efficiently that backlog converts into revenue and cash, while STAN cost savings and recent margin gains hold up.
The biggest near term risk is that restructuring costs from actions like the Dothan transition and broader realignment linger, or that new high value orders do not arrive quickly enough to keep backlog healthy once this record wave ships. If efficiency programs deliver smaller gains from here, earnings and Allient’s already expensive P/E could come under pressure.
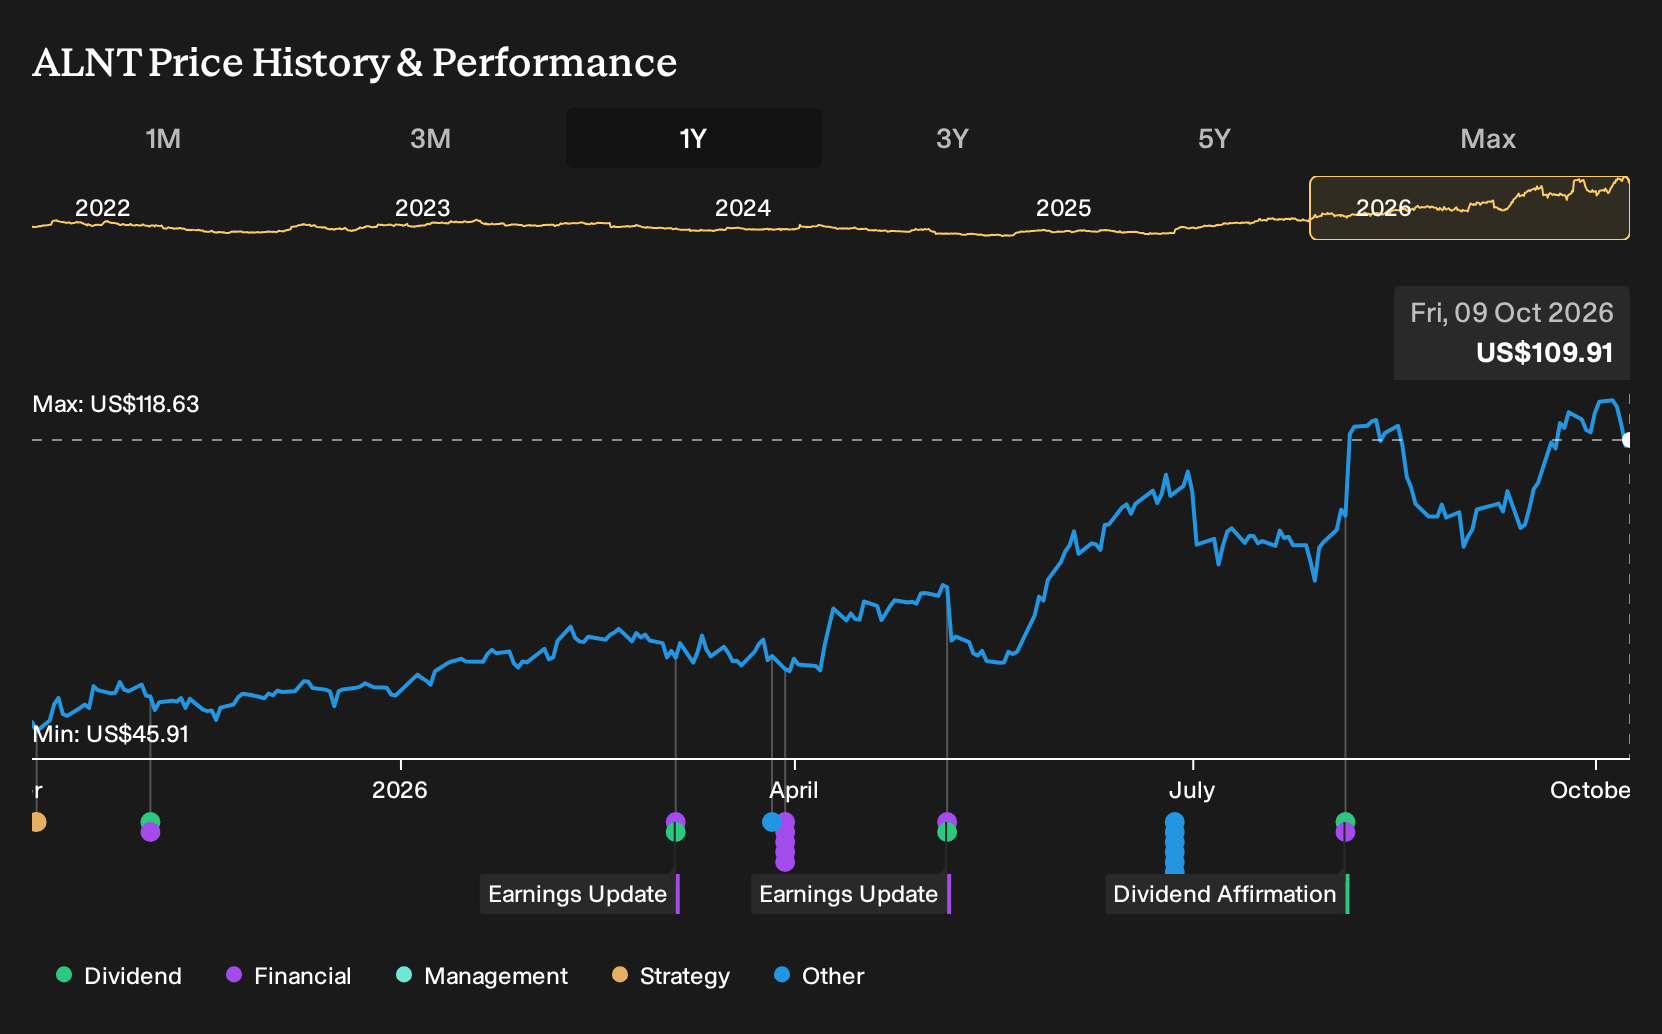
The most relevant recent marker for this data center and defense story is Allient’s Q2 2026 update, where bookings reached US$201.3 million and powered that US$298 million backlog. That order book sits alongside record gross margin of 34.9% and operating margin of 10.2%, supported by STAN driven cost savings that are planned to continue through 2026.
For you as an investor, the key question is execution. Can Allient turn those orders into consistent earnings while absorbing around US$2 million to US$3 million of restructuring expense in 2026 and maintaining quality in data center power quality and automation work? With the stock already trading at a higher P/E than US Electrical peers, any slip in backlog conversion or margin progress could matter quickly.
What Analysts Are Building Into The Allient Story
Consensus forecasts sketch a demanding arc for Allient. Analysts are working off assumed revenue growth of 8.2% a year over the next three years and a move in profit margins from 5.0% today to 7.7% by 2029. On those inputs, projected earnings of US$56.3 million by 2029 compare with earnings today of US$28.6 million. That is roughly a 2x step up in profit that has to come through the income statement for the current narrative to hold.
Those same models tie directly into the valuation debate around Allient. To line up with the analyst view, an investor would need to be comfortable with 2029 revenues of US$727.9 million and earnings of US$56.3 million, all in the context of a future P/E of 47.5x that still sits above the current US Electrical sector multiple of 36.9x. In other words, the story is not only about growing into higher data center and defense exposure; it also assumes investors are still willing to pay a premium multiple for those future earnings.
Allient's narrative projects US$727.9 million revenue and US$56.3 million earnings by 2029. This rests on 8.2% yearly revenue growth and roughly a 2x earnings increase from US$28.6 million today.
Uncover how Allient's fair value indicates a 7% potential upside to its current price before sentiment around Allient’s premium backlog story shifts.
Exploring Other Perspectives
One alternative angle to the Allient story focuses on data center capacity risk. The most pessimistic analysts worry that recent AI buildouts cool, leaving the new Wisconsin and Mexico expansion underused. Before this rally, that group was only penciling in about US$736.6 million of 2029 revenue and US$58.1 million of earnings, so today’s record orders could eventually reshape those expectations.
Explore 2 other Allient fair value estimates, including one that suggests as much as 40% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Allient research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Allient. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Allient's overall financial health at a glance.
Looking For More Investment Ideas Beyond Allient?
Once you have a view on Allient, it can help to set that thesis alongside other opportunities that fit your risk profile, income goals and balance sheet preferences. The Simply Wall St Screener gives you a quick way to line up different types of stocks and test whether Allient still deserves a place in your shortlist.
- If resilience matters most to you, you could start with companies that pair steadier risk profiles with cleaner finances by reviewing the 31 resilient stocks with low risk scores.
- If value is your priority, you could compare Allient with businesses that combine strong fundamentals and room for re rating by running through the 20 high quality undiscovered gems.
- If financial strength is non negotiable, you could focus on companies where debt, cash and profitability look more robust by scanning the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com