
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hinge Health (HNGE) Stock Still Looks Pricey On Earnings Power
Hinge Health has delivered very strong share price gains recently, which puts fresh attention on whether that move lines up with what the business is actually earning. With the stock now trading at US$102.90, the immediate issue for investors is how that price stacks up against its earnings power.
- The share price is up 125.9% year to date, which raises the question of whether the earnings picture has kept pace with the market's optimism.
- The business model depends heavily on converting its digital musculoskeletal care platform into consistent earnings, so any shift in profitability or cost control can materially change what a fair earnings multiple looks like.
- There is a second opinion on Hinge Health worth weighing. See what analysts think Hinge Health's shares could be worth.
For investors, the debate is whether Hinge Health's current share price is justified by its earnings when assessed against the Fair Ratio benchmark.
If you are questioning whether Hinge Health's 125.9% year to date return is fully backed by its earnings power, it can help to compare this story with a focused list of 29 high quality undervalued stocks.
Does Hinge Health Look Pricey on Earnings?
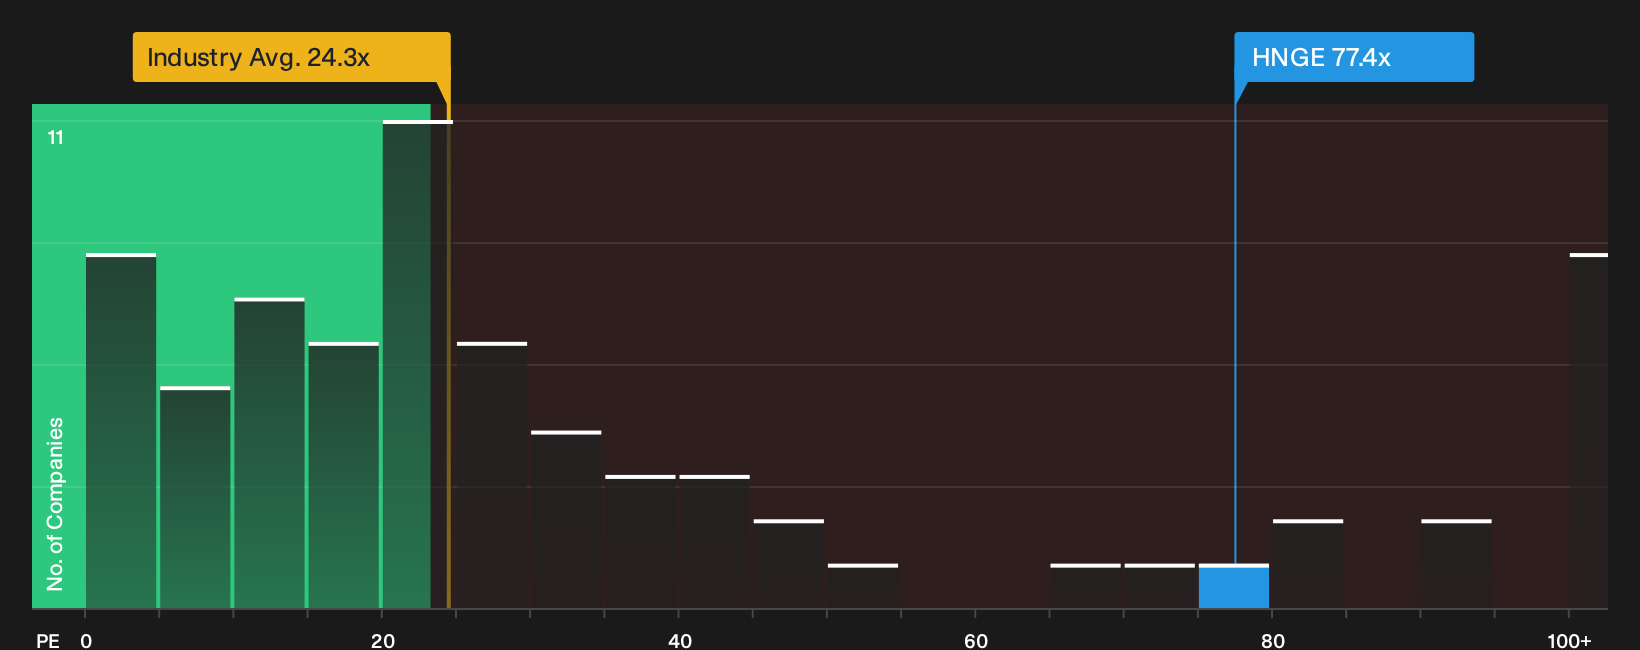
The P/E ratio is a useful lens for Hinge Health because earnings now give you a clear anchor for what the market is paying. At the current share price, the stock trades on a P/E of 77.4x. That is well above the Healthcare sector average of 24.3x, so you are paying a much higher price per dollar of earnings than for the typical industry peer.
The Fair Ratio model, which adjusts the P/E you might expect for Hinge Health based on its growth profile, profitability mix, size and risk, points to a lower level than where the shares trade today. The current 77.4x P/E also sits above the peer group average of 46.2x, which reinforces the picture of investors assigning a premium multiple to this business. For anyone weighing an entry point, the key question is whether Hinge Health's future earnings path is strong enough to support that premium or whether the current pricing already builds in a lot of good news. Explore the numbers behind Hinge Health's P/E valuation.
The Hinge Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle leaves off for Hinge Health, by spelling out in plain terms which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than it is today. Rather than a single ratio or model output, Narratives explain the future scenarios that those numbers rely on so you can watch how closely the real business tracks that script on the Community page.
Community views on Hinge Health split between those who see a high quality business still mispriced and those who think expectations already look full.
Bull case: 29% undervalued
"Most striking is the free cash flow margin, which surged to 47% in Q2 2026, far exceeding typical SaaS benchmarks of 15 to 20%..."
Discover why this Narrative puts Hinge Health at 29% undervalued.
Bear case: 14% overvalued
"Even with high client retention at 97% and head to head win rates at all time highs, large employers and health plans continually reassess vendors..."
Explore why this Narrative puts Hinge Health at 14% overvalued.
An unresolved piece of the Hinge Health puzzle
The valuation work only goes so far without asking where professional analysts think Hinge Health could be a few years from now, and how that picture lines up with today’s pricing. Explore where analysts expect Hinge Health to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com