
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Is Integra LifeSciences Holdings (IART) $450 Million Debt Deal Changing?
- Integra LifeSciences Holdings (NasdaqGS:IART) completed a US$450 million senior secured note offering due 2033 as part of its capital structure overhaul.
- The new senior secured notes are expected to refinance existing credit facilities within a broader refinancing transaction across Integra LifeSciences' debt stack.
- Completion of the US$450 million senior secured note issue reshapes Integra LifeSciences' funding profile and overall balance sheet structure. Take a look at 1 major warning sign we have identified for Integra LifeSciences Holdings.
Refinancing moves like Integra LifeSciences' recent US$450 million note issue often sit within a wider trend that income-focused investors may want to explore through 8 dividend fortresses.
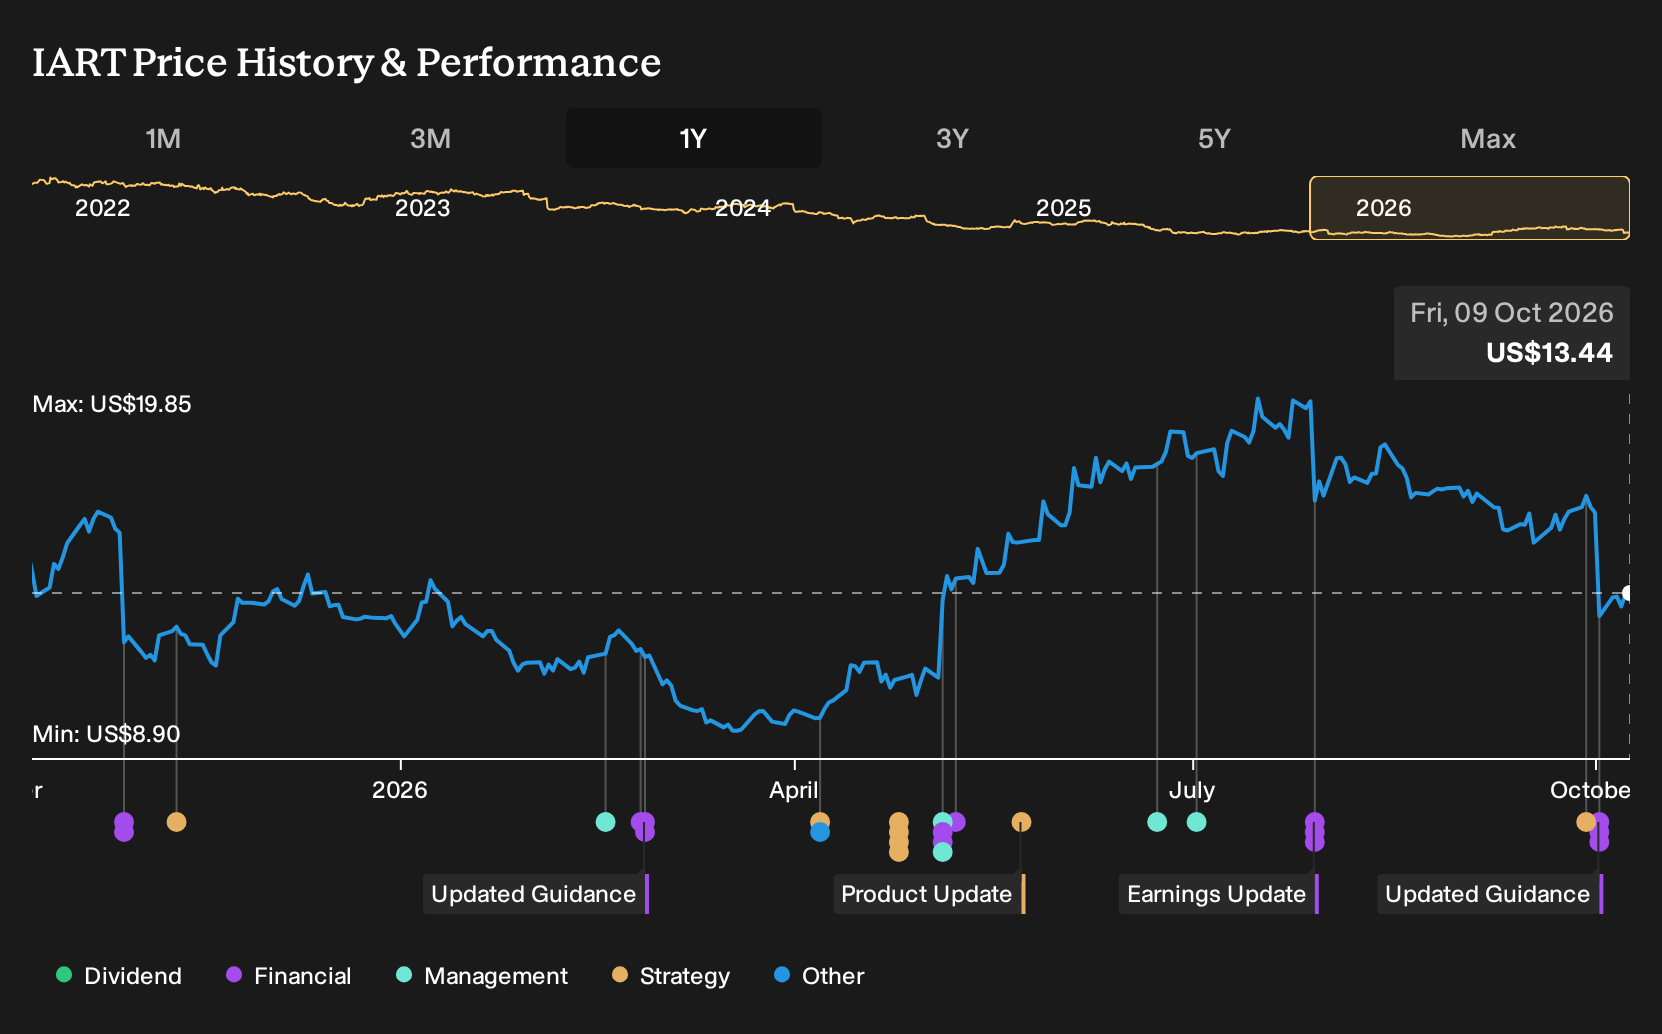
Integra LifeSciences Holdings is a US medical equipment group with a US$1.0b market cap that supplies surgical instruments and neurosurgical, ENT, and wound care products used in operating rooms and critical care units. As a result, changes to its capital structure sit behind a large installed base of hospital customers.
See how Integra LifeSciences Holdings's balance sheet measures up.
Integra LifeSciences’ refinancing shifts the risk focus to interest burden and flexibility
For Integra LifeSciences, the 9.5% senior secured notes and linked refinancing plan go straight to the heart of the Narrative’s key constraint, high leverage and interest cover. A larger slice of funding now comes from long dated, fixed rate debt that is secured and guaranteed by core subsidiaries. That structure may simplify the debt stack and extend maturities; yet it also locks in a clear cash cost for capital at 9.5%. For investors weighing the debt reduction catalyst, the question is whether future operating and free cash flow can comfortably fund this coupon while management works toward lowering the roughly US$1.6b net debt load.
See how these catalysts shape Integra LifeSciences Holdings' path to a $18.38 fair value.
The cleanest early read on whether this refinancing is helping will come from upcoming quarterly reports, in particular the interest coverage ratio and total leverage figure against the current 4.1x level as the new notes and any Term Loan B funding flow through the balance sheet.
The question coverage often skips on Integra LifeSciences Holdings, who is actually in charge here and what are they rewarded for doing?
Investors have seen Integra LifeSciences’ products and debt terms, but the quieter story is who sits in the key seats and how their pay packages line up with your interests. See who is actually steering Integra LifeSciences Holdings, and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com