
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Alliance Expansion Require Action From Regeneron (REGN) Investors?
- Regeneron Pharmaceuticals expanded its long running alliance with Sanofi, securing a US$1b upfront payment and sharing rights to four new long acting immunology antibodies, while also releasing fresh clinical data across oncology and obesity programs.
- The combination of new collaboration economics and early ubamatamab and trevogrumab data points to Regeneron Pharmaceuticals leaning further into diversified, non EYLEA revenue sources and higher margin partnership income.
- The focus now shifts to how Regeneron Pharmaceuticals' expanded Sanofi alliance could reshape the investment narrative around its long term earnings mix.
Scan how Regeneron Pharmaceuticals' push beyond EYLEA compares with other immunology and oncology players by reviewing the hand-picked 34 healthcare AI stocks now gaining attention.
Regeneron Pharmaceuticals Investment Narrative Recap
To own Regeneron Pharmaceuticals, you need to believe the business can steadily replace and then surpass its EYLEA franchise with a mix of Dupixent profit share, oncology assets like Libtayo and ubamatamab, and newer obesity and cardiometabolic efforts. In the short term, the focus is on execution in these newer areas while EYLEA faces ongoing competition and pricing pressure.
Recent data across oncology and obesity, along with the expanded Sanofi alliance, speak directly to that diversification effort. The biggest near term risk remains that retinal revenue and legal issues around Libtayo and fianlimab weigh more heavily than expected, and that newer programs take longer or prove less impactful than hoped.
The ubamatamab update in low grade serous ovarian cancer appears particularly relevant at this stage. Investors are watching whether Regeneron Pharmaceuticals can turn early oncology signals into registrational studies, regulatory filings, and eventually commercial products that are meaningful alongside Dupixent and EYLEA.
In this area, the company has already moved to enroll a potentially registrational LGSOC cohort and is planning a Phase 3 trial, so execution and safety management become the key watch points. The progress of these trials will feed directly into the medium term catalyst path and will influence how much weight investors place on oncology as a potential offset to competitive pressure in the eye franchise.
What The Current Regeneron Pharmaceuticals Forecasts Assume
Analysts are effectively sketching out a version of Regeneron Pharmaceuticals where a broader mix of immunology, oncology, and obesity drugs supports a bigger profit pool by the end of the decade. Their models build in 9.7% yearly revenue growth for the next three years, a lift in profit margins from 27.9% today to 31.9% in three years, and earnings rising from US$4.3b now to US$6.5b by 2029. That jump in profit would need to come while the P/E multiple steps down from 17.3x today to 14.9x, with the share count shrinking about 2.67% a year as buybacks reduce outstanding stock.
Consensus targets go a step further and spell out what would need to line up for the stock to reach the current analyst fair value. The central case assumes revenues of US$20.5b and earnings of US$6.5b in 2029, with the shares trading at 14.9x those profits and discounted back using a 7.5% to 7.55% rate. That framework leaves room for debate, given the spread between the most optimistic earnings forecast of US$8.5b and the most cautious view at US$5.7b, which shows how differently researchers are thinking about Dupixent durability, EYLEA HD, and newer programs like ubamatamab.
For readers trying to weigh these moving parts, the key is not just whether Regeneron Pharmaceuticals can reach US$20.5b of sales, but how it gets there and what mix of therapies drives the shift. A higher profit margin profile assumes more high contribution collaboration revenue from Sanofi, a richer blend of oncology income, and efficient scaling of obesity and cardiometabolic products. Any gap between those expectations and real world execution on trials, regulatory decisions, or competitive responses would feed straight through to earnings and could leave the business short of the consensus path described today.
Regeneron Pharmaceuticals' narrative projects US$20.5b revenue and US$6.5b earnings by 2029. This setup includes 9.7% yearly revenue growth and an earnings increase of about US$2.2b from the current US$4.3b base.
Uncover why Regeneron Pharmaceuticals' fair value indicates a 14% potential upside to its current price before that gap closes.
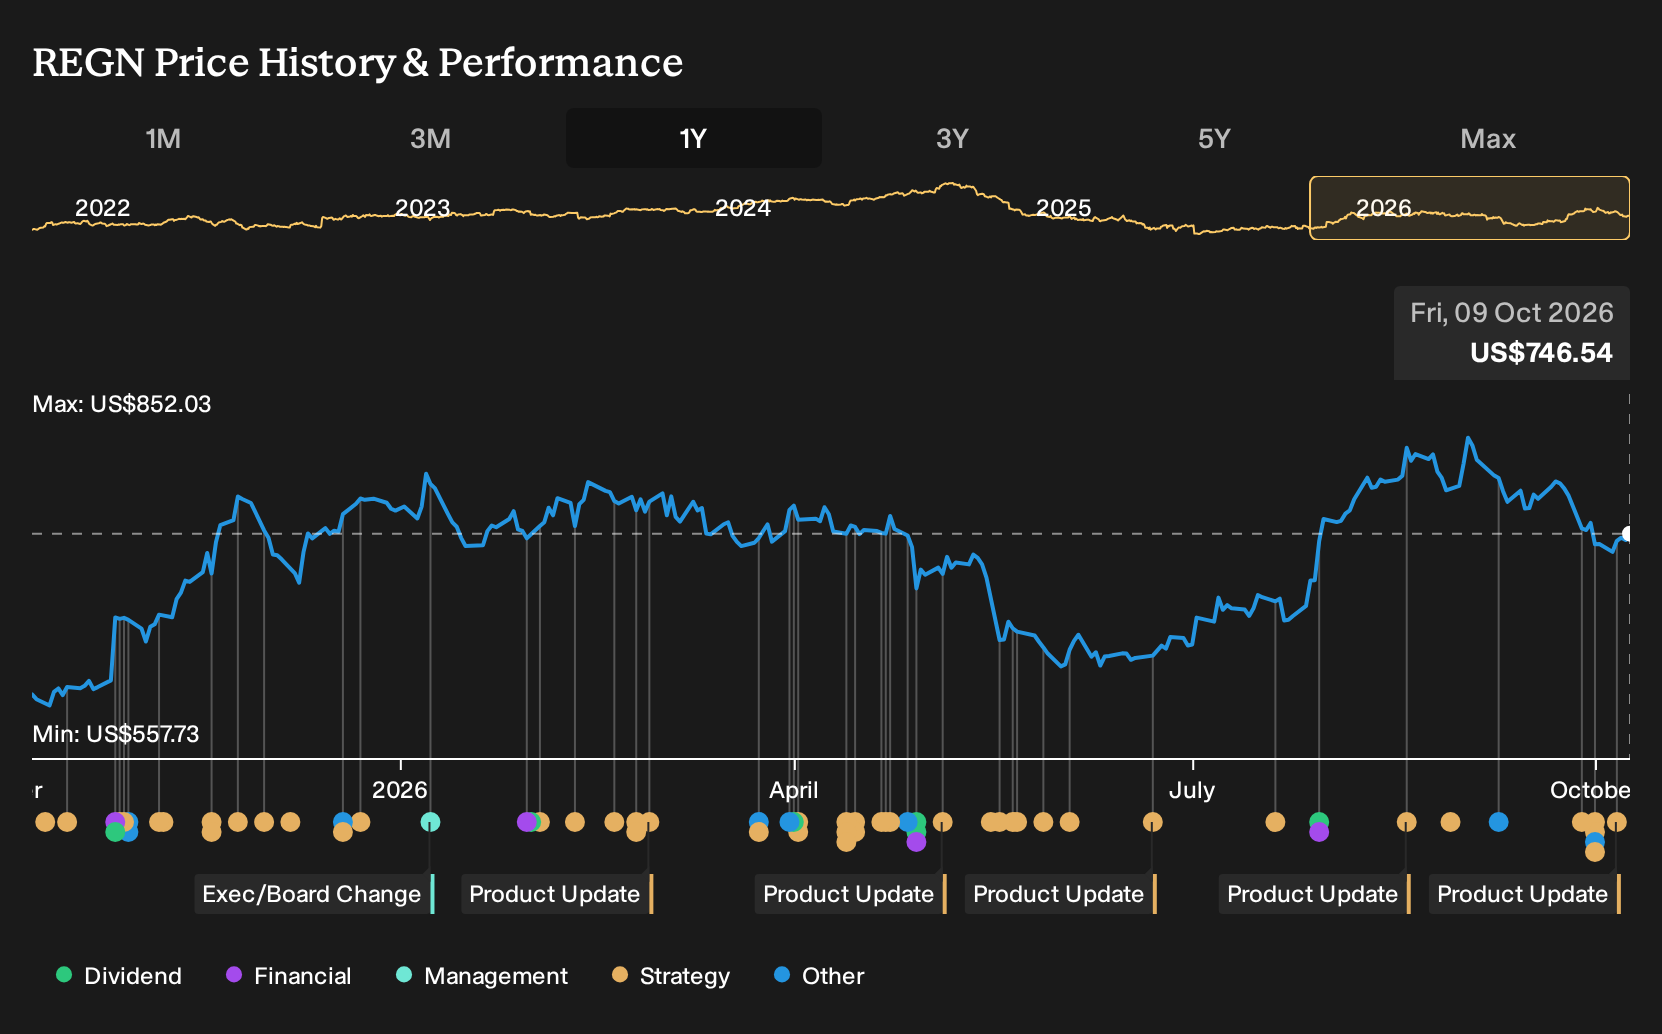
Exploring Other Perspectives
You now have two very different stories on Regeneron Pharmaceuticals. The most optimistic analysts were already sketching a C5 and siRNA catalyst path, with revenues reaching about US$22.9b and earnings of US$8.5b by 2029. Fresh ubamatamab and oncology data could either reinforce that view or prompt a reset, so explore several viewpoints before deciding where you sit.
Explore 5 other Regeneron Pharmaceuticals fair value estimates, including one that suggests as much as 228% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Regeneron Pharmaceuticals research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Regeneron Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Regeneron Pharmaceuticals' overall financial health at a glance.
Looking For More Ideas Beyond Regeneron Pharmaceuticals?
If you want to pressure test Regeneron Pharmaceuticals against a wider opportunity set, use the Simply Wall St Screener to scan other companies that match your risk profile, income needs, or preference for stronger balance sheets.
- For investors who care most about resilient business models and steadier risk profiles, review a curated 31 resilient stocks with low risk scores that may better fit a capital preservation mindset.
- If dependable income is a priority, consider dividend payers in the 8 dividend fortresses that might align with a long term cash flow focus.
- When the goal is to spot future leaders before the crowd, check out the 20 high quality undiscovered gems that pair solid fundamentals with lower current visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com