
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
WD 40 (WDFC) Stock Looks Above Fair Value Today
WD-40 Company has seen its stock grind higher over the past year, which puts fresh focus on a simple question for you as a shareholder: Does the current share price around its recent US$202.29 close still line up with what the business earns today?
- WD-40 has delivered a 7.3% gain over the past year, which puts recent buyers in profit and raises the question of how much of its earnings power is already reflected in the share price.
- The business relies on well known maintenance brands with established margins and cash generation, which can support an earnings profile that investors often weigh carefully against the price they are paying.
- There is a second opinion on WD-40 worth weighing. See what analysts think WD-40's shares could be worth.
The issue now is whether WD-40's current valuation is justified by its earnings when set against the Fair Ratio benchmark.
If you are weighing whether WD-40's US$202.29 share price reflects its earnings, it can also help to compare it with a wider set of 29 high quality undervalued stocks
Has WD-40 Run Too Far on Earnings?
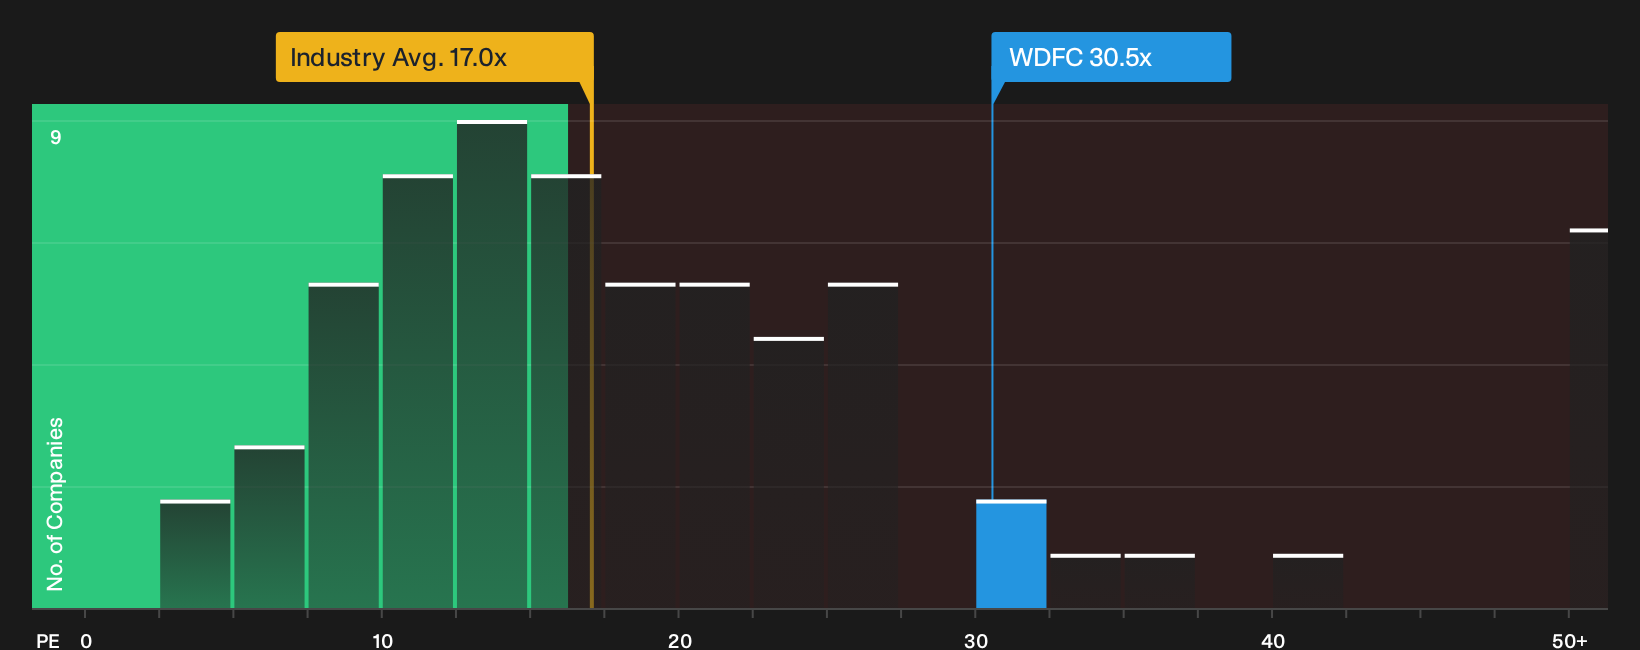
The P/E ratio works well for WD-40 because earnings are a key lens for a mature consumer brand business built around cash generation. On this measure, the stock trades on roughly 30.5x earnings, which is well above the Household Products sector average near 17.0x and above peers around 17.3x.
A tailored Fair Ratio that blends WD-40's growth profile, profitability, size and risk points to a lower multiple than the current 30.5x. This puts the shares in clearly overvalued territory on this framework. That kind of premium usually asks you to assume strong persistence in the company’s earnings quality or to accept a rich price for the comfort of a familiar franchise. Explore the numbers behind WD-40's P/E valuation.
The WD-40 Narrative: What Would Justify Today's Price?
Narratives pick up where the WD-40 valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price, and they sit on Simply Wall St’s Community page. Each narrative lays out the specific assumptions behind its view of fair value so you can compare those expectations with WD-40's actual results as they arrive.
One of the top community narratives on WD-40: 26% undervalued
"The main thing that has to go right is for WD-40 to execute on premiumization of its Multi-Use Product and growth of Specialist lines..."
Discover why this Narrative puts WD-40 at 26% undervalued.
For WD-40, the share price is only one decision point
Before you treat WD-40 as just a set of valuation ratios, it is worth asking who is steering the business, how their pay is structured and whether those incentives truly line up with your interests. See who runs WD-40 and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com