
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Investors Are Trying To Figure Out About Halozyme Therapeutics (HALO)
Halozyme Therapeutics (HALO) just expanded its global collaboration and license deal with argenx, adding two more exclusive ENHANZE targets. The enlarged agreement brings additional potential milestone payments and future royalties into focus for investors.
The fresh argenx expansion comes alongside a strong run in Halozyme Therapeutics, with a 90 day share price return of 45.08% and a year to date share price return of 57.05%. The 1 year total shareholder return of 72.26% and 3 year total shareholder return of 202.11% point to momentum that has been building over several years, as recent partnership news and the appointment of Jim Daly to the board sharpen focus on both the ENHANZE platform and commercial execution.
Scan other fast-moving healthcare partnerships built around licensing platforms and recurring royalties with the curated 34 healthcare AI stocks that echo the Halozyme Therapeutics and argenx ENHANZE story.
After a surge like Halozyme Therapeutics has just logged, the fork in the road is clear. Is the recent ENHANZE momentum already in the price, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 27% Undervalued
Halozyme Therapeutics last closed at $110.42 while the most followed narrative, according to Teg, assigns a fair value of $151.83. That gap puts the recent ENHANZE momentum and platform buildout in a different light for anyone trying to judge what is already priced in.
Using a simplified framework, investors can estimate Halozyme''s future earnings power by scaling current results.
Current guidance implies:
• Approximately $1.23 billion royalty revenue
• Approximately $8.83 EPS
If combined ENHANZE® and Hypercon™ royalties ultimately reach $2.5 billion annually:
$2.50B ÷ $1.23B = 2.03x
Royalty revenue would be roughly double today''s level.
Applying the same relationship to earnings:
$8.83 × 2.03 ≈ $17.90 EPS
That suggests annual earnings power approaching $18 per share before considering additional buybacks or operating leverage.
See why 3 investors see Halozyme Therapeutics as 27% undervalued.
Result: Fair Value of $151.83 (UNDERVALUED)
Still, the Halozyme Therapeutics royalty story can be knocked off course if ENHANZE partner launches disappoint expectations or if Hypercon and Aerocon progress materially slower than markets currently assume.
Find out about the key risks to this Halozyme Therapeutics narrative.
Another View: Halozyme Therapeutics Through The P/E Lens
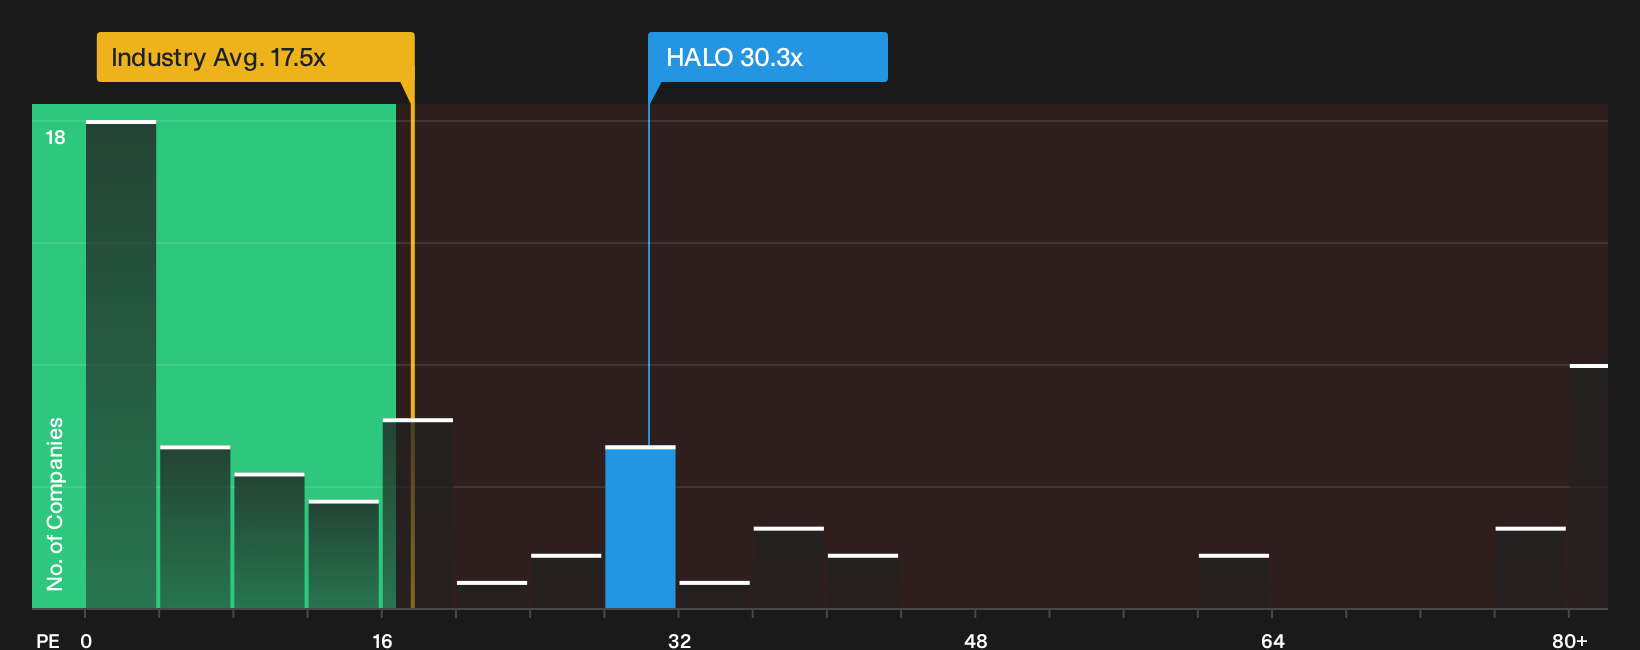
There is a catch to the Halozyme Therapeutics undervaluation story. On earnings multiples, the stock trades on a P/E of 30.3x, which is above the US Biotechs sector on 17.5x and above an estimated fair ratio of 21.9x. That gap points to valuation risk if sentiment cools.
To see how this earnings-based view lines up with the broader valuation picture, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
For a clearer picture of how Halozyme''s valuation compares across peers and the sector, review the
Next Steps
If this Halozyme Therapeutics narrative feels split between optimism and caution, do not sit on the fence. Instead, review the core numbers, partner exposure, and sentiment under your own microscope by weighing up the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Halozyme Therapeutics?
Halozyme Therapeutics may already be on your radar, but the next strong addition to your watchlist could be hiding in plain sight if you widen the search.
- Target potential bargains by scanning for companies with robust fundamentals and attractive pricing through the 29 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with healthier finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for future market favourites before the crowd notices by checking the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com