
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 U.S. Infrastructure Stocks Tied To SPR Refill And Energy Storage Demand
The U.S. Strategic Petroleum Reserve, sitting near multi decade lows, has turned what used to feel like a sleepy government stockpile into a live market risk. Supply shocks now carry more bite, and pricing power can shift quickly when barrels are scarce and storage is constrained. This piece walks through how that backdrop hits the SPR value chain and profiles 3 U.S. stocks whose businesses are directly exposed to those pressures.
The three stocks covered next are a sample set. The full screen surfaced 10 more U.S. energy infrastructure and engineering contractors tied by business description to SPR style storage and fuel terminal work that are not detailed here.
To identify and analyze your own highest conviction angles in this theme, head straight into the U.S. Strategic Energy Infrastructure & Engineering Contractors screener.
Beam Global (BEEM)
Beam Global fits this screener as a clean-tech player focused on distributed, off grid energy and storage that can complement government efforts to build more resilient back up capacity when traditional fuel reserves look less secure.
Beam Global designs and manufactures renewably energized infrastructure and battery solutions, with all reported revenue of about US$26.5 million coming from solar products and proprietary technology solutions, and the stock carries a market value of roughly US$24 million.
"Beam's privileged government-backed partnerships in the Middle East and strategic manufacturing footprint give it fast-track access to over $1 trillion in near-term sustainable infrastructure spending, which may affect its gross and net margins as high-value projects ramp."
What that ultimately means for Beam Global’s profitability depends on how one underappreciated pressure on its future contract mix and pricing unfolds.
If that contract tilt is what you care about, read the full narrative for Beam Global to see how that pressure could reshape the next phase for Beam Global.

Matrix Service (MTRX)
Matrix Service sits much closer to the traditional heart of the SPR theme than Beam Global, because its core business is designing, building and maintaining the large storage tanks and terminals that keep crude, LNG and other fuels available when physical reserves run thin.
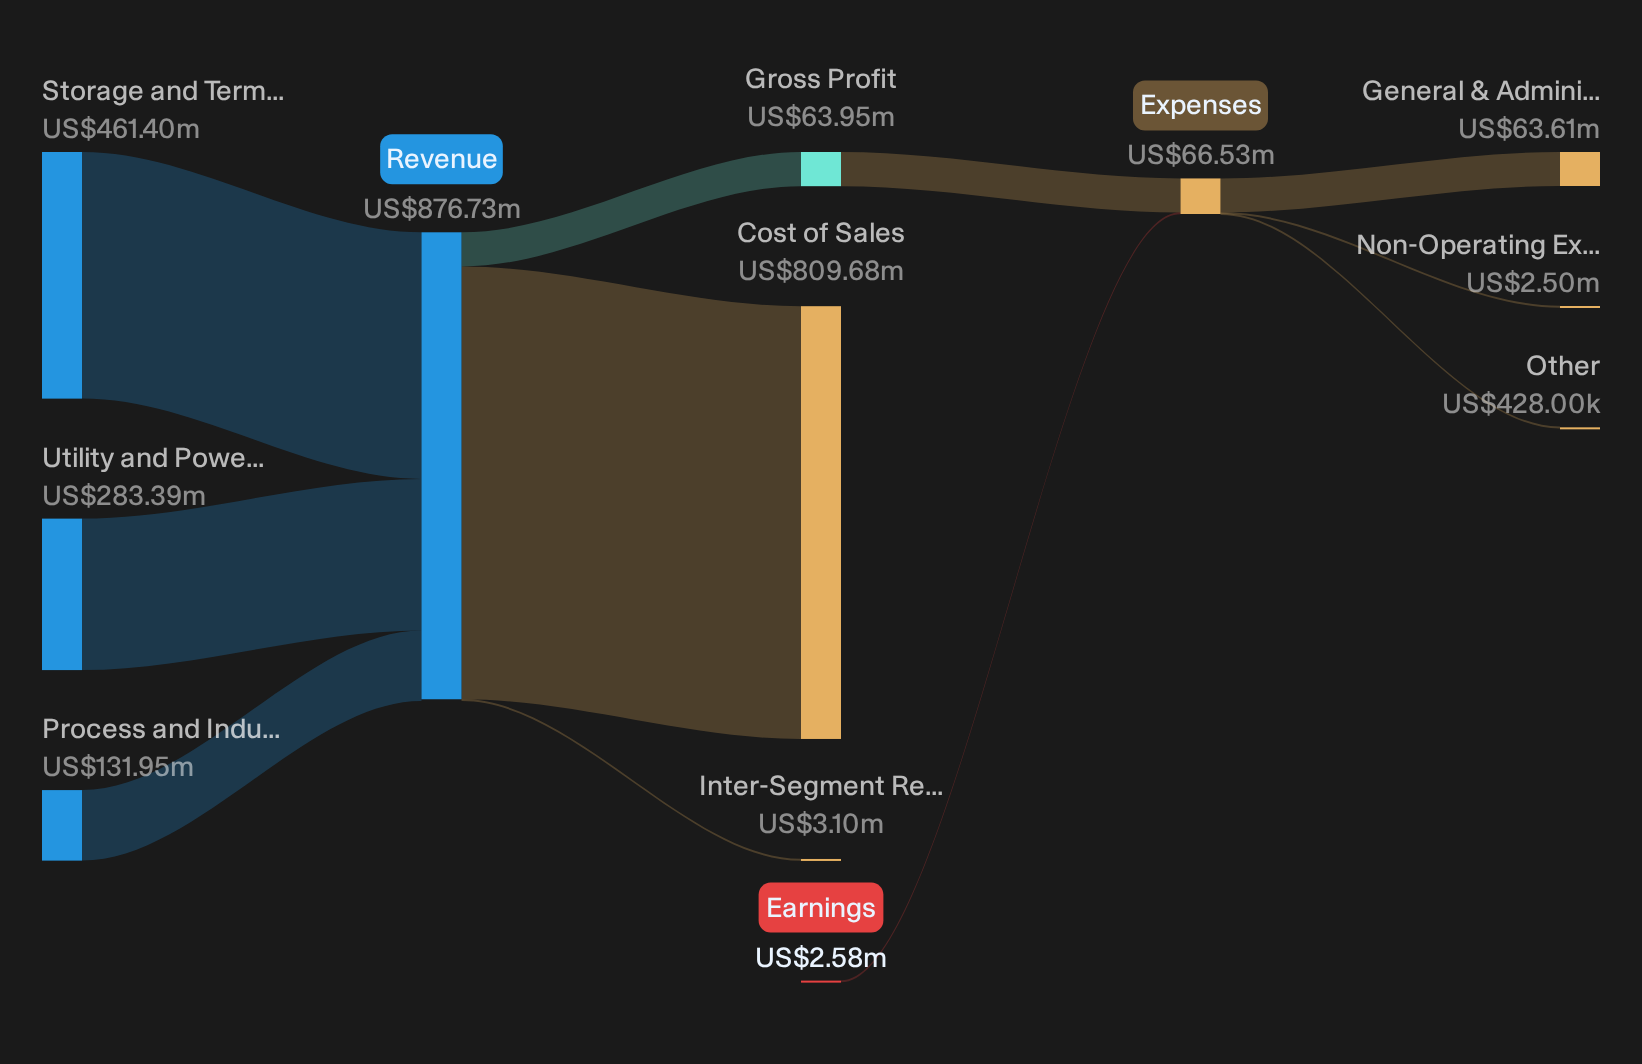
Matrix Service Company focuses on large scale storage and terminal solutions, which generated about US$461 million of the US$874 million segment revenues, with utility and power infrastructure adding roughly US$283 million and process and industrial facilities about US$132 million, and the stock carries a market value near US$298 million.
"Exposure to large LNG and NGL projects, including peak shaving and specialty storage, is feeding into a US$1.1b backlog and guided full year revenue of US$875 million to US$925 million."
What really matters now is how one less visible constraint on future storage project timing shapes Matrix Service’s pricing power and eventual margins.
That hidden timing pressure is exactly what full narrative for Matrix Service unpacks, including how Matrix Service’s backlog could accelerate or stall as SPR linked projects shuffle in the queue.
Quanta Services (PWR)
Quanta Services plugs directly into the SPR theme because it actually builds and maintains the electric and underground infrastructure that keeps strategic energy systems running, from transmission lines to storage-related pipelines, and its scale gives it a front row seat to long duration grid and energy security projects.
Quanta Services generates about US$26.9b of revenue from Electric Infrastructure Solutions and roughly US$6.0b from Underground Utility and Infrastructure Solutions, with the stock valued around US$106.1b by market cap.
"The long case is simple: Quanta sits at the intersection of several unusually durable spending waves: aging grid replacement, transmission expansion, utility hardening, manufacturing reshoring, renewable interconnection, and AI-driven power demand."
The real swing factor is how one less visible constraint on future large project execution shapes Quanta’s ability to turn backlog into sustained margin strength.
That execution swing factor is exactly what the full narrative for Quanta Services unpacks, including how project bottlenecks, risk sharing and capital cycles might be reshaping Quanta Services’ long run earnings power.

Curious About What You Might Be Missing Next
Fresh ideas do not stay under the radar for long. Momentum builds, prices move, and the cleanest entries can be identified quickly. Review these breakout themes and consider whether they fit your approach.
- Target dependable cash generators by running through a curated list of solid balance sheet and fundamentals (25 results) before the market fully reflects their staying power.
- Identify potential income workhorses early by scanning the 8 dividend fortresses while yields are still elevated and price momentum has not yet accelerated.
- Evaluate opportunities related to electrification and grid upgrades by reviewing a focused 43 power grid technology and infrastructure stocks while the theme is still developing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com