
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Pebblebrook Hotel Trust (PEB) Sells Hotel Zags, Is The Stock Fully Priced?
Pebblebrook Hotel Trust (PEB) just closed the $10.0 million sale of The Hotel Zags, a 174 room Portland property, and intends to funnel the cash into general corporate uses, including potential share repurchases.
The share price of Pebblebrook Hotel Trust has climbed over recent months, with a 30 day share price return of 7.17% and a year to date share price return of 65.54%. The 1 year total shareholder return of 87.96% signals strong momentum as asset sales and capital recycling continue.
Scan more hotel and real estate plays that are recycling capital, such as Pebblebrook Hotel Trust, by reviewing our curated list of 29 high quality undervalued stocks.
Pebblebrook Hotel Trust now trades only slightly below the average analyst target, yet carries a wider modelled discount to intrinsic value. Is the market rightly cautious after years of mixed returns, or mispricing the recent portfolio cleanup and buyback firepower?
Most Popular Narrative: 4% Overvalued
Pebblebrook Hotel Trust last closed at $19.12, a touch above the narrative fair value estimate of about $18.42. This frames the recent asset recycling and buyback plans as a test of how much improvement is already reflected in the price.
The ongoing recovery and strengthening of urban hotel demand, particularly in major gateway cities like San Francisco (where occupancy climbed from ~64% to nearly 70% year over year and remains well below peak levels), signals robust upside for further RevPAR and revenue growth as global travel and urbanization trends persist and major events return to cities. Strategic reinvestment and repositioning of key assets such as the multimillion dollar redevelopment of Newport Harbor Island Resort and other properties are driving outsized gains in both room and high margin ancillary revenue streams (e.g., F&B and event spaces), pointing to above average NOI and margin expansion as newly upgraded assets achieve stabilization.
See why 1 investors see Pebblebrook Hotel Trust as 4% overvalued.
Result: Fair Value of $18.42 (OVERVALUED)
Still, Pebblebrook Hotel Trust leans heavily on urban gateway markets, and rising labor and wage pressures in those cities could squeeze profitability if costs outpace efficiency gains.
Find out about the key risks to this Pebblebrook Hotel Trust narrative.
Another View on Pebblebrook Hotel Trust’s Valuation
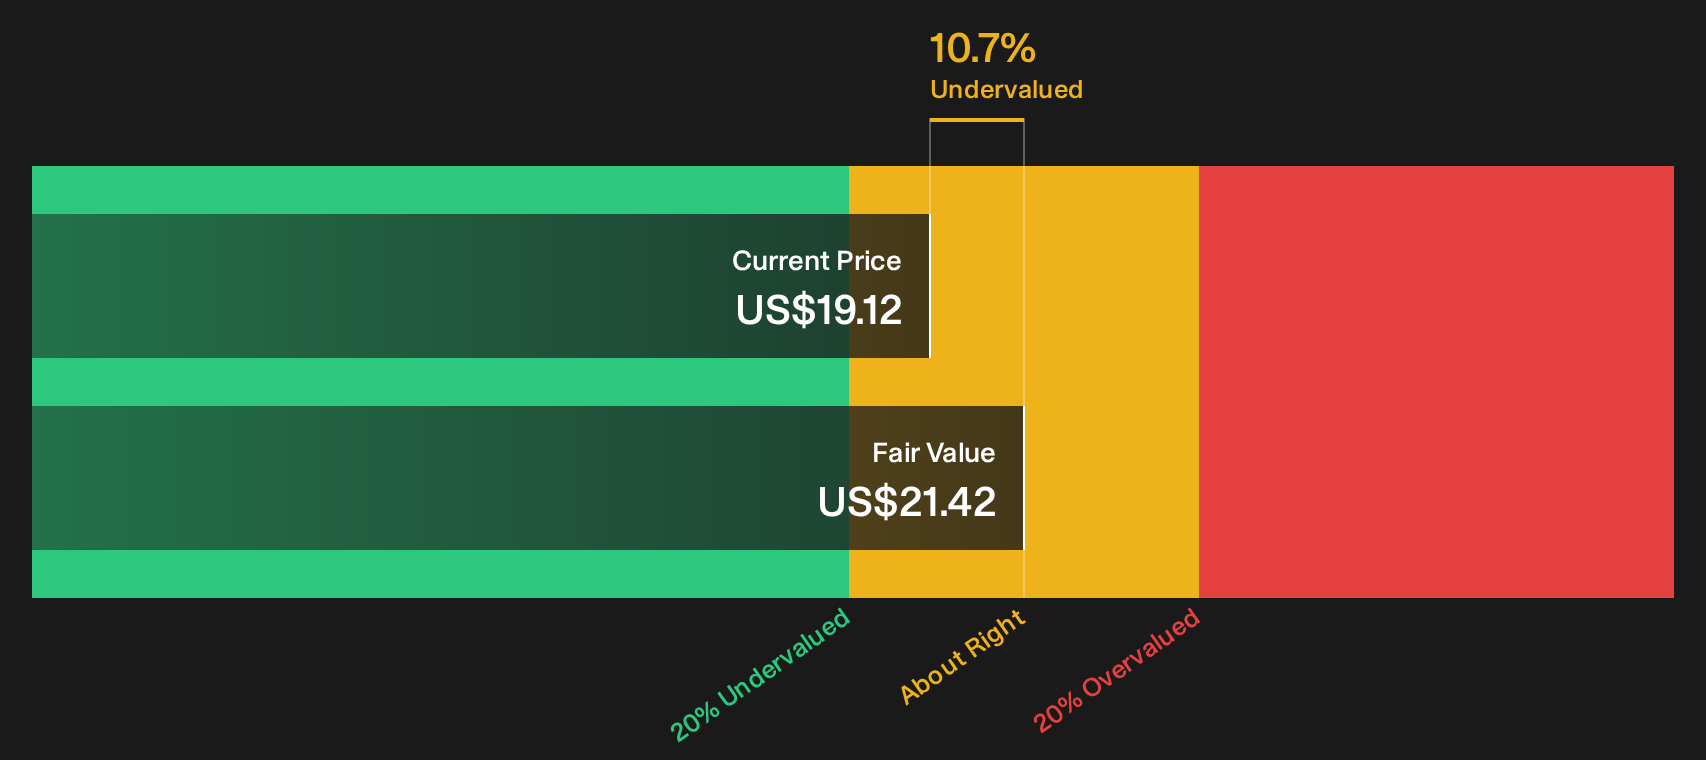
Some analysts view Pebblebrook Hotel Trust as about 4% overvalued at $19.12 compared with a stated fair value of $18.42, while the SWS DCF model indicates the opposite. That cash flow based approach suggests the shares are trading below an estimated value of $21.42. Which yardstick do you trust when the signals disagree?
For a closer look at how this cash flow based view is built and what assumptions sit underneath it, take a few minutes with the Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals across Pebblebrook Hotel Trust can either feel exciting or uncomfortable, so move quickly, review the underlying data, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Pebblebrook Hotel Trust?
Do not stop with Pebblebrook Hotel Trust. Broaden your watchlist now with other potential opportunities surfaced by the Simply Wall St Screener, or you risk missing the next idea.
- Target consistency by reviewing a curated 31 resilient stocks with low risk scores that screens for resilience when markets turn choppy.
- Hunt for quality on sale with a focused 29 high quality undervalued stocks that blends solid balance sheets with attractive valuations.
- Spot future leaders early by scanning a 20 high quality undiscovered gems that highlights underfollowed businesses with strong fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com