
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
IDACORP (IDA) Plans A Major Grid Buildout, Is It Still 14% Undervalued?
IDACORP (IDA) drew fresh attention after its recent share move, with the stock up 1% on the day and modestly higher over the past week, while remaining flat over the past month.
Set against a 90 day share price return that is down 10.3%, the recent uptick in IDACORP at US$135.42 looks more like a tentative rebound than a full shift in momentum. At the same time, the 1 year total shareholder return of 3.3% and 3 year total shareholder return of 53.0% show that longer term holders have seen much stronger gains than short term traders.
Compare IDACORP's recent move with a hand picked group of regulated utilities by scanning the 43 power grid technology and infrastructure stocks for ideas with similar grid and infrastructure exposure.
That uptick in IDACORP could either be a small sentiment bounce or a reaction to how the regulated utility is actually being priced today. Which story does the current valuation tell?
Most Popular Narrative: 14% Undervalued
Analysts following IDACORP see a gap between the last close at $135.42 and their narrative fair value of about $157.33, and they link that gap directly to specific load growth and capital plans rather than vague optimism.
Massive planned capital investments, with IDACORP expecting to spend between US$1.3b and US$1.5b on CapEx in 2026 and around US$7b from 2026 to 2030 on generation, storage and transmission projects such as B2H and SWIP North, are forecast to drive rate base from about US$5.3b in 2025 to around US$11b by 2030 and increase regulated earnings.
See why 4 investors see IDACORP as 14% undervalued.
Result: Fair Value of $157.33 (UNDERVALUED)
Still, the IDACORP story depends heavily on executing a US$7b grid buildout and on large industrial customers ramping as planned. As a result, delays or regulatory pushback could quickly test that undervaluation case.
Find out about the key risks to this IDACORP narrative.
Another View: Cash Flows Tell A Different Story
While the consensus narrative frames IDACORP as about 14% undervalued, the SWS DCF model points the other way. On that cash flow view, IDA at $135.42 sits above an estimated future cash flow value of $112.08, which implies the stock screens as overvalued rather than cheap.
The gap between an earnings based fair value and a lower DCF output highlights valuation risk. If future cash generation tracks closer to the model, investors would be paying up today for growth that may already be embedded in the price. The question is which lens you trust more for a regulated utility with heavy capital plans.
Look into how the SWS DCF model arrives at its fair value.
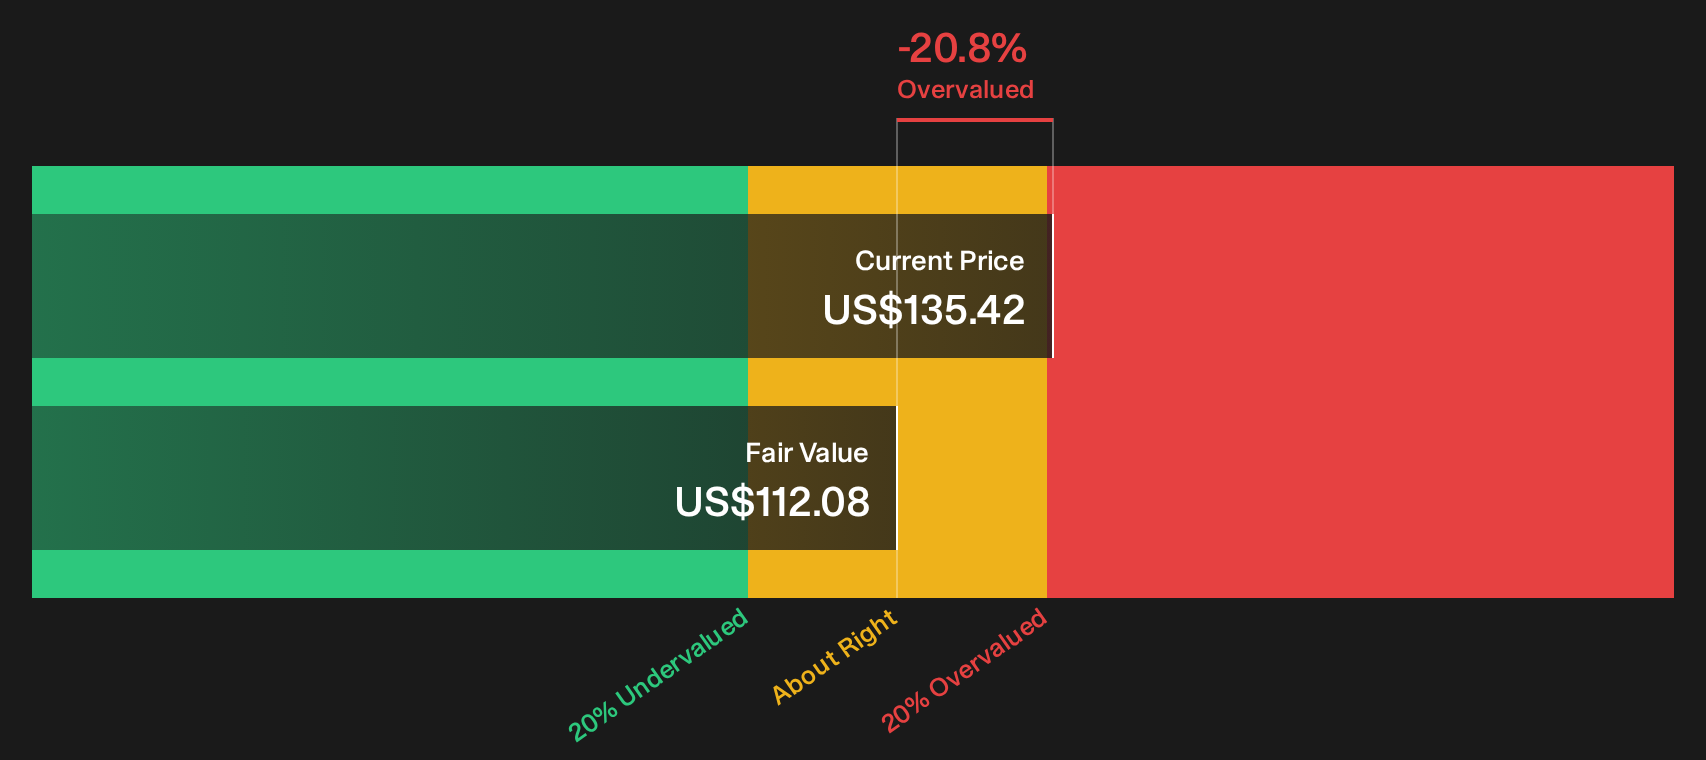
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out IDACORP for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on IDACORP's value story, and now the next move sits with you. Pressure test both the upside and downside by checking the 2 key rewards and 2 important warning signs.
Ready To Find Your Next Idea Beyond IDACORP?
If IDACORP has your attention today, do not stop there. Broaden your watchlist with fresh ideas that match how you like to build a portfolio.
- Target potential mispricings by scanning a curated list of companies that score well on quality and valuation through the 29 high quality undervalued stocks.
- Strengthen your income stream by reviewing higher yielding candidates that still aim for resilience using the 8 dividend fortresses.
- Prioritise resilience by focusing on businesses with robust balance sheets and fundamentals through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com