
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Global E Online (GLBE), Why Is The Latest Update Drawing Attention?
Global-E Online (GLBE) is reshaping its commercial leadership after promoting Tomer Gold to Chief Revenue Officer, effective October 1, 2026. Investors now have a fresh lens on how this management shift could influence the company’s revenue engine.
Global-E Online’s leadership reshuffle comes at a time when momentum in the shares has been improving, with a 30-day share price return of 8.63% and a 1-year total shareholder return of 19.21%, even though the 5-year total shareholder return is still down 29.24%.
Scan Global-E Online alongside a hand-picked 20 high quality undiscovered gems that also pair strong fundamentals with under-the-radar growth stories in e-commerce and digital infrastructure.
Bulls see Global-E Online pairing double digit revenue and net income growth with leadership continuity in its commercial engine. Bears point to the still weak 5 year return. Which side does the valuation lean toward next?
Most Popular Narrative: 20% Undervalued
Global-E Online’s most followed narrative pegs fair value at $50.62, versus a last close of $40.39. That gap frames the current debate around whether recent execution and guidance fully show up in the share price yet.
The rapid expansion and onboarding of new merchants across multiple geographies, including successful launches with major brands in the U.S., Europe, and Asia, as well as strong enterprise client retention, indicate continued, durable revenue growth driven by globalization of DTC e-commerce and rising demand for seamless international shopping experiences.
See why 22 investors see Global-E Online as 20% undervalued.
Result: Fair Value of $50.62 (UNDERVALUED)
Still, the Global-E Online story can change quickly if regulatory shifts raise cross border compliance costs or if competition pressures service fees and growth assumptions.
Find out about the key risks to this Global-E Online narrative.
Another Take On Global-E Online’s Valuation
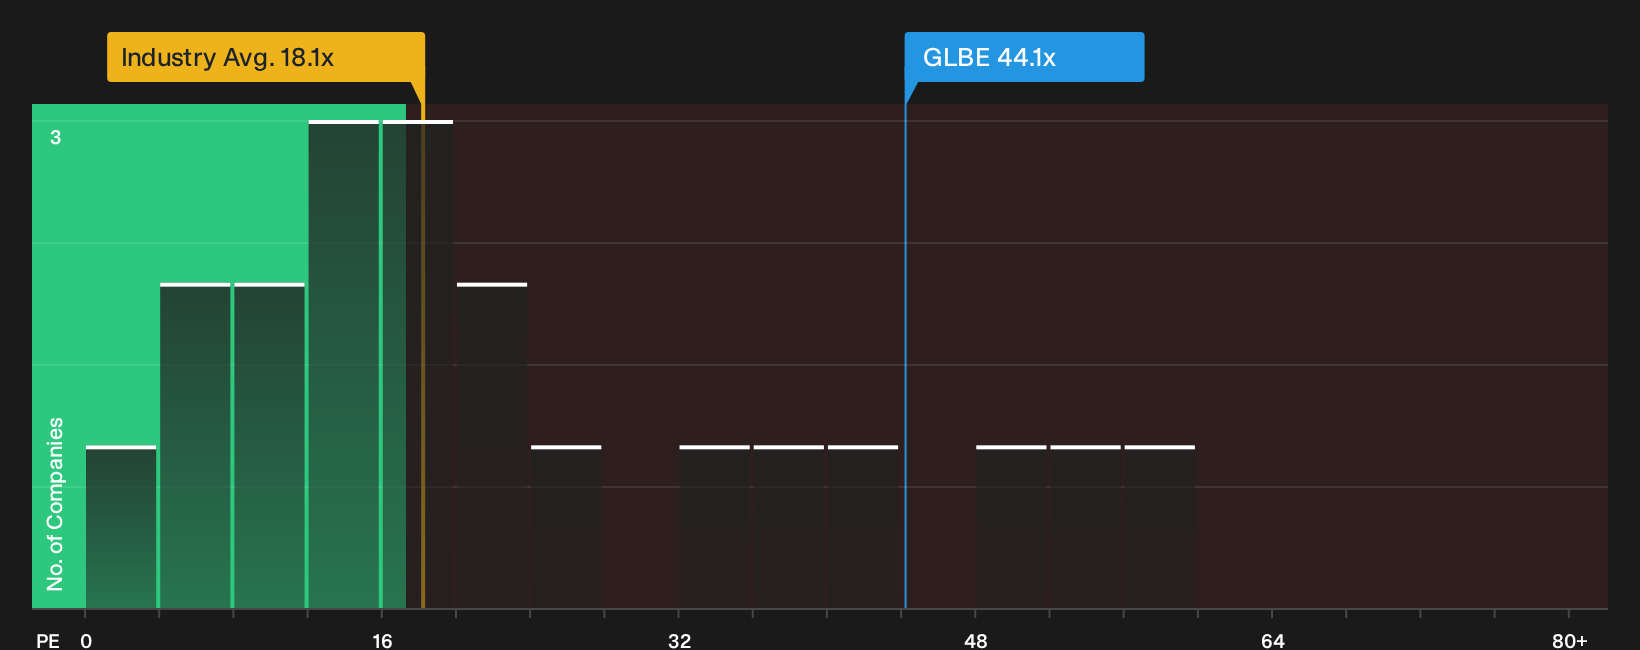
One perspective suggests Global-E Online looks attractive relative to fair value. Another presents a more demanding picture. At around 44.1x P/E, the stock trades well above peers on 12.5x and above an estimated fair ratio of 24.6x, which indicates meaningful downside risk if sentiment cools.
For investors weighing that premium against the growth narrative, the key question is whether Global-E’s execution justifies paying almost double the fair ratio that investors might eventually gravitate toward.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Global-E Online story so far. For a clearer view, act quickly and consider both sides using the 4 key rewards and 1 important warning sign.
Looking for more Global-E Online investment ideas?
If Global-E Online has your attention, do not stop here. Broaden your watchlist now so you are not chasing the next opportunity after it has moved.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (25 results) that can help anchor your portfolio when sentiment swings.
- Hunt for mispriced quality with a 29 high quality undervalued stocks that surfaces stocks where fundamentals and price still look out of sync.
- Build a calmer portfolio by reviewing a 31 resilient stocks with low risk scores that filters for businesses with sturdier risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com