
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Shake Shack (SHAK) Could Be 18% Undervalued After Brazil Expansion Plan
Brazil move puts Shake Shack’s Latin America push in focus
Shake Shack (SHAK) is extending its Latin America footprint, planning to enter Brazil through a new licensing partnership with Bold Hospitality Company after seven years of expansion in Mexico and with an upcoming launch in Panama.
Recent trading around Shake Shack reflects that tension between fresh expansion news and a tougher year for the shares. The stock has climbed 9.71% on a 7-day share price return and 7.59% over 90 days, yet the year-to-date share price return is down 19.85% and the 1-year total shareholder return has declined 22.89%, even though the 3-year total shareholder return is up 25%.
Scan how Shake Shack’s Latin America push compares with other consumer companies by running through the hand picked 20 high quality undiscovered gems.
Bulls view the Brazil launch as proof that Shake Shack can continue scaling internationally, while bears note that the share price remains sharply lower over the past 12 months. Which side does the current valuation support?
Most Popular Narrative: 18% Undervalued
On the latest numbers, the most followed narrative puts Shake Shack’s fair value at $81.38 versus a last close of $66.90, which points to a meaningful valuation gap if those long term assumptions hold.
The focus on urban expansion and faster roll out of both domestic company operated Shacks and international licensed locations, including new formats such as drive thrus and smaller footprints, is being backed by reduced build costs to under US$2 million per unit and over 30% cash on cash returns on recent openings, which can support system wide revenue growth and improving earnings.
See why 15 investors see Shake Shack as 18% undervalued.
Result: Fair Value of $81.38 (UNDERVALUED)
Still, that story can crack if record beef and operating costs keep pressuring restaurant level margins, or if heavier value competition and softer demand weigh on future sales.
Find out about the key risks to this Shake Shack narrative.
Another View: What Shake Shack’s P/E Is Telling You
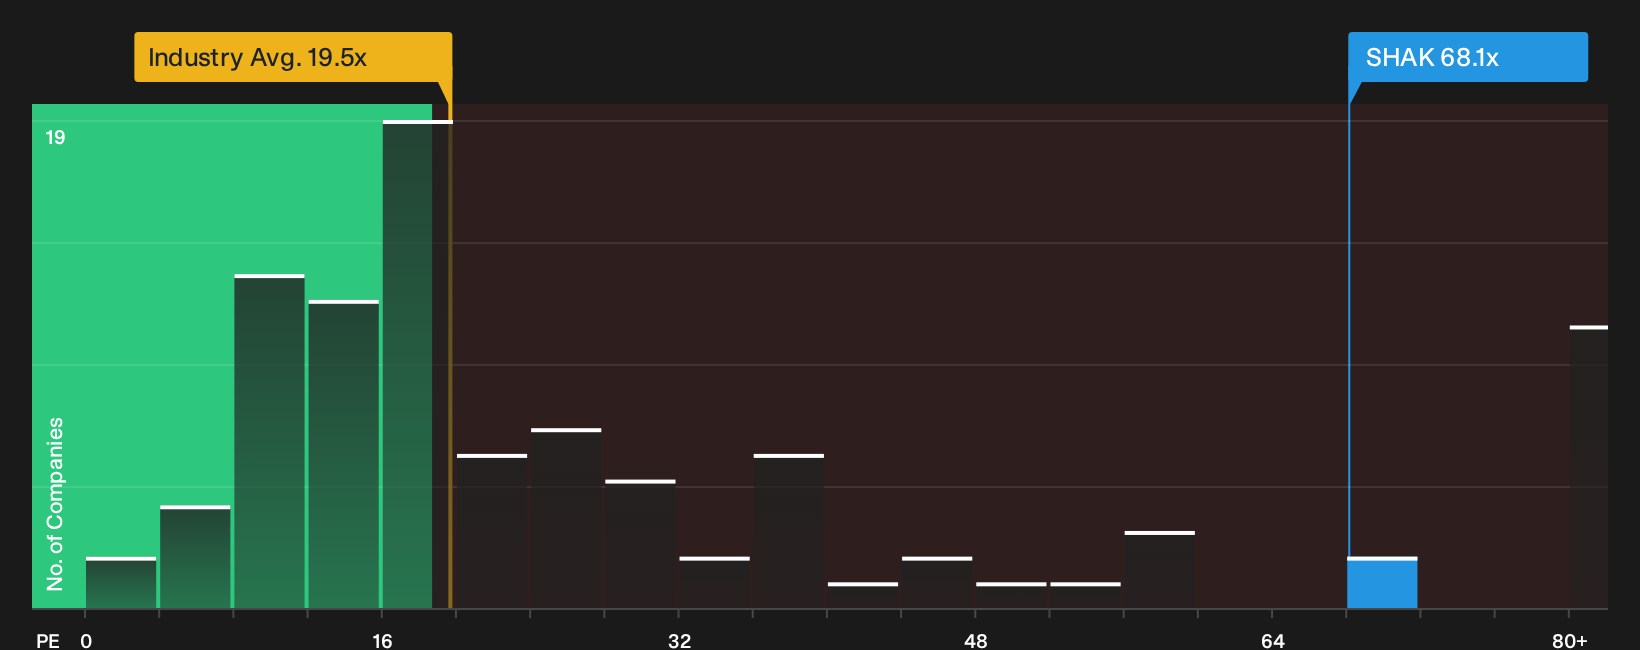
The fair value narrative points to upside for Shake Shack, yet the simple earnings multiple sends a different message. The stock trades on a P/E of 68.1x, while the US Hospitality industry averages 19.5x and close peers sit near 19.2x.
The fair ratio for Shake Shack is estimated at 22.4x. That is a big gap, which implies investors are already paying a steep premium and leaves less room for error if future earnings or margins fall short of expectations. Is that premium something you are comfortable underwriting at today’s price?
To see how these earnings multiples compare with the underlying numbers over time, take a look at the valuation breakdown next, where See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Shake Shack leave you on the fence, that is the right instinct. Move quickly to review the upside drivers in detail with the 3 key rewards.
Looking for more investment ideas beyond Shake Shack?
Do not stop with one restaurant stock. Broaden your watchlist with other angles on quality, price and resilience using the Simply Wall St screener.
- Target potential mispricings by scanning a curated set of 29 high quality undervalued stocks that pair stronger fundamentals with more modest expectations.
- Build an income focused shortlist by zeroing in on 8 dividend fortresses that may help support more predictable cash payouts.
- Prioritise resilience first by running through 31 resilient stocks with low risk scores that score well on balance sheet strength and business risk.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com