
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Record Revenue Outlook Could Be A Game Changer For CRA International (CRAI)
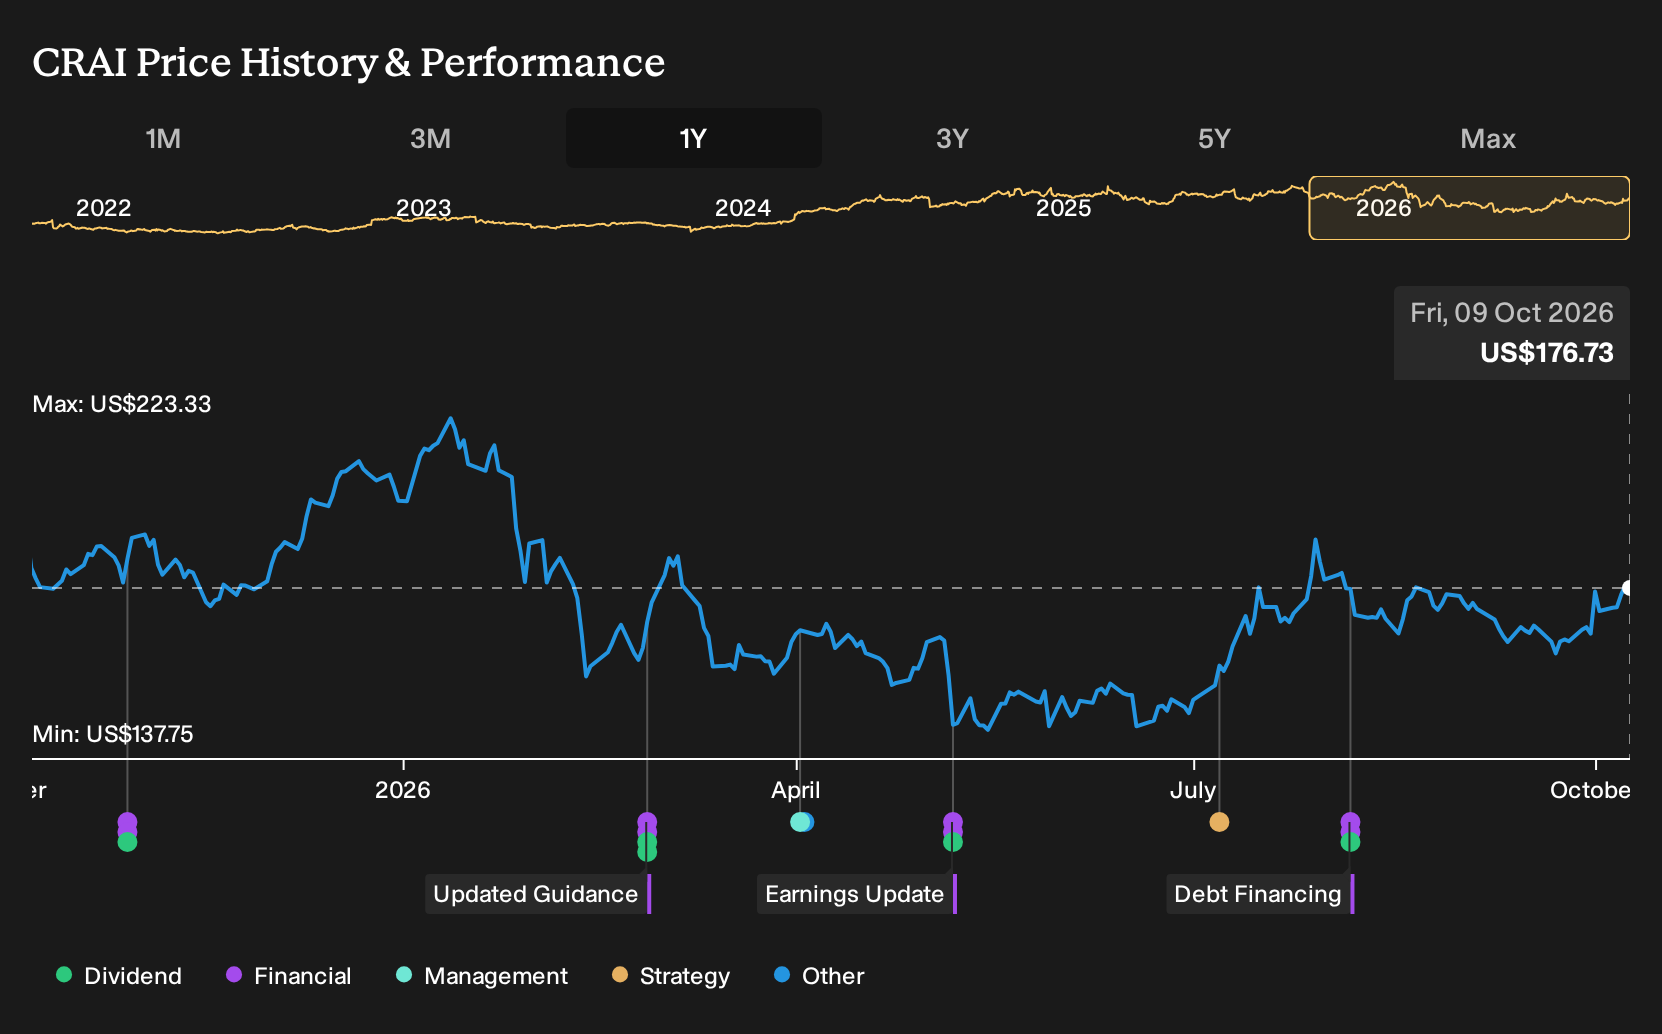
- CRA International reported record Q2 2026 revenue of US$210.8 million, reflecting 12.8% year over year growth and supported by strong contributions across key consulting practices and regions, while reaffirming its non GAAP EBITDA margin outlook.
- The firm raised full year 2026 revenue guidance to a range of US$805 million to US$820 million. This points to management confidence in demand across Antitrust & Competition Economics, Forensic Services, and Risk, Investigations and Analytics that is linked to active M&A and crisis related work.
- We will now look at how CRA International's raised 2026 revenue guidance could influence the existing investment narrative around growth and margins.
Compare CRA International's momentum in complex disputes and M&A work with a curated set of consulting and analytics peers screened as 20 high quality undiscovered gems.
CRA International Investment Narrative Recap
To own CRA International, you need to be comfortable with a consulting model that leans heavily on complex disputes, antitrust, and M&A related work. The raised 2026 revenue outlook signals that current case flow in those areas is holding up. The key near term swing factor remains how consistently those high value matters keep coming through the door.
The biggest risk still sits on the cost and funding side. Heavy spending on senior talent and higher use of the credit facility leave less room if case activity slows or pricing softens. The latest quarter does not remove that concern, but it suggests the business is currently absorbing it.
The most relevant update here is management lifting full year 2026 revenue guidance to US$805 million to US$820 million while keeping non GAAP EBITDA margin guidance intact. That combination ties directly into the core catalyst for CRA International, which is converting demand in antitrust, forensic work, and risk analytics into steady top line expansion without margin slippage.
For you as a shareholder or potential investor, the raised range highlights both opportunity and pressure. Execution needs to stay tight on staffing, utilization, and pricing to support the higher revenue bar, given elevated compensation, debt, and capital returns. Any sign that margins start to compress against the reiterated outlook would quickly refocus attention on those existing risks.
CRA International's narrative projects US$902.9 million in revenue and US$72.1 million in earnings by 2029. This assumes 4.3% yearly revenue growth and an earnings increase of about US$22.9 million from US$49.2 million today.
Uncover why CRA International's fair value indicates a 42% potential upside to its current price. This gap could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band, from US$250.5 to US$790.19 per share, which shows how far opinions on CRA International can stretch. Before the latest guidance upgrade feeds into those models, you should weigh that spread against the live risks around M&A intensity, leverage, and senior hiring costs.
Explore another CRA International fair value estimate, including one that suggests it could be worth just $250.50!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CRA International research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CRA International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CRA International's overall financial health at a glance.
Looking For More Investment Ideas Beyond CRA International?
If CRA International's story has sharpened your thinking, use that same lens on a wider set of opportunities by running a few focused screens on Simply Wall St. The right filters can help you quickly narrow a broad market into a shortlist that actually fits your risk appetite and income goals.
- If capital preservation is near the top of your list, start with resilient companies that have steadier risk profiles and review a 31 resilient stocks with low risk scores that can help you filter out the more fragile balance sheets.
- Income focused investors who care about reliable cash returns can scan for sturdier payers by checking a curated group of 8 dividend fortresses that meet a 5%+ yield hurdle.
- For readers hunting for mispriced quality, broaden your watchlist with a 29 high quality undervalued stocks that blends solid cash flows with healthier financial positions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com