
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ASX Growth Stocks Insiders Are Betting On
As the Australian share market prepares for a potentially positive start to the week, buoyed by recent gains on Wall Street, investors remain cautious about rising bond yields and their potential impact. In this environment of mixed signals and geopolitical considerations, growth companies with high insider ownership can offer unique insights into potential opportunities, as insiders often have a deep understanding of their company's prospects.
Top 10 Growth Companies With High Insider Ownership In Australia
| Name | Insider Ownership | Earnings Growth |
| Wisr (ASX:WZR) | 10.4% | 94.2% |
| Torque Metals (ASX:TOR) | 19.7% | 70.8% |
| Starpharma Holdings (ASX:SPL) | 21.1% | 75.1% |
| SKS Technologies Group (ASX:SKS) | 23.3% | 28.3% |
| PDI Gold (ASX:PDI) | 11.1% | 48% |
| Forrestania Resources (ASX:FRS) | 24.8% | 72.9% |
| Barton Gold Holdings (ASX:BGD) | 19.7% | 92.3% |
| Austral Resources Australia (ASX:AR1) | 24% | 28.2% |
| Adveritas (ASX:AV1) | 17.6% | 99.9% |
| Advanced Engineered Materials (ASX:AEM) | 35.1% | 58.7% |
Let's review some notable picks from our screened stocks.
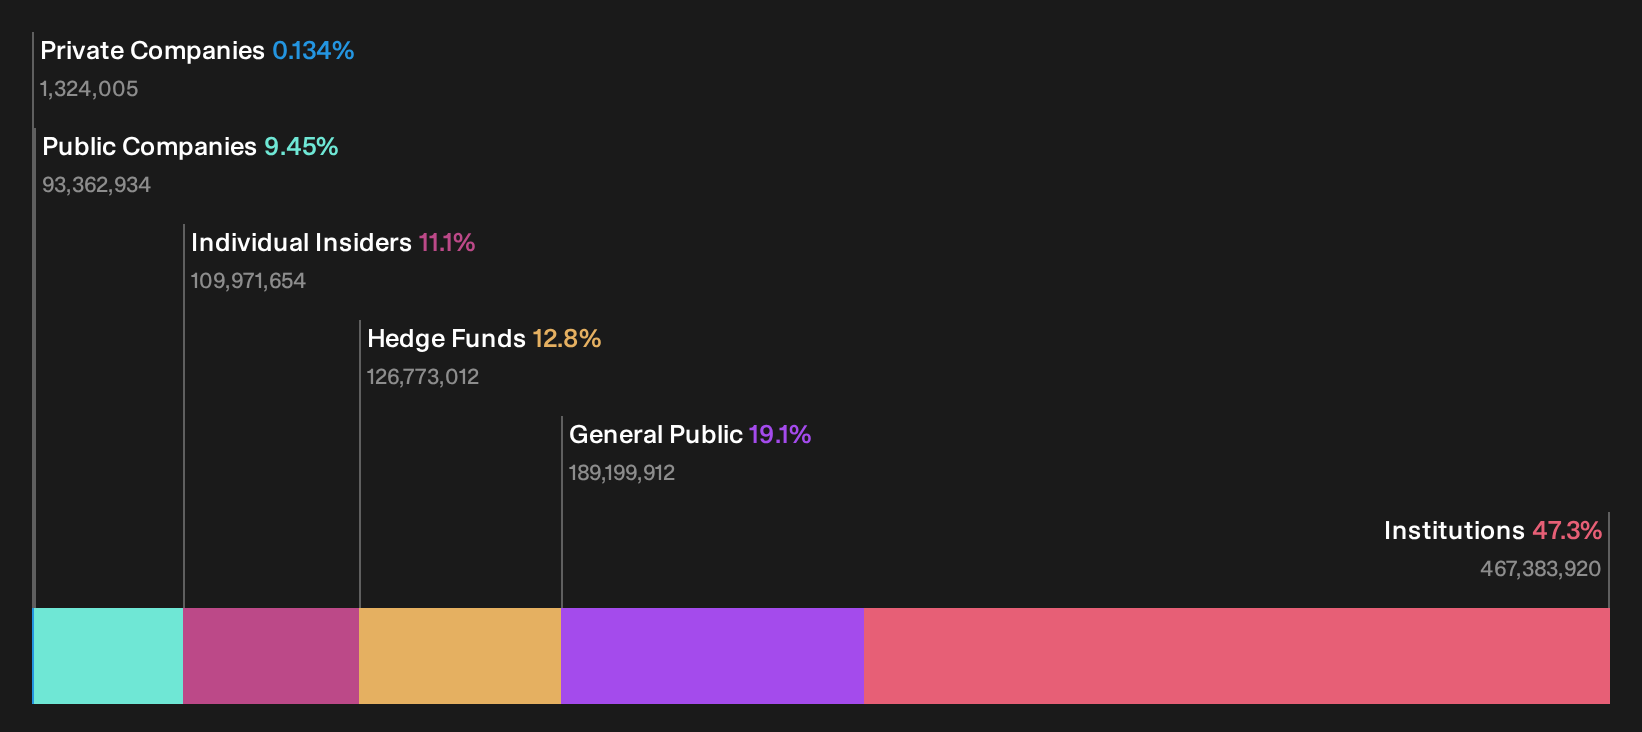
PDI Gold (ASX:PDI)
Simply Wall St Growth Rating: ★★★★★★
Overview: PDI Gold Limited is involved in the exploration, development, mining, and processing of gold deposits in West Africa with a market capitalization of A$4.42 billion.
Operations: The company's revenue is derived from its operations at the Nampala site, contributing $46.79 million, and the Kiniéro site, contributing $156.07 million.
Insider Ownership: 11.1%
Revenue Growth Forecast: 37% p.a.
PDI Gold Limited, recently rebranded from Predictive Discovery, has shown strong operational performance at its Kiniero and Nampala mines. Despite a net loss of US$68.38 million for the year ended June 2026, the company holds substantial mineral resources and ore reserves bolstered by favorable economic factors. With revenue growth forecasted at 37% annually and expected profitability within three years, PDI presents potential as a growth-focused investment in Australia's mining sector.
- Take a closer look at PDI Gold's potential here in our earnings growth report.
- The analysis detailed in our PDI Gold valuation report hints at an deflated share price compared to its estimated value.
Santana Minerals (ASX:SMI)
Simply Wall St Growth Rating: ★★★★★★
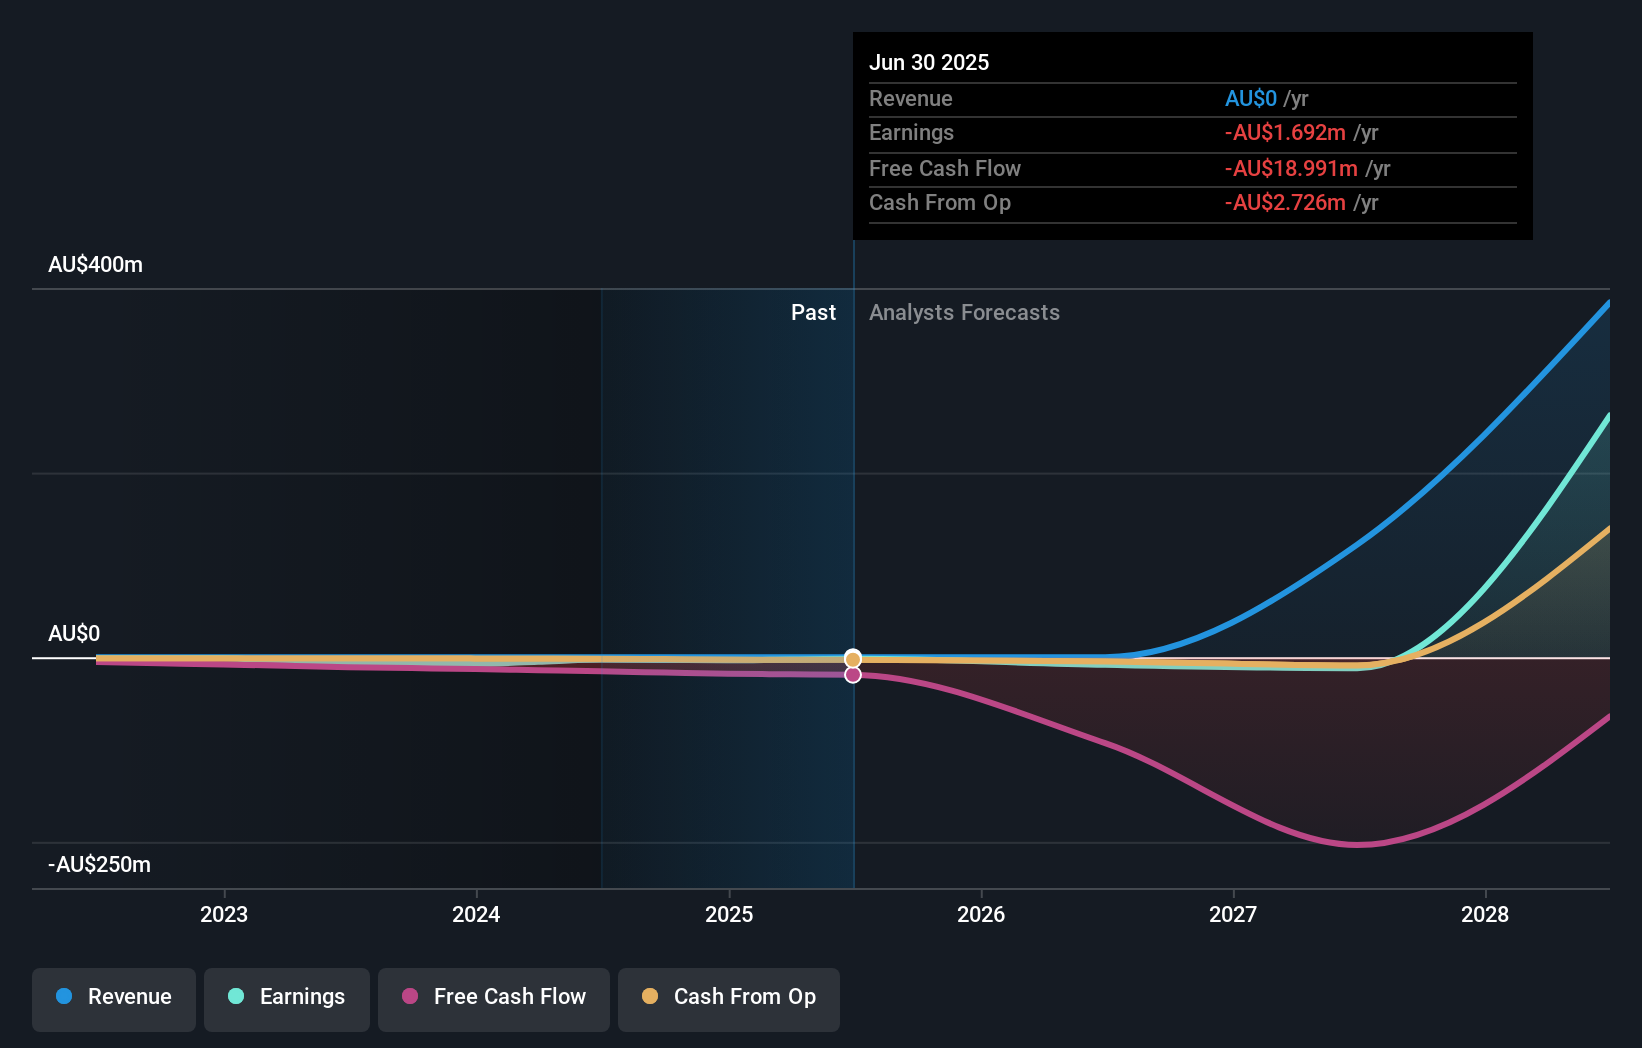
Overview: Santana Minerals Limited is involved in the exploration and evaluation of mineral properties in New Zealand and Cambodia, with a market cap of A$492.88 million.
Operations: The company does not report any revenue from its exploration and evaluation activities in New Zealand and Cambodia.
Insider Ownership: 11.6%
Revenue Growth Forecast: 53.6% p.a.
Santana Minerals is poised for significant growth with a forecasted revenue increase of 53.6% annually, outpacing the Australian market. Despite a recent net loss of A$1.41 million, the company's strategic infill drilling at Rise and Shine has yielded high-grade gold intercepts, enhancing resource confidence and potential profitability within three years. Trading substantially below estimated fair value, Santana's high insider ownership aligns management interests with shareholders amidst promising exploration outcomes.
- Delve into the full analysis future growth report here for a deeper understanding of Santana Minerals.
- In light of our recent valuation report, it seems possible that Santana Minerals is trading behind its estimated value.
Southern Cross Electrical Engineering (ASX:SXE)
Simply Wall St Growth Rating: ★★★★☆☆
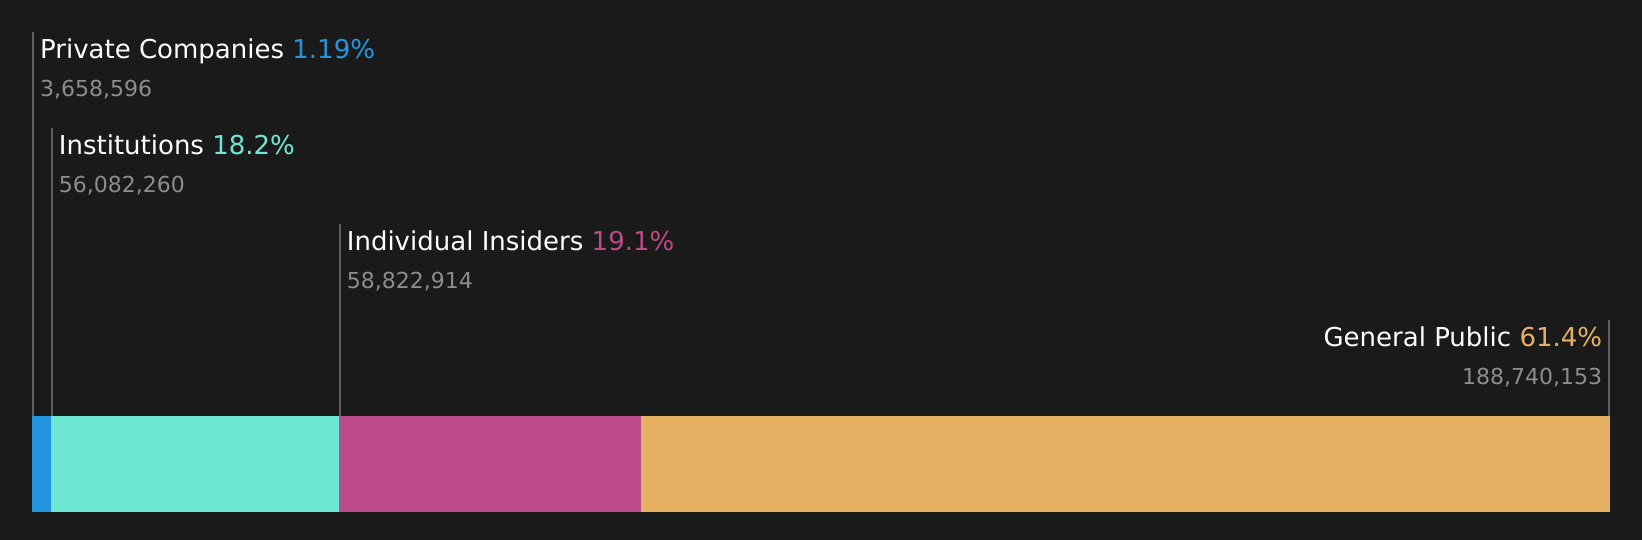
Overview: Southern Cross Electrical Engineering Limited, with a market cap of A$1.43 billion, offers electrical, instrumentation, communications, security, fire, and maintenance services and products across Australia.
Operations: The company generates revenue of A$718.70 million from its Electrical, Security, and Communication Services segment in Australia.
Insider Ownership: 17.8%
Revenue Growth Forecast: 18% p.a.
Southern Cross Electrical Engineering's inclusion in the S&P/ASX 300 and Small Ordinaries indices highlights its evolving market presence. Despite a recent drop in sales to A$718.7 million and net income to A$7.07 million, earnings are forecasted to grow significantly at 39.8% annually, outpacing the Australian market. Trading below estimated fair value, the company benefits from high insider ownership aligning management with shareholder interests, although profit margins have declined due to large one-off items impacting results.
- Click here and access our complete growth analysis report to understand the dynamics of Southern Cross Electrical Engineering.
- Upon reviewing our latest valuation report, Southern Cross Electrical Engineering's share price might be too optimistic.
Seize The Opportunity
- Click through to start exploring the rest of the 112 Fast Growing ASX Companies With High Insider Ownership now.
- Ready For A Different Approach? Uncover the next big thing with financially sound penny stocks that balance risk and reward.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com