
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Revenue Guidance Reaffirmed Altering The Investment Case For Genius Sports Stock (GENI)?
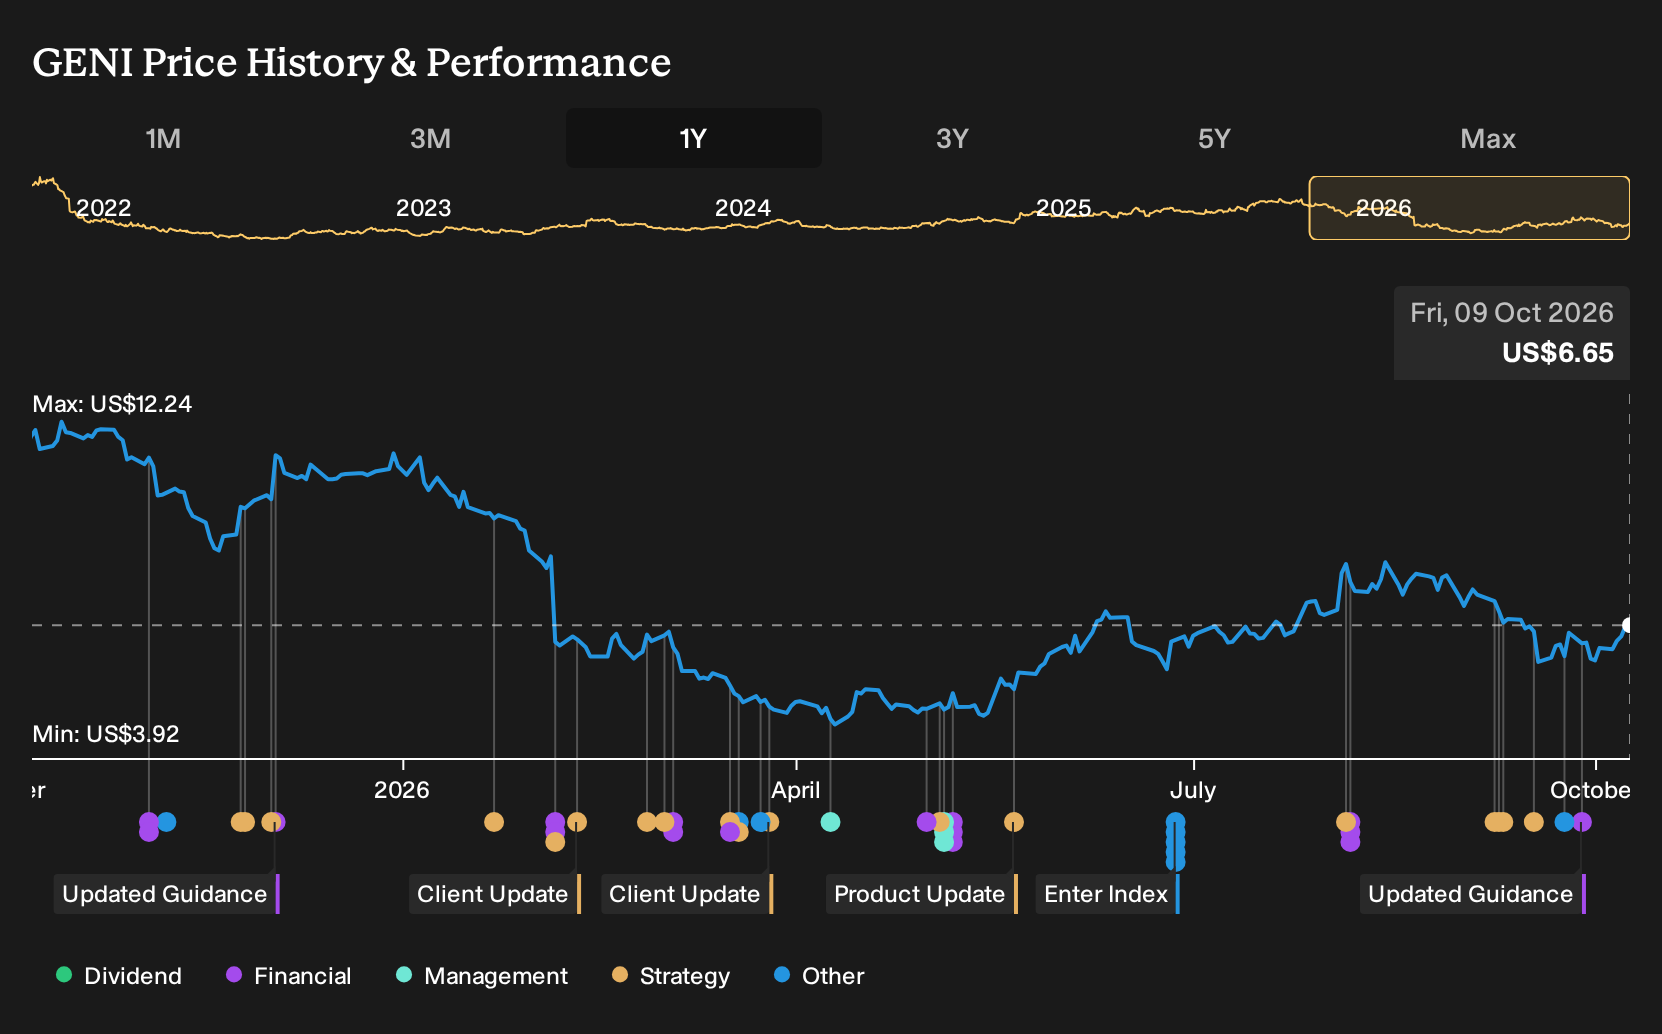
- Genius Sports reaffirmed its full year 2026 revenue guidance in late September, keeping expectations in a range of US$1.005b to US$1.025b.
- The reiterated outlook indicates that Genius Sports currently sees sufficient demand visibility across sports betting, media, and data rights to maintain a revenue target above one billion dollars.
- We will now examine how Genius Sports' reaffirmed 2026 revenue range fits within the existing investment narrative and risk framework.
Compare Genius Sports' reaffirmed billion dollar revenue ambition with other potential breakout plays by scanning our curated list of 20 high quality undiscovered gems.
Genius Sports Investment Narrative Recap
To own Genius Sports, you need to believe that official data, video and fan engagement tools can keep gaining traction with leagues, sportsbooks and advertisers. The reaffirmed 2026 revenue range above US$1b signals management still sees enough contracted and pipeline demand to support that scale, which speaks directly to the durability of its data rights and technology stack.
In the near term, the key swing factor is execution on large rights deals while controlling the cost of those contracts and the tech required to service them. The reaffirmed guidance does not materially change that equation, and it does not remove the risk that higher rights fees or intense competition could pressure margins.
With no fresh deal announcements alongside this guidance, the reaffirmation itself becomes the most relevant development. It links back to the core catalyst for Genius Sports: the monetisation of long term partnerships like Serie A, European Leagues and the expanded NFL agreements through products such as GeniusIQ, BetVision and FanHub led media services.
For you as an investor, the question is whether management can translate that content and technology footprint into the revenue growth analysts currently model and eventually into profits, while managing costs and regulatory friction in markets like the US, Europe and Brazil. The updated guidance does not resolve those execution and regulatory risks. However, it does provide a clearer revenue yardstick to measure progress against over the next few years.
Genius Sports' current analyst narrative points to US$1.7b in revenue and US$292.3 million in earnings by 2029. That profile aligns with forecast yearly revenue growth of 29.7% and an earnings swing of roughly US$474 million from a loss of US$181.6 million today to the projected profit base.
Discover why Genius Sports' fair value points to a 63% potential upside from its current price, which may materialize sooner than many investors anticipate.
Exploring Other Perspectives
One alternate view on Genius Sports leans heavily on rights cost pressure. The more cautious analysts previously pencilled in about US$1.6b of revenue and roughly US$198.1 million of earnings by 2029, which is well below the consensus earnings figure. Those estimates reflect a more restrained story, and the reaffirmed 2026 guidance could eventually push that narrative to adjust. You can treat this as a reminder that opinion ranges are wide and that it is worth exploring several scenarios before deciding how this stock fits your own portfolio goals.
Explore 3 other Genius Sports fair value estimates, including one that suggests it could be worth just $10.82!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Genius Sports research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Genius Sports. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Genius Sports' overall financial health at a glance.
Looking For More Investment Ideas Beyond Genius Sports?
If Genius Sports has sharpened your thinking about where growth and risk can show up in a portfolio, it can help to set it alongside other potential opportunities using a structured stock search. The Simply Wall St Screener lets you scan the market using clear filters so you can quickly build a watchlist that matches your own return goals and risk tolerance.
- If capital preservation comes first for you, start with resilient businesses that score well on stability metrics and review the 31 resilient stocks with low risk scores to see which ones fit that brief.
- If steady income matters more than price swings, focus on companies with higher yields and consistent distributions by checking out the 8 dividend fortresses in the screener.
- If you prefer growth potential backed by solid accounts, look through the list of solid balance sheet and fundamentals (25 results) to find candidates with stronger fundamentals supporting their expansion plans.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com