
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Visteon (VC) Revenue And Profit Rise, Is A $129 Fair Value Within Reach?
Visteon (VC) has been drawing fresh attention after a stretch of weaker share performance, with the stock down over the past month and past 3 months despite the company reporting higher revenue and net income.
Viewed over a longer stretch, Visteon’s share price has retreated, with the stock down 15.36% over the past month and 17.49% over the past quarter. This has contributed to an 11.82% year to date share price decline and a 21.83% drop in 1 year total shareholder return, which points to fading momentum as investors reassess both growth potential and risk around the current US$85.43 level.
Compare Visteon’s pullback with other auto and tech hardware stocks that also report higher revenue and net income by scanning our hand picked 29 high quality undervalued stocks.
Visteon is reporting higher revenue and net income while the share price has declined. The key question now is whether that combination creates genuine value at around US$85.43.
Most Popular Narrative: 34% Undervalued
Against Visteon’s last close at $85.43, the most followed narrative anchors fair value at $129.00. This implies a sizeable valuation gap that analysts link to future cockpit programs, mix shifts and planned cash returns that are not yet fully reflected in the share price.
Visteon's current pipeline of software defined cockpit programs, including SmartCore domain controllers and over US$1b of high performance compute cockpit bookings with launches starting in late 2026 and ramping from 2028, points to future revenue and earnings contributions that do not appear fully reflected in current valuation multiples.
See why 6 investors see Visteon as 34% undervalued.
Result: Fair Value of $129 (UNDERVALUED)
Still, the Visteon narrative can crack if memory cost inflation keeps pressuring margins, or if fading Ford and GM programs are not replaced fast enough.
Find out about the key risks to this Visteon narrative.
Another View: Visteon On Earnings Multiples
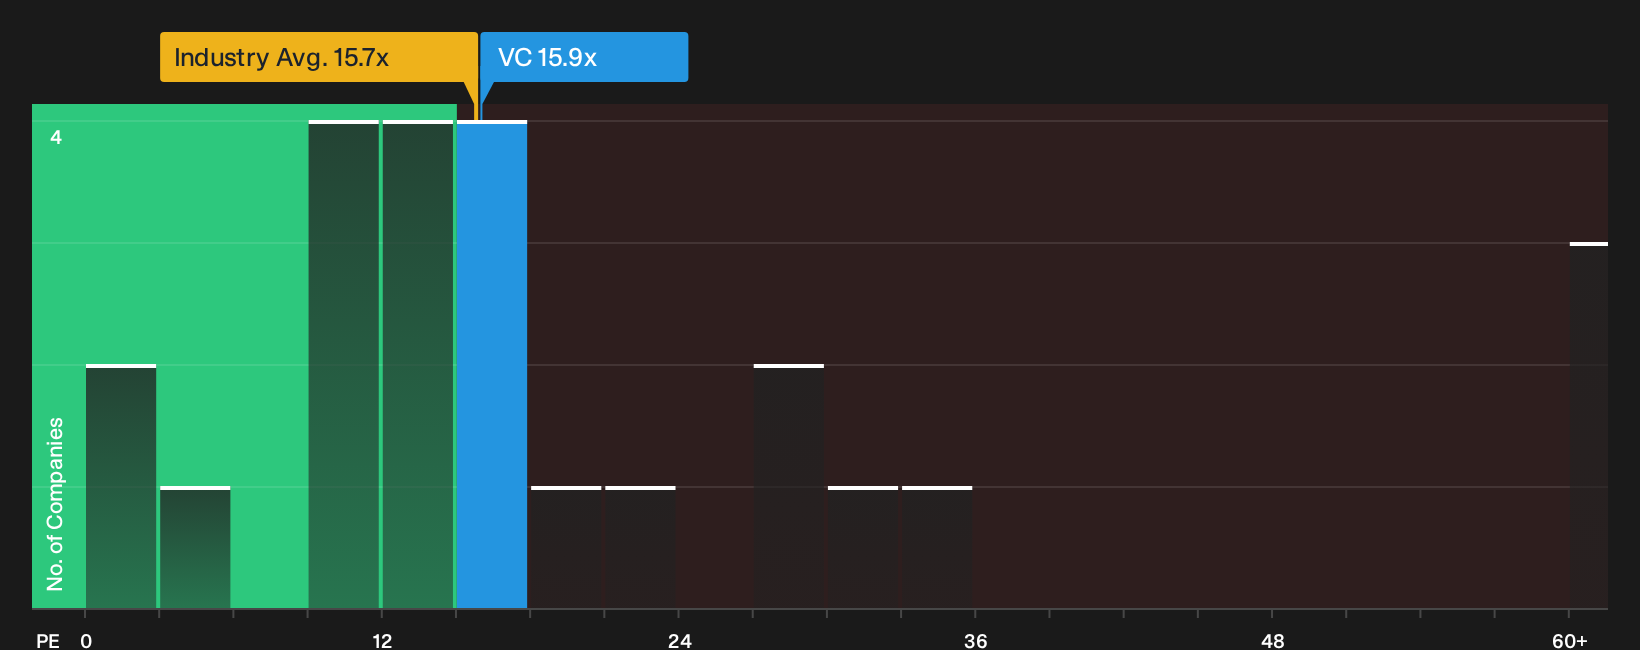
The story looks different when you shift from fair value estimates to simple earnings ratios. Visteon trades on a P/E of 15.9x, compared with 11.1x for peers and a fair ratio of 15.4x. That points to richer pricing than rivals. Is the cockpit software pipeline strong enough to justify paying up on this metric?
To see what the numbers say about this price gap, and how it could close over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Visteon is clearly split, with some investors focusing on potential upside and others wary of the risks that could cap returns. Act quickly, review the underlying data, and weigh both sides by checking the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Visteon?
If Visteon has you rethinking where to focus next, use this pullback as a prompt to scan fresh ideas that fit your own risk and return preferences.
- Target potential mispricings by reviewing companies on our 29 high quality undervalued stocks before other investors start paying closer attention.
- Build a sturdier core for your portfolio by focusing on businesses in the list of solid balance sheet and fundamentals (25 results) that may better handle tougher conditions.
- Protect against nasty surprises by focusing on the 31 resilient stocks with low risk scores that our models flag with more resilient risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com