
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Cameco (TSX:CCO) A Bargain After Its Global Uranium Conference Update?
Cameco (TSX:CCO) stepped into the spotlight at the Global Uranium Conference 2026 in Adelaide, as Vice-President of Investor Relations Cory Kos addressed uranium supply security, utility contracting and nuclear power investment trends.
Investor attention has picked up around Cameco as the uranium conference spotlight coincides with a recent pullback, with the share price down 7.20% year to date and a 30 day share price return of 6.27% in the red. However, longer term total shareholder returns of 154.16% over three years and 311.00% over five years point to momentum that has built over time rather than faded in recent months.
Scan beyond Cameco and identify other nuclear fuel and infrastructure stocks that may be poised for the next leg of the cycle with the curated 16 nuclear energy infrastructure stocks
The pullback in Cameco shares sits against a wide gap between the current CA$125.61 price and analyst and intrinsic estimates, so the key question is where fair value really lands as you weigh the next move in uranium exposure.
Most Popular Narrative: 30% Undervalued
Cameco’s most followed valuation storyline anchors fair value at CA$179.07 per share, well above the CA$125.61 last close. This puts the current pullback squarely against a bullish long-term thesis built on contracts, fuel services and Westinghouse exposure.
Cameco continues to be tied to a global wave of new nuclear construction, with government-backed programs in countries such as Canada, the U.S. and those pledging to expand nuclear capacity expected to support uranium and fuel demand over many years, which can feed into higher long-term revenues.
Momentum in utility contracting remains a live driver. Long-term uranium contracting is still below replacement rates, and Cameco is deliberately limiting new contract volumes while pushing for higher floors in the high US$70s per pound and ceilings around US$160 per pound on longer-tenor deals. This supports pricing power and potential net margin expansion.
See why 151 investors see Cameco as 30% undervalued.
Result: Fair Value of CA$179.07 (UNDERVALUED)
Still, the Cameco story can wobble if Saskatchewan production issues drag on or if cost inflation outpaces contract pricing and squeezes margins.
Find out about the key risks to this Cameco narrative.
Another View: Cameco looks expensive on sales
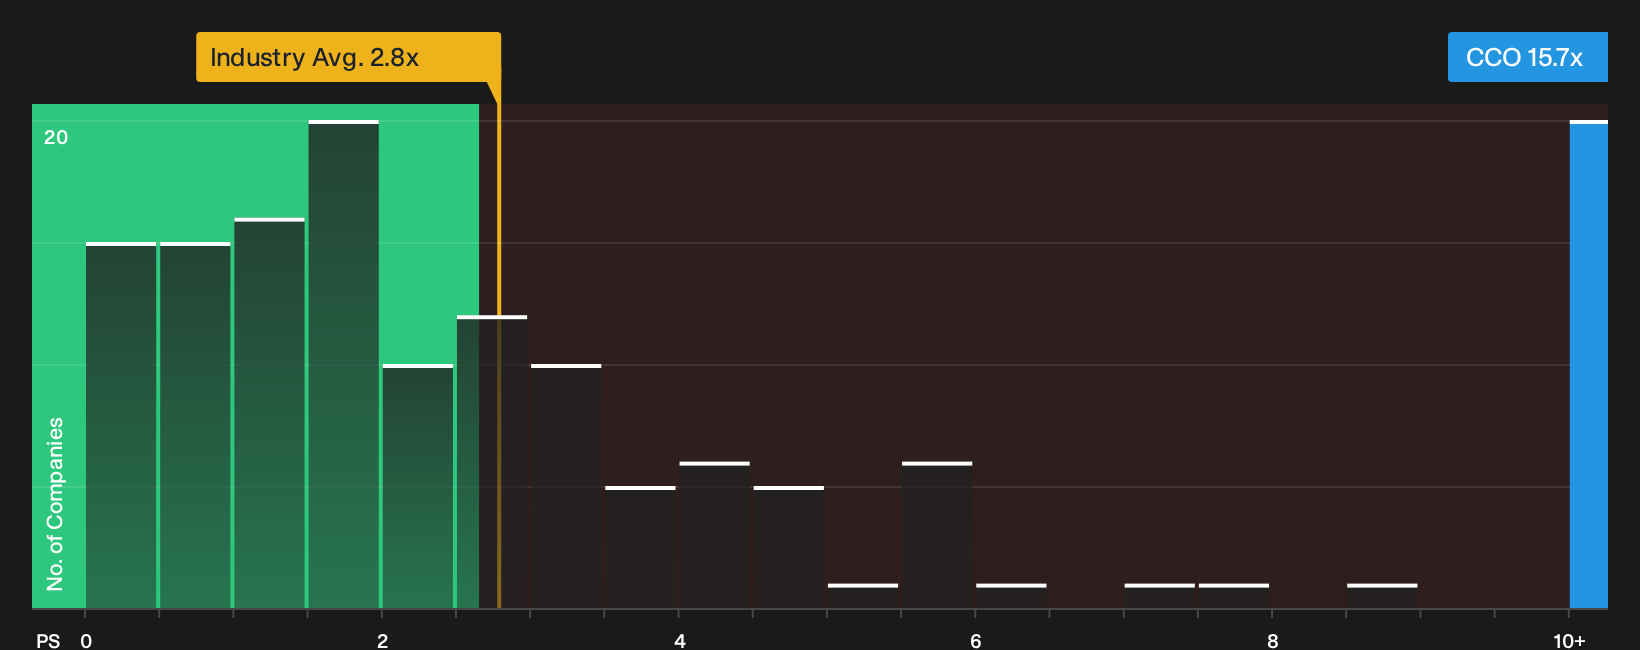
Cameco screens as undervalued on fair value estimates, yet its P/S ratio of 15.7x is far higher than the Canadian Oil and Gas industry at 2.8x and above the peer average at 8.9x. The fair ratio sits at 2x. That kind of gap points to potential valuation risk if expectations reset.
For a closer look at what the numbers imply for this pricing gap, including where the ratio could drift over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Bullish or cautious after all this Cameco detail? Act quickly, stress test the data against your own uranium thesis, then weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Cameco?
Consider exploring more than a single uranium stock. Use the Simply Wall Street Screener to uncover ideas that align with your risk profile and income goals.
- Scan for companies that combine robust fundamentals with a margin of safety via the 8 high quality undervalued stocks.
- Focus on businesses that show strong financial footing using the list of solid balance sheet and fundamentals (7 results).
- Target higher-yielding payers to potentially support your income objectives through the 3 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com