
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Diversified Earnings Change The Bull Case For Principal Financial Group Stock?
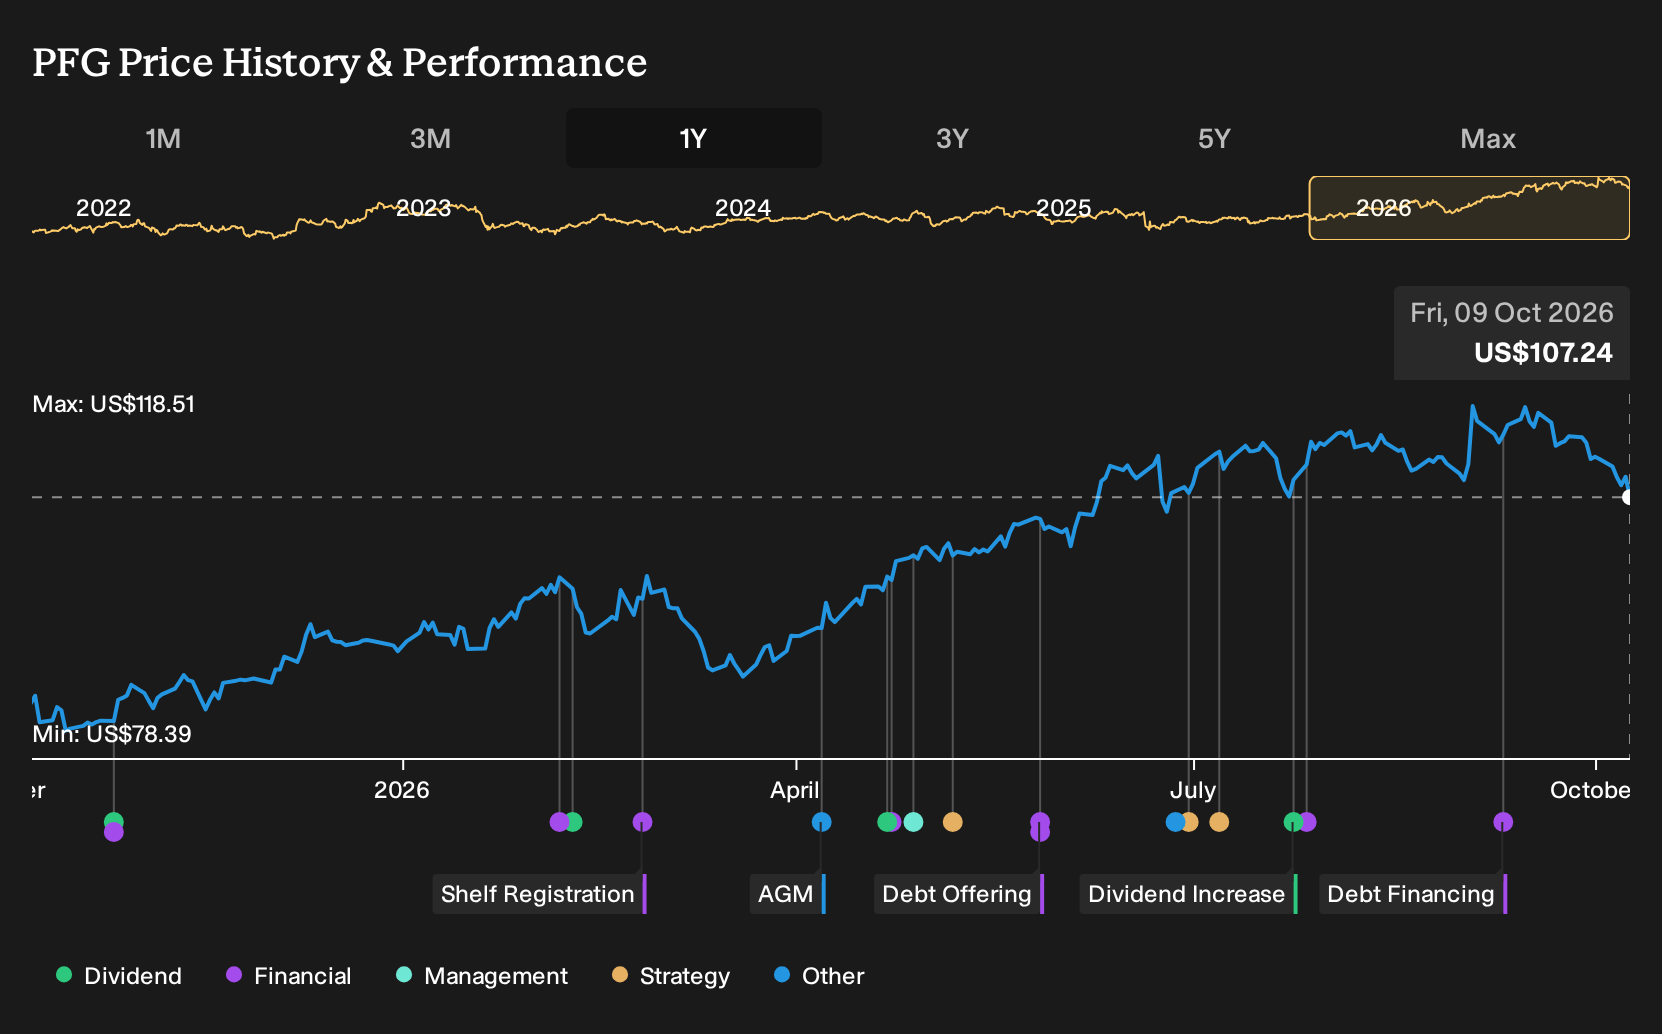
- Principal Financial Group has been attracting attention after its diversified mix of retirement, asset management, and benefits businesses, combined with recent acquisitions, was highlighted as a factor in its earnings profile and asset base.
- The stock currently trades at a discounted P/B value versus industry peers, which puts extra focus on how effectively management allocates capital and emphasizes core business areas.
- We will now look at how Principal Financial Group's investment narrative could be influenced by its diversified model and evolving asset base.
Compare Principal Financial Group's mix of retirement, asset management, and benefits exposure with a curated 29 high quality undervalued stocks that share a similar focus on diversified earnings and disciplined capital use.
Principal Financial Group Investment Narrative Recap
To own Principal Financial Group, you need to believe its mix of retirement, asset management, and benefits can keep generating steady fee and premium income while costs stay tightly controlled. The recent share price strength and discount to book value do not materially change that core thesis. The key near term swing factor is how effectively Principal converts its diversified model into consistent inflows and stable margins.
The biggest operational risk still sits in asset flows and client behavior. Prolonged market volatility or a tilt toward lower fee products could put pressure on revenue and net margins, especially after prior institutional fixed income outflows. Competitive pricing in dental and other benefits lines also limits how much Principal Financial Group can increase premiums without losing business.
The most relevant recent development is the reaffirmed Market Perform rating on Principal Financial Group by Keefe, Bruyette & Woods, along with a slightly reduced price target from US$117 to US$115. That type of move keeps attention on execution rather than narrative. It highlights how much the story now depends on consistent operational delivery rather than major expectation resets.
For you as an investor, the notable connection is between that neutral stance and the catalysts already in motion. Management is emphasizing cost discipline, a focus on higher fee mandates, and retirement exposure to small and mid sized employers. If those efforts support earnings quality and help offset any choppiness in flows, sentiment could remain relatively stable even if markets are volatile.
Principal Financial Group's current analyst narrative points to US$19.3b in revenue and US$2.7b in earnings by 2029, based on a 7.2% yearly revenue growth rate. That outlook compares with earnings today of US$1.6b and implies an earnings increase of about US$1.1b by the forecast year.
Uncover why Principal Financial Group's fair value indicates a 5% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view around Principal Financial Group leans heavily on fee pressure. The most bearish analysts already worked off lower numbers, with revenue expectations around US$19.2b and earnings of roughly US$2.5b by 2029. That cohort reads today’s news as a potential stress test for those cautious assumptions, which might shift again.
Explore 2 other Principal Financial Group fair value estimates, including one that suggests it could be worth just $112.08.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Principal Financial Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Principal Financial Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Principal Financial Group's overall financial health at a glance.
Looking for more investment ideas beyond Principal Financial Group?
Once you have formed a view on Principal Financial Group, it can help to set it beside other opportunities that align with your risk tolerance, return goals, and balance sheet preferences. The Simply Wall St Screener is built for that comparison, letting you filter the wider market using the same criteria you care about here.
- For investors who want income with resilience, consider income focused opportunities with a 8 dividend fortresses that aim to pair higher yields with durable cash flows.
- If capital protection matters most, look for companies on a 31 resilient stocks with low risk scores that score well on financial strength and business stability.
- For those hunting for mispriced potential, scan through a 20 high quality undiscovered gems that flag under followed businesses with solid fundamentals that might not be on every investor's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com