
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Tosei (TSE:8923) Could Be 31% Above Fair Value On Raised Profit And Dividend Forecasts
Tosei raises profit and dividend forecasts after nine month results
Tosei (TSE:8923) has paired its nine month earnings release with higher profit and dividend forecasts, even as it trims revenue guidance for the fiscal year ending November 30, 2026.
The update gives investors fresh numbers on Revitalization, Rental, and Fund and Consulting performance, and a revised dividend outlook, to reassess both income potential and risk around the stock.
Tosei shares trade at ¥1,655 after a 1-day share price gain of 1.85%, although the stock has slipped 4.5% over the past 90 days as investors weigh the trimmed revenue forecast against higher profit guidance and a richer dividend outlook.
Over a longer stretch, momentum has been strong, with a 1-year total shareholder return of 6.66%, a 3-year total shareholder return close to 2x, and a 5-year total shareholder return of more than 3x. This suggests the latest move comes after a very extended run.
Spot opportunities with a similar profit and dividend focus by scanning our hand picked 28 dividend fortresses alongside Tosei.Tosei’s profit and dividend upgrade points to a resilient real estate platform, yet the share price has slipped recently. Is this still a quality business available at a sensible valuation today?
Price-to-earnings of 10.4x for Tosei: Is it justified?
Tosei trades on a P/E of 10.4x, which is lower than the wider JP market but higher than the domestic real estate group, so investors are effectively paying a mid-range earnings multiple for the shares at ¥1,655.
The P/E ratio compares the current share price with earnings per share and gives you a shorthand way to see how much the market is willing to pay for current profits. For a property focused business like Tosei, this matters because earnings can be cyclical, and a richer multiple often reflects expectations that profit quality and growth will hold up through the cycle.
Relative to peers, the stock screens as inexpensive against the peer average P/E of 14.2x and also below an estimated fair P/E of 12.7x. However, it trades at a premium to the JP real estate industry average of 9.5x. That combination suggests the market is assigning Tosei a higher rating than the sector, while still leaving room for the valuation to move closer to the fair ratio level if earnings delivery lines up with expectations.
Explore the SWS fair ratio for Tosei.
Result: Price-to-earnings of 10.4x (ABOUT RIGHT)
Still, Tosei’s real estate focus ties earnings closely to property cycles, and any slowdown in asset transactions or hotel demand could pressure that mid-range P/E story.
Find out about the key risks to this Tosei narrative.
Another view on Tosei’s valuation
The SWS DCF model paints a different picture for Tosei. On that cash flow view, an estimated value of ¥1,152.88 per share sits well below the current ¥1,655 price, which points to the stock trading on the expensive side rather than at a bargain. Which lens do you trust more when real estate cycles turn?
Look into how the SWS DCF model arrives at its fair value.
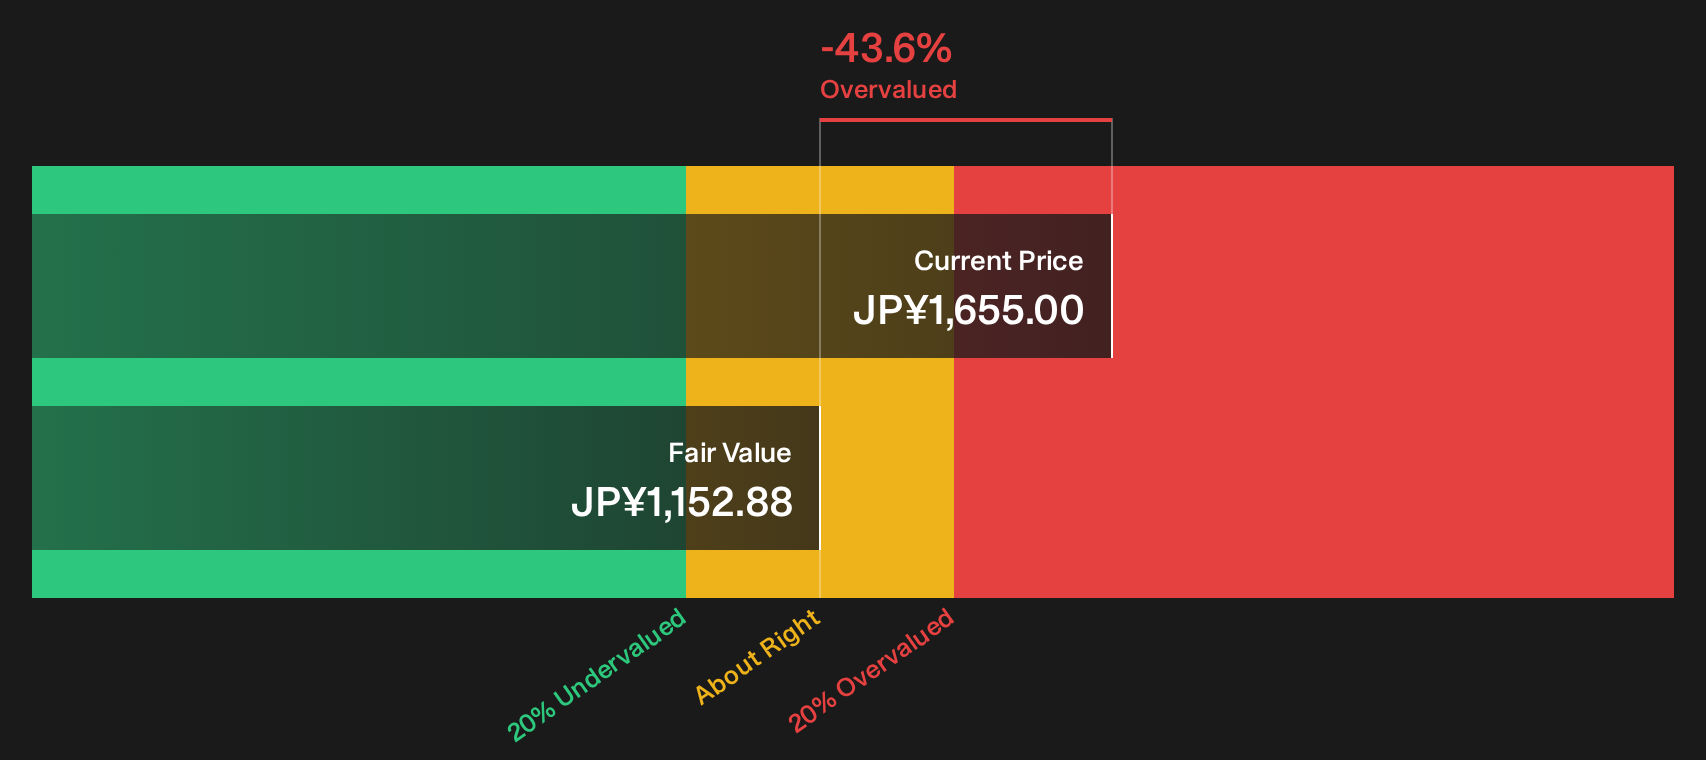
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tosei for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sitting between mixed valuation signals and a richer dividend outlook, Tosei has both supporters and skeptics. If you want a clearer picture before sentiment shifts again, start by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Tosei?
If Tosei has sharpened your focus on valuation and income, you can use that momentum to widen your opportunity set with targeted screeners built around quality and risk.
- Focus on quality at a discount by scanning our hand picked 13 high quality undervalued stocks that blend solid financials with appealing pricing.
- Support capital protection by reviewing the 23 resilient stocks with low risk scores that score well on resilience and balance sheet stability.
- Explore potential opportunities by combing through 74 high quality undiscovered gems that pair strong fundamentals with relatively low attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com