
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Evergy (EVRG) Earnings And Data Center Growth
- Evergy reported second quarter adjusted earnings of US$0.88 per share compared with US$0.82 a year earlier, reaffirmed its 2026 adjusted EPS guidance midpoint of US$4.24, and highlighted contributions from regulated investment recovery, load growth, and large customer revenues.
- The utility also underscored how its data center push is reshaping the business, with five Electric Service Agreements totaling 3 GW of load and plans for at least one additional ESA in 2026 to deepen this large customer base.
- This article examines how Evergy's investment narrative interacts with expanding data center contracts that support its large-load demand profile.
Scan Evergy's data center push alongside a curated field by comparing it with 43 power grid technology and infrastructure stocks.
Evergy Investment Narrative Recap
For Evergy, the basic belief is that regulated infrastructure spending and long term data center contracts can support a steadier earnings path than a typical cyclical business. The latest quarter, with adjusted EPS of US$0.88 and guidance reaffirmed at a US$4.24 midpoint for 2026, keeps that thesis intact rather than changing it.
The main near term swing factor is execution on grid and generation projects while keeping customer bills acceptable as large loads ramp. The biggest risk still sits in the capital stack. Heavy spending funded with debt and equity could pressure margins if operating costs, depreciation and interest weigh on results.
The reaffirmed 2026 adjusted EPS guidance midpoint of US$4.24 is the announcement that matters most here. It ties the current data center contract wins directly to Evergy’s near term earnings path and indicates that management views the existing capital plan and five ESAs as sufficient to support its targets for now.
For you as an investor, the key question is whether Evergy can keep delivering against that guidance while it funds about US$21.6b of planned spend from 2026 to 2030. Execution on the data center build out, regulatory outcomes around rate cases, and the cost of servicing higher interest obligations remain the practical catalysts to track.
Evergy's current analyst setup points to revenue of US$7.4b and earnings of US$1.3b by 2029, anchored on analyst expectations for revenue growth of 6.5% a year and an earnings step up of about US$374m from US$925.8m today.
Uncover why Evergy's fair value indicates a 13% potential upside to its current price that could narrow quickly.
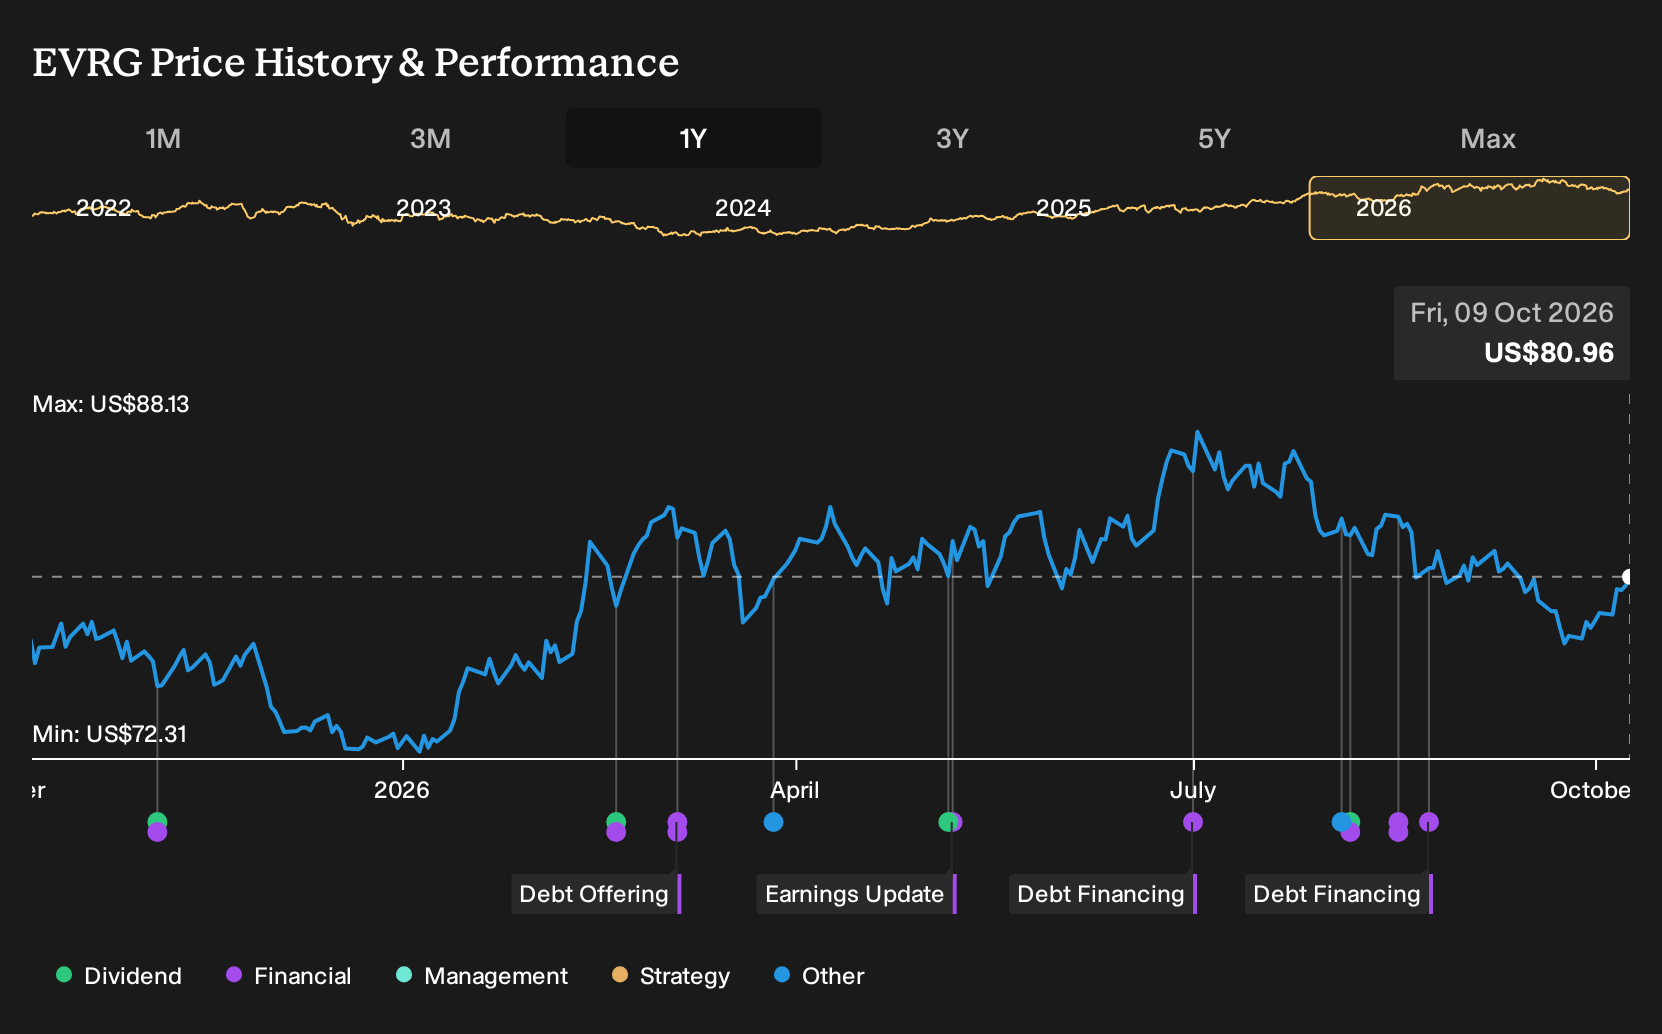
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$61 to US$91 per share, which highlights how far apart individual views on Evergy can be. Those investors are weighing the same story you are: heavy capital spending, large ESAs and regulatory responses could all reshape how the business performs over time. Explore several alternative viewpoints before you decide what the current price implies.
Explore another Evergy fair value estimate, including one that suggests as much as 13% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Evergy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Evergy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Evergy's overall financial health at a glance.
Looking for more investment ideas beyond Evergy?
Once you have a view on Evergy, it can help to put that thesis in context by comparing it with other businesses that match your preferred style, whether that is value, income, or resilience. The Simply Wall St Screener lets you scan a wider field in a structured way rather than jumping between tickers at random.
- If you want to focus on quality at a reasonable price, start with a curated set of companies that look attractively priced on fundamentals through the 29 high quality undervalued stocks.
- For income focused ideas, you could look at businesses with higher yields and an emphasis on resilience by reviewing the 8 dividend fortresses.
- If balance sheet strength matters most to you, filter for companies with sturdier finances and cleaner leverage profiles using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com