
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Glaukos (GKOS) Cheap After Its iDose TR Phase 4 Win?
Glaukos (GKOS) is back in focus after reporting that its Phase 4 trial of iDose TR used during cataract surgery met the primary efficacy endpoint, with clinically meaningful intraocular pressure reductions and a favorable safety profile.
Glaukos shares have been volatile around the recent stream of clinical and licensing headlines, with the iDose TR Phase 4 readout following fresh Epioxa Phase 3 extension data and the RevOpsis retinal biologics deal earlier this week.
At a latest share price of US$165.69, the stock has a 1-day share price return of 2.73% and a 90-day share price return of 8.49%. The year-to-date share price return of 49.65% sits alongside a 1-year total shareholder return of 100.69%, indicating momentum over both the short and long term.
Scan beyond Glaukos and explore how other ophthalmic and medical specialists are reflecting similar momentum with our curated list of 34 healthcare AI stocks.
Glaukos has already doubled shareholders' money over the past year, yet fresh iDose TR and Epioxa readouts keep resetting expectations. Is the recent surge capturing most of that progress, or does the current valuation still leave clear upside?
Most Popular Narrative: 16% Undervalued
Glaukos is framed as undervalued in the most followed narrative, with a fair value of about $196.46 against the latest close at $165.69. That gap rests on a story about glaucoma treatment shifting toward procedures where Glaukos already has a meaningful foothold.
Strong ongoing adoption and utilization of iDose TR, a first-of-its-kind procedural pharmaceutical with a unique profile, suggests the early stages of a paradigm shift toward interventional glaucoma therapies. This is viewed as a substantial long-term opportunity given the aging population and rising prevalence of glaucoma, which is cited as a likely driver of robust multi-year revenue and market expansion.
See why 2 investors see Glaukos as 16% undervalued.
Result: Fair Value of $196.46 (UNDERVALUED)
Still, the Glaukos story could change quickly if reimbursement rules tighten or if competition in minimally invasive glaucoma procedures takes more share than bulls expect.
Find out about the key risks to this Glaukos narrative.
Another View: Glaukos Looks Expensive On Sales
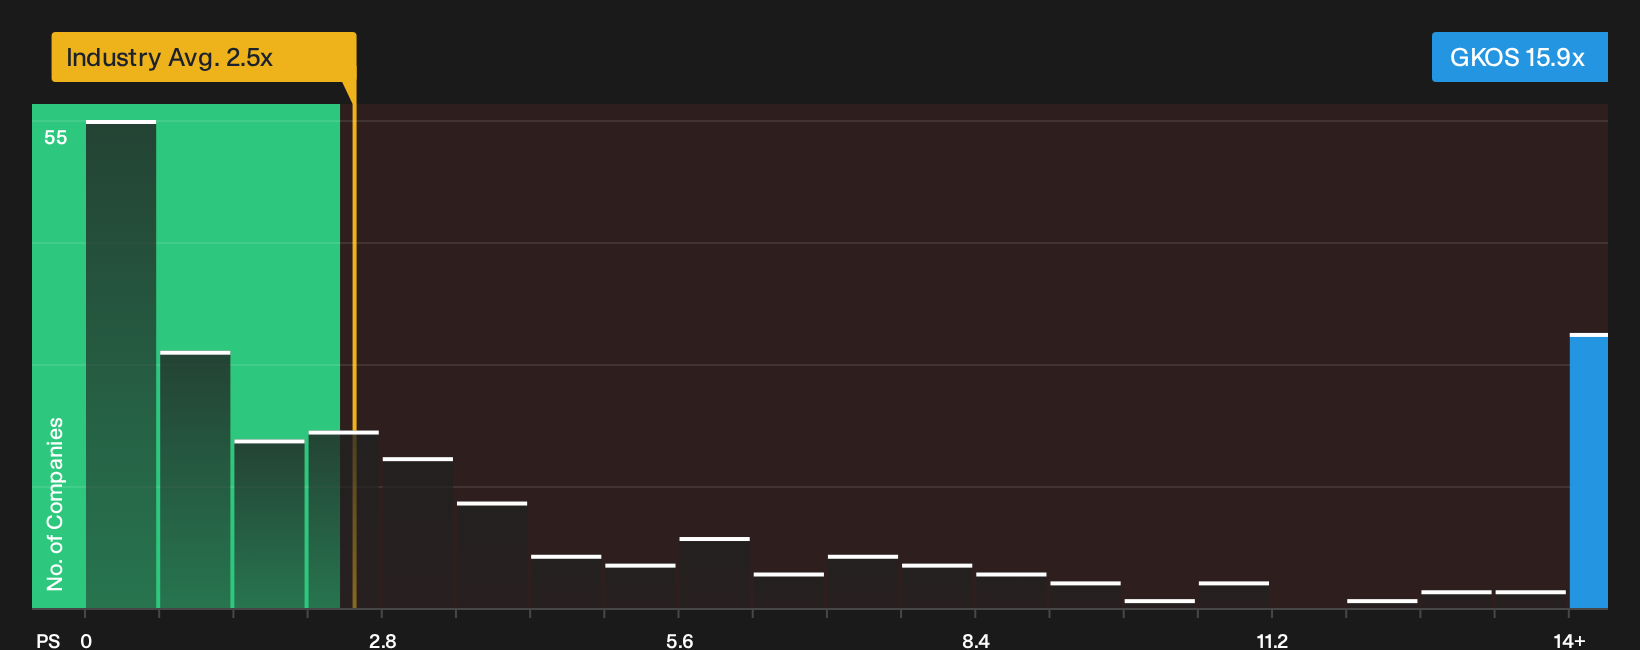
Glaukos screens very differently once you shift from fair value models to a simple sales multiple. The shares trade on a P/S ratio of 15.9x, versus 2.5x for the US Medical Equipment industry, 3.9x for peers, and a fair ratio of 9x. That gap points to real valuation risk if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Glaukos story looks exciting, yet some signals urge caution. Move quickly, review the underlying data, and weigh both 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Glaukos?
Do not stop your research with Glaukos. Spread your watchlist across different styles of opportunities so one story never decides your whole investing outcome.
- Target potential mispricing and look for quality businesses trading below their implied worth with the 29 high quality undervalued stocks.
- Focus on steady cash returns and evaluate companies in the 8 dividend fortresses to help strengthen your income stream.
- Limit portfolio risk and concentrate on resilience by reviewing the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com