
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Sezzle Stock In Focus Before Earnings Report
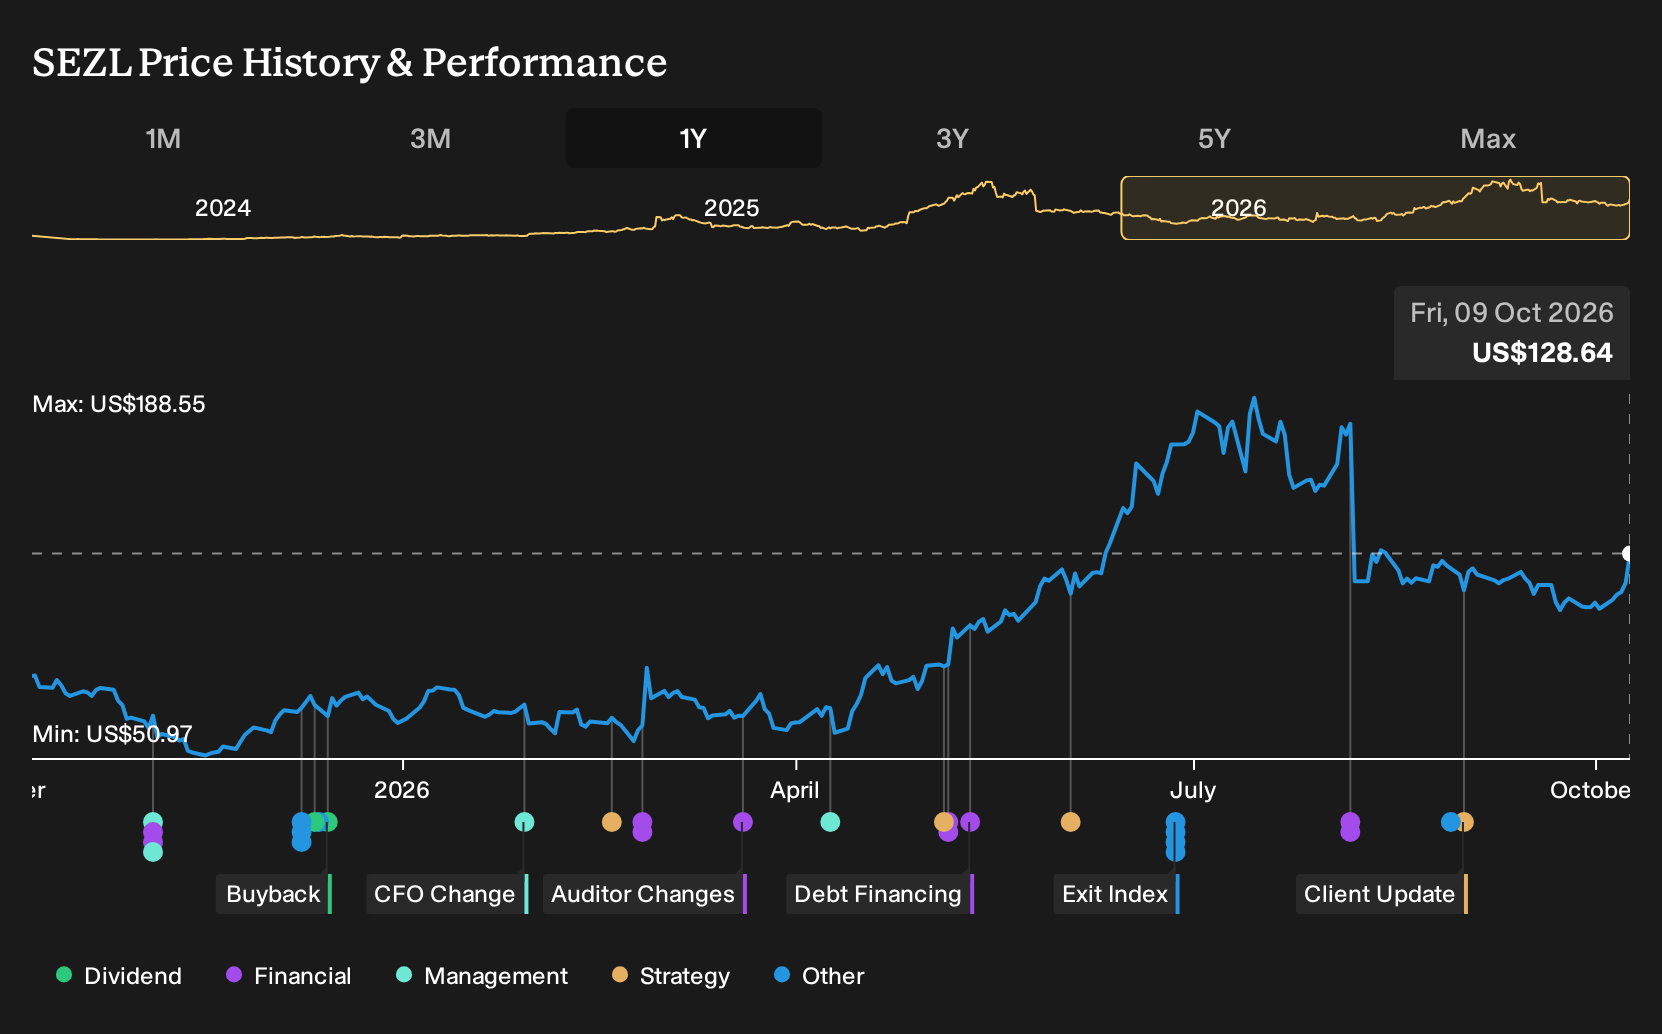
- Sezzle has drawn fresh attention after survey data showed that 66% of shoppers may abandon a cart without their preferred BNPL option, while the firm prepares to report third quarter results on 4 November 2026 and continues to expand payment plans, virtual cards and subscription services.
- The combination of strong checkout relevance, a broadening mix of products such as Sezzle Anywhere and long term lending, and a current P/E that sits above the US diversified financials industry average places execution, credit quality and product uptake under a brighter spotlight for investors tracking Sezzle's fundamentals.
- Investors will now be watching how Sezzle's role in reducing cart abandonment could influence the existing investment narrative around its BNPL platform.
Sezzle Investment Narrative Recap
To own Sezzle, you need to believe its role in checkout conversion and flexible payment plans can keep attracting both merchants and consumers, while newer services like Sezzle Anywhere, virtual cards and long term lending deepen engagement. The key near term swing factor is execution on these products as usage patterns become clearer.
The recent survey highlighting cart abandonment risk keeps the focus on Sezzle’s relevance at checkout rather than changing the main catalyst. The main catalyst remains adoption across its broader ecosystem. The biggest current risk sits around valuation and volatility, with a P/E above the US diversified financials average and a history of sharp price moves.
The upcoming third quarter results on 4 November 2026 are the most relevant near term milestone. This update will give you a fresh read on active subscribers, virtual card usage, transaction frequency and credit performance. Each of these metrics feeds directly into how durable Sezzle’s current economics look as it leans further into subscriptions and long term lending.
That earnings release will also sit alongside an active legal and funding backdrop, including the antitrust suit in discovery and reliance on higher risk funding sources rather than deposits. When you weigh the Morning Consult survey against those factors, the operational question becomes whether strong checkout relevance and a broader product mix can offset legal, funding and pricing pressure if sentiment cools.
What The Current Sezzle Forecasts Actually Assume
Forecasts around Sezzle hinge on a fairly specific set of numbers. Analysts are working off annual revenue growth assumptions of 22.8% over the next three years and an earnings path that rises from current profit of US$161.4 million to a consensus of US$333.5 million by 2029. That shift implies earnings roughly doubling, about 2.1x, from today’s level. On those same projections, revenues are expected to reach US$984.2 million in 2029, paired with margins moving from 30.4% today to 33.9% over the same horizon.
Sezzle's narrative projects US$984.2 million revenue and US$333.5 million earnings by 2029. This requires 22.8% yearly revenue growth and an earnings increase of roughly 2.1x from US$161.4 million today.
Uncover why Sezzle's fair value indicates a 31% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternative angle on Sezzle leans heavily on funding firepower as the main catalyst. The most optimistic analysts focused on the US$300 million receivables facility and roughly US$205 million of liquidity, then built forecasts toward about US$1.1b of revenue and US$353.8 million of earnings by 2029. Those projections came before the cart abandonment survey, so you may see opinions shift as checkout dependence on BNPL becomes clearer. Treat this as a reminder that views can be wide apart and worth comparing rather than following any single story.
Explore 9 other Sezzle fair value estimates, including one that suggests there could be as much as 52% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sezzle research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sezzle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sezzle's overall financial health at a glance.
Looking for more Sezzle style investment ideas?
If Sezzle has sharpened your focus on where growth, resilience and cash generation intersect, it can help to scan a broader field of opportunities using targeted filters.
- For readers hunting for mispriced quality, start with companies that screen well on both valuation and fundamentals through the 29 high quality undervalued stocks.
- If capital preservation and steadier profiles matter more to you right now, sort for businesses that clear a high bar on financial strength and balance sheet resilience with the list of solid balance sheet and fundamentals (25 results).
- Income focused investors can zero in on cash return potential by filtering for higher yield payers that still pass basic quality checks using the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com