
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Stocks Riding The M And A Recovery Including ServiceNow Stock
Higher rates, cheaper valuations and a reset in deal appetite are pulling mergers, carve outs and corporate restructurings back onto boardroom agendas, and that is where opportunity often hides in plain sight. When capital becomes more selective, the companies that help others buy, sell and reshape businesses can suddenly move from background advisers to central players. This article walks through three stocks exposed to that deal making story and shows how the same news catalyst can create potential openings as well as risks for your portfolio.
The companies discussed next are just a starting sample of this theme, and the full screen surfaced 11 more listed players with similarly interesting M&A and restructuring stories that are not covered below. To identify and analyze your own highest conviction ideas in this corner of the market, head straight into the M&A and Corporate-Transformation Enabler Stocks screener.
ServiceNow (NOW)
Overview: ServiceNow runs a cloud platform that helps large organisations automate and connect IT, customer, HR and other workflows across departments.
Operations: ServiceNow generates about US$14.7b from internet software and services, with roughly US$8.8b from the United States and the rest across EMEA and Asia Pacific.
Market Cap: US$145.6b
ServiceNow matters in this screener because it is often the behind the scenes workflow engine that private equity owners and large corporates rely on when they integrate acquisitions, separate units or rebuild processes with AI driven automation across multiple departments.
"Agentic AI monetization: ServiceNow AI crossed $1 billion in annual contract value in Q2 2026, suggesting AI is moving from experimentation toward meaningful enterprise spending."
What happens to ServiceNow’s appeal to M&A buyers if one unseen pressure on how quickly enterprises standardize onto fewer workflow platforms shifts?
That pressure point is exactly where ServiceNow’s story gets interesting, so read the full narrative for ServiceNow to see how its workflow engine could accelerate or stall as dealmaking reshapes IT spending.

International Business Machines (IBM)
Overview: International Business Machines delivers hybrid cloud, AI, consulting, infrastructure and financing services that help large organisations modernise complex technology and data heavy operations.
Operations: IBM generates about US$31.1b from Software, US$21.3b from Consulting, US$15.9b from Infrastructure and US$33.9b from the Americas region.
Market Cap: US$214.0b
When private equity firms and large corporates need to restructure portfolios or integrate acquisitions at scale, IBM often becomes the behind the scenes systems and consulting partner stitching everything together.
"IBM's focused strategy on hybrid cloud and AI remains central as software reaches nearly 45% of total revenue, and about 80% of that software revenue is recurring."
What happens to IBM’s earnings resilience if one quiet assumption about how quickly enterprises replatform critical systems and AI workloads shifts?
As that timetable shifts, read the full narrative for International Business Machines to see whether IBM’s recurring software weight is quietly accelerating, or masking, its M&A restructuring role.
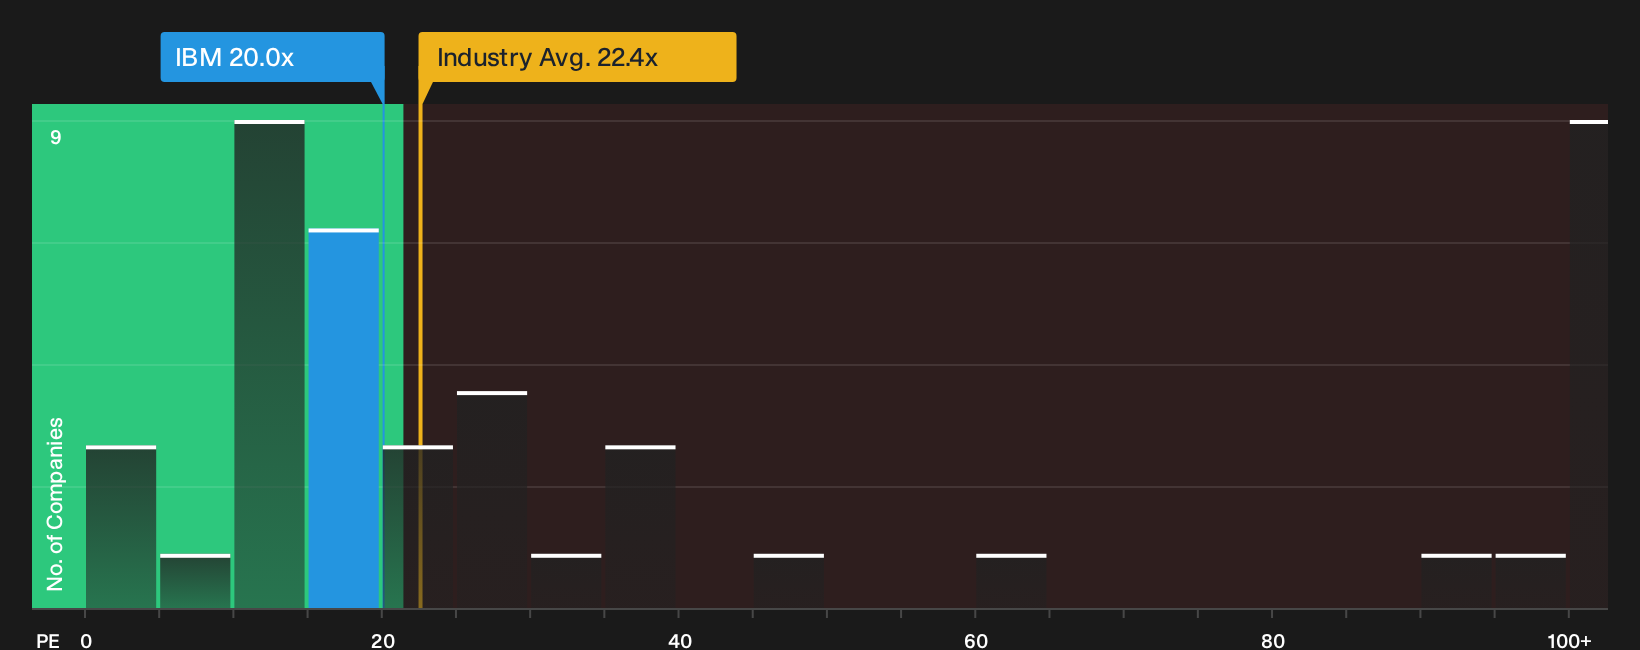
Nagarro (XTRA:NA9)
Overview: Nagarro is a global digital engineering partner that builds and integrates complex software systems for enterprises undergoing M&A, carve outs and large scale technology transformations.
Operations: Nagarro generates about €1.0b from computer services, with sizeable contributions from the United States, Germany and the rest of the world.
Market Cap: €957 million
Where ServiceNow and IBM often supply the platforms and heavy consulting, Nagarro is the hands on builder wiring acquired assets, carve outs and AI driven overhauls into working digital products for private equity portfolios and corporates that are reshaping themselves.
"The push to reposition the business around AI centric Fluidic Intelligence and centralize AI assets into the Fluidic Forge requires retraining staff, changing sales motions and running complex, long duration client programs. If execution on this shift stalls or client adoption is slower than hoped, it could dilute pricing power and limit improvements in net margins."
What happens to Nagarro’s deal linked appeal if one quiet assumption about how clients share the benefits of AI productivity shifts.
If that profit sharing balance is the real swing factor, the full narrative for Nagarro shows where Nagarro’s AI shift could accelerate or quietly stall margins in the next phase.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout trends, dropping risk and under the radar stories can get caught quickly once momentum starts flying. Scan the next wave and act now.
- Spot steady payers before yields get compressed by late money chasing income across the market using the 8 dividend fortresses.
- Track early AI momentum where profits already matter, not just hype cycles, through the curated 39 profitable AI stocks that aren't just burning cash.
- Follow real-world infrastructure demand as electrification builds, grid spending rises and capital rotates into enablers with the focused 43 power grid technology and infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com