
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
The Call ICBC Bulls Got Right
If you only glanced at the headlines about hidden bad debts in China’s banking system and fresh capital injections into state lenders, you might have expected a rough year for Industrial and Commercial Bank of China. Investors who held Industrial and Commercial Bank of China over the past year are up 43.1%, including dividends. If you had bought on 9 October 2025, with knowledge limited to the loud debate between bullish digital growth hopes and bearish macro worries, what exactly did that contrast ask you to weigh?
Industrial and Commercial Bank of China has already moved. See which of 178 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing On Industrial and Commercial Bank of China
The shares cost HK$5.65 at the start of the period. Anyone looking at Industrial and Commercial Bank of China then was really choosing between two sharply different stories about where the bank could head next.
On the optimistic side, the bullish view saw digital transformation and Belt and Road expansion lifting earnings. A Fair Value of HK$6.99, the price those expectations implied, was built on 12.1% annual revenue growth and a future P/E of 7.5x.
The cautious view focused on slowing Chinese growth, demographic pressure, and policy lending. It pointed to a Fair Value of HK$5.08 and raised concern that high exposure to real estate and local government borrowers could keep credit risk elevated.
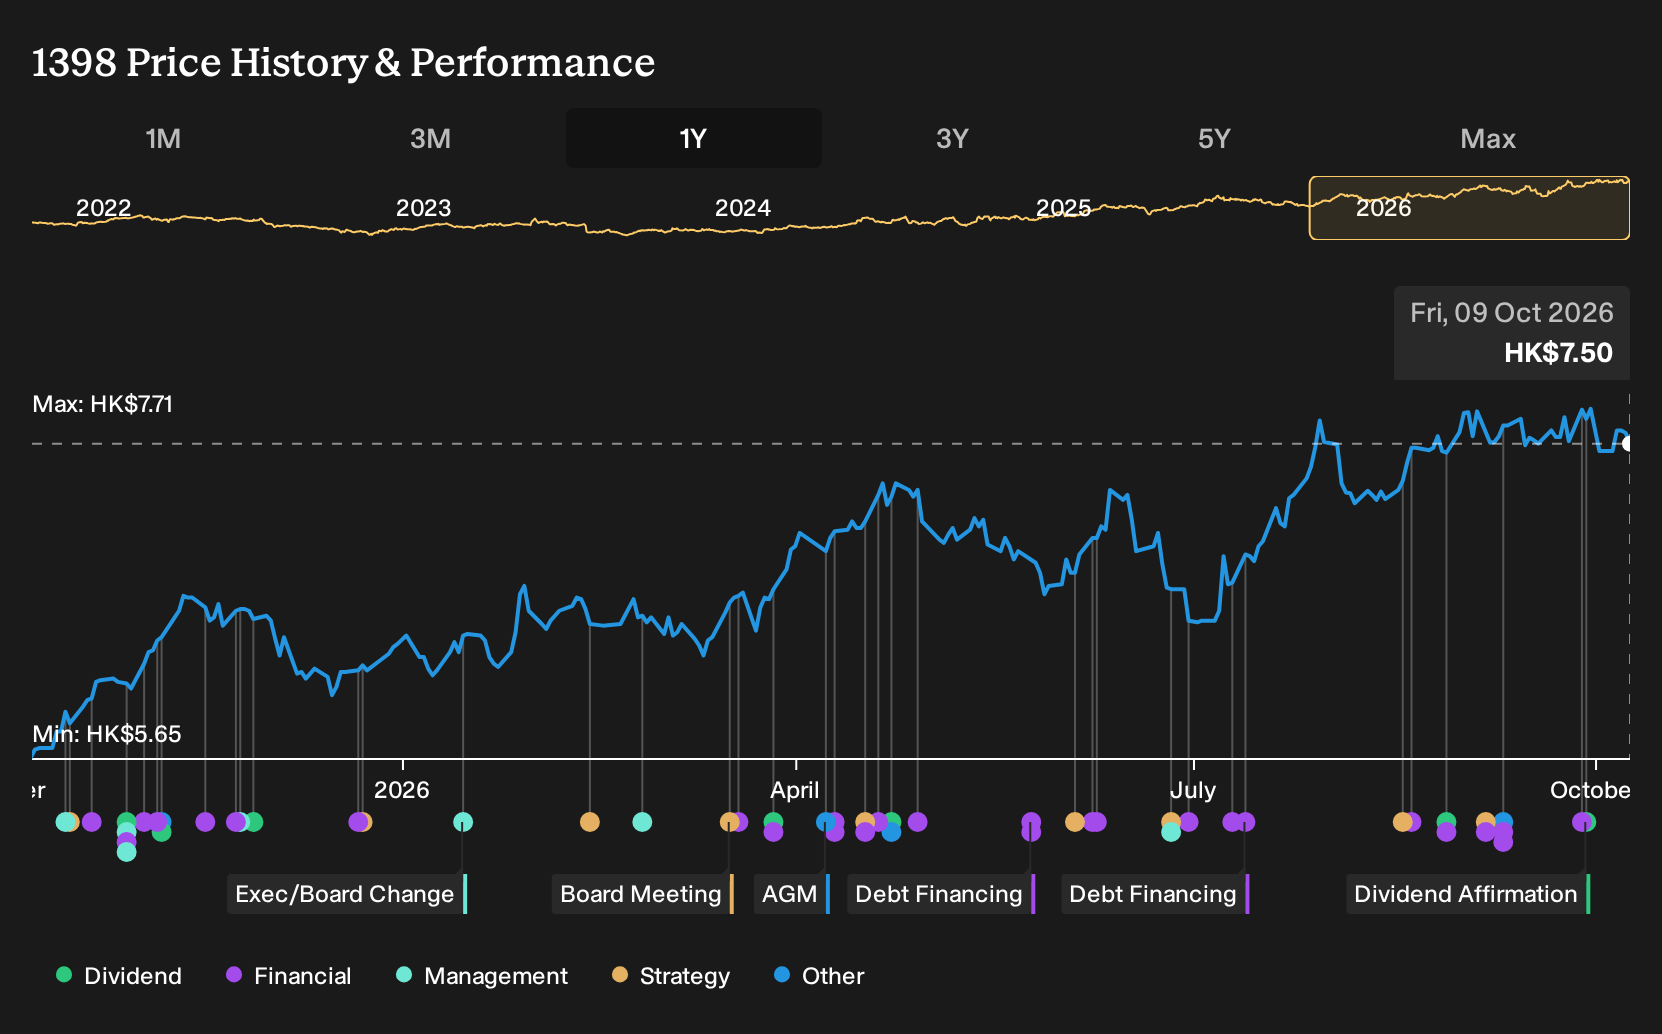
What The Results Changed For Industrial and Commercial Bank of China
The clearest new fact was China’s capital injection plan, with Industrial and Commercial Bank of China preparing to raise up to ¥100b to reinforce core Tier 1 ratios. This supported the cautious focus on policy support and credit risk. At the same time, Q2 2026 revenue of ¥166,459m and net income of ¥82,327m, with net margin slipping to 49.5%, had mixed implications.
The big assumption that really mattered was capital strength. For other banks, you look directly at core equity tier ratios, capital raisings, and net margin trends to assess whether growth stories rest on internally funded expansion or fresh equity support.
What Industrial and Commercial Bank of China’s Price Now Asks You To Believe
Industrial and Commercial Bank of China now trades at HK$7.5. The selected Narrative’s Fair Value sits above the current price and leans on a stronger long-term case for earnings resilience than the market is currently pricing.
The Narrative focuses on global reach, green finance and digital scale. It argues today’s price still does not fully credit the potential earnings power from ICBC’s international network and high digital engagement.
"Expanding global footprint, digital transformation, and green finance leadership are set to drive robust long-term growth and enhance earnings resilience. Strong capital position and dominance in retail and personal banking support high loan capacity, risk resilience, and sustained shareholder returns."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Before The Next Story Makes Headlines
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 25% below our estimate - uses established production to finance drilling that extends nearby mineral resources.
- Company 2 - 35% below our estimate - scales a store and online network after investments in digital integration.
- Company 3 - 30% below our estimate - converts sizeable in-ground inventories into producing reserves while navigating operating risks.
Those are three of them. See the full list of 204 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com