
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
NVR (NVR) Just Raised A Bigger Question For Investors
Why NVR’s recent earnings miss matters for investors
NVR (NVR) has been under pressure after second quarter results fell short on both earnings and revenue, with higher lot costs, land deposit impairments, and high mortgage rates weighing on performance.
NVR’s share price has been sliding, with the stock down 1.7% on a 1-day share price return basis and about 19% year to date. The 1-year total shareholder return has declined roughly 21%, signaling fading momentum as earnings setbacks and high rates reset expectations.
Seize this reset in NVR sentiment to scan a hand picked group of housing related stocks with resilient fundamentals through the list of solid balance sheet and fundamentals (25 results).Bulls point to NVR’s long record and current discount to some analyst targets. Bears focus on earnings misses and estimate cuts. Which story does the latest valuation actually support for new money today?
Most Popular Narrative: 57% Overvalued
NVR last closed at $5,899.16, while the leading narrative fair value sits at $3,758. That gap sets a very different story to the recent pullback and puts the focus squarely on whether the past playbook still fits the current set up.
NVR converts the most capital-intensive, most cyclical, most balance-sheet-fragile activity in U.S. industrial business, residential land development, into a software-like compounder with 30% ROIC and net-cash balance sheets. The mechanism is the Lot Purchase Agreement (LPA) model. NVR pays non-refundable deposits of approximately 10% of finished lot value to third-party developers for the right to take down lots on a quarter-by-quarter basis. The capital that peers tie up in raw land, NVR redeploys into share buybacks. The risk that peers absorb in housing downturns, NVR walks away from by forfeiting deposits.
See why 6 investors see NVR as 57% overvalued.
Result: Fair Value of $3,758 (OVERVALUED)
Still, the NVR story can crack if higher lot costs squeeze that asset light model, or if weaker housing demand makes those land deposits harder to recoup.
Find out about the key risks to this NVR narrative.
Another View: NVR Through Our DCF Lens
The market story around NVR looks very different when you swap the narrative fair value for the SWS DCF model. On this approach, NVR at $5,899.16 screens as undervalued versus an estimated future cash flow value of $7,151.35. This raises a simple question: Is the crowd overreacting to near term earnings noise?
Look into how the SWS DCF model arrives at its fair value.
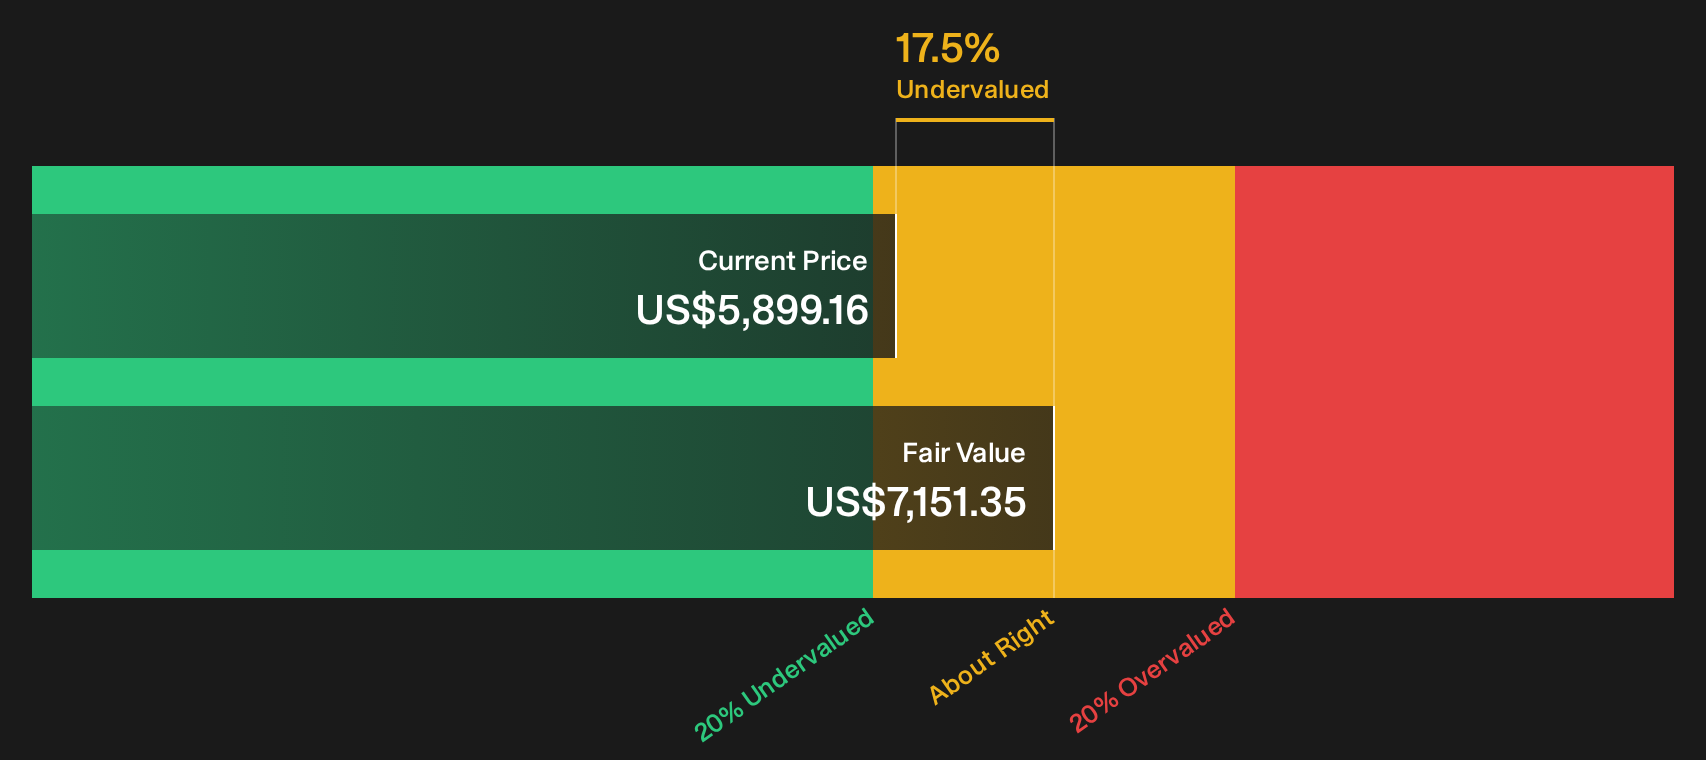
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NVR for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on NVR can be useful if you move quickly and test the assumptions for yourself across both risks and rewards. To see how those competing forces compare in the data, start with the 1 key reward and 1 important warning sign.
Looking for more NVR investment ideas?
If NVR has sharpened your thinking but you do not want to stop at one housing related stock, use the Simply Wall Street Screener to compare fresh ideas side by side.
- Target resilience in tougher markets by scanning a 31 resilient stocks with low risk scores that aims to balance upside potential with steadier risk profiles.
- Hunt for quality at a discount by lining up companies through the 20 high quality undiscovered gems that pair solid fundamentals with limited crowd attention.
- Build income focused watchlists by zeroing in on a 8 dividend fortresses designed for investors who want higher yields backed by financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com