
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Excelerate Energy (EE) Is Getting Attention Today
Excelerate Energy (EE) has drawn fresh attention after securing a contract to convert an LNG carrier into a new Floating Storage and Regasification Unit, and it also reported Q2 revenue growth of 61% year on year.
At a share price of $34.76, Excelerate Energy has seen a 7-day share price return of 6.82%, even though the 30-day share price return declined 9.50% and the 90-day share price return fell 10.87%. At the same time, the 1-year total shareholder return of 30.25% and 3-year total shareholder return of 134.33% point to momentum that has built over a longer horizon as investors weigh the recent LNG contract win and Q2 revenue beat against short term volatility.
Scan beyond Excelerate Energy and line up other LNG and infrastructure players by screening for list of solid balance sheet and fundamentals (25 results) that might handle volatility with similar resilience.
The contract win and sharp Q2 revenue jump have reset expectations for Excelerate Energy. After this latest run and pullback, does the balance of risk and potential upside still skew toward buyers when you line price up against fundamentals?
Most Popular Narrative: 20% Undervalued
Excelerate Energy last closed at $34.76 while the most followed narrative anchors fair value at $43.46. The current quote sits well below that framework and puts the focus squarely on how durable its LNG assets and contracts really are.
The analysts have a consensus price target of $43.46 for Excelerate Energy based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $2.6 billion, earnings will come to $89.7 million, and it would be trading on a PE ratio of 17.7x, assuming you use a discount rate of 7.2%.
See why 12 investors see Excelerate Energy as 20% undervalued.
Result: Fair Value of $43.46 (UNDERVALUED)
Still, Excelerate Energy’s LNG-heavy model faces clear threats if decarbonization policies curb long term gas demand or if big capex projects in markets like Iraq underdeliver.
Find out about the key risks to this Excelerate Energy narrative.
Another View: Excelerate Energy Through Earnings Multiples
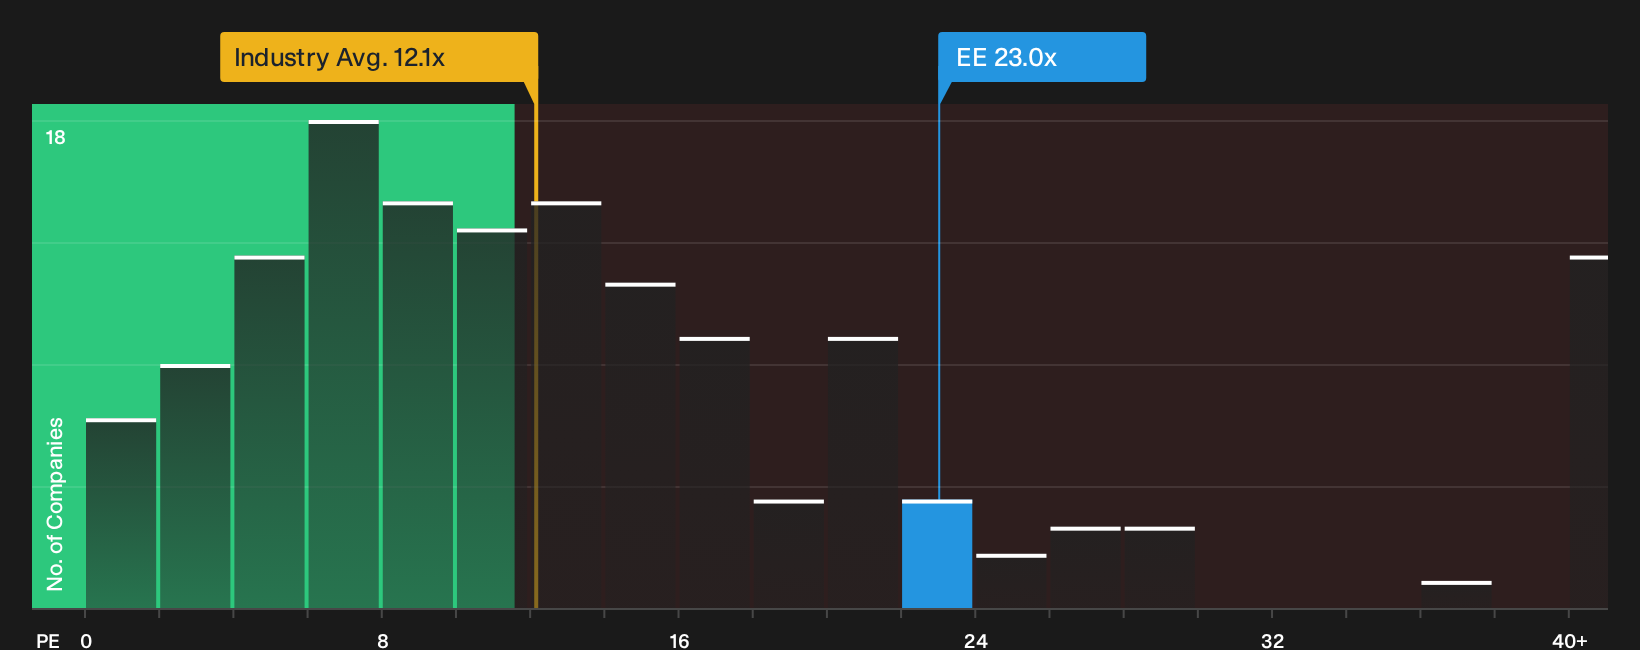
The earlier story on Excelerate Energy leans on analyst fair value of $43.46 and future earnings assumptions. A second lens comes from today’s P/E ratio around 23x, which sits above a fair ratio of 18.5x and well above the US Oil and Gas average of 12.1x and peer average of 10.1x. That gap points to meaningful valuation risk if sentiment cools and the market drifts closer to the fair ratio or sector norms.
Investors weighing Excelerate Energy against other LNG and infrastructure names may want to stress test their thesis using both cash flow narratives and earnings multiples before deciding which signal to trust most when volatility returns. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Excelerate Energy is mixed enough that waiting on a clear signal could mean reacting after the move. Pull up the full breakdown of the 1 or more rewards investors are focusing on and pressure test whether they still stack up for you with 4 key rewards.
Looking for more Excelerate Energy style ideas?
If Excelerate Energy has sharpened your focus on pricing, risk and quality, do not stop with a single ticker. Broadening your watchlist now can surface opportunities before they become crowded trades and help you stress test your thesis across different types of businesses.
- Target potential mispricings early by scanning a curated pool of financially strong companies that trade below internal estimates of worth through the 29 high quality undervalued stocks.
- Strengthen your income stream by reviewing stocks that combine higher yields with balance sheets built to handle shocks using the 8 dividend fortresses.
- Protect your downside by focusing on businesses with resilient financial profiles and lower assessed risk levels in the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com