
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Leonardo DRS (DRS) Expands Allied Defense Reach, Is Its 33% Undervaluation Case Convincing?
Leonardo DRS (DRS) just wrapped final delivery and training for its INOD Block III thermal weapon sights to the Australian Army, while also creating a new UK radar subsidiary. Both moves sharpen its international defense profile.
These contract wins and the new DRS UK unit arrive after a choppy few months for Leonardo DRS, with the share price down about 16% over 90 days but still posting a 3‑year total shareholder return close to 95%. This suggests long term holders have seen strong gains even as near term momentum has cooled.
Scan the defense space for other contractors pushing into allied markets with radar, sensing, and thermal tech by reviewing our curated list of 91 robotics and automation stocks.
Leonardo DRS shares have pulled back even as international contracts and a new UK radar hub widen the business footprint. Are investors rethinking the story, or simply resetting the price tag ahead of the next chapter in the valuation narrative?
Most Popular Narrative: 33% Undervalued
Compared with the latest close at $36.24, the most followed narrative pegs Leonardo DRS at a Fair Value of $53.82. This frames the recent pullback as a valuation gap rather than a business problem.
Leonardo DRS is materially increasing organic investment, with internal R&D and capital expenditures focused on tactical radars, infrared foundry, naval propulsion and capacity expansion. This can position the company to participate in higher value programs over time and support future earnings and margin profiles.
See why 19 investors see Leonardo DRS as 33% undervalued.
Result: Fair Value of $53.82 (UNDERVALUED)
Still, the Leonardo DRS story can wobble if higher R&D and capex fail to translate into fresh awards, or if backlog and return on capital trends weaken again.
Find out about the key risks to this Leonardo DRS narrative.
Another View On Leonardo DRS Valuation
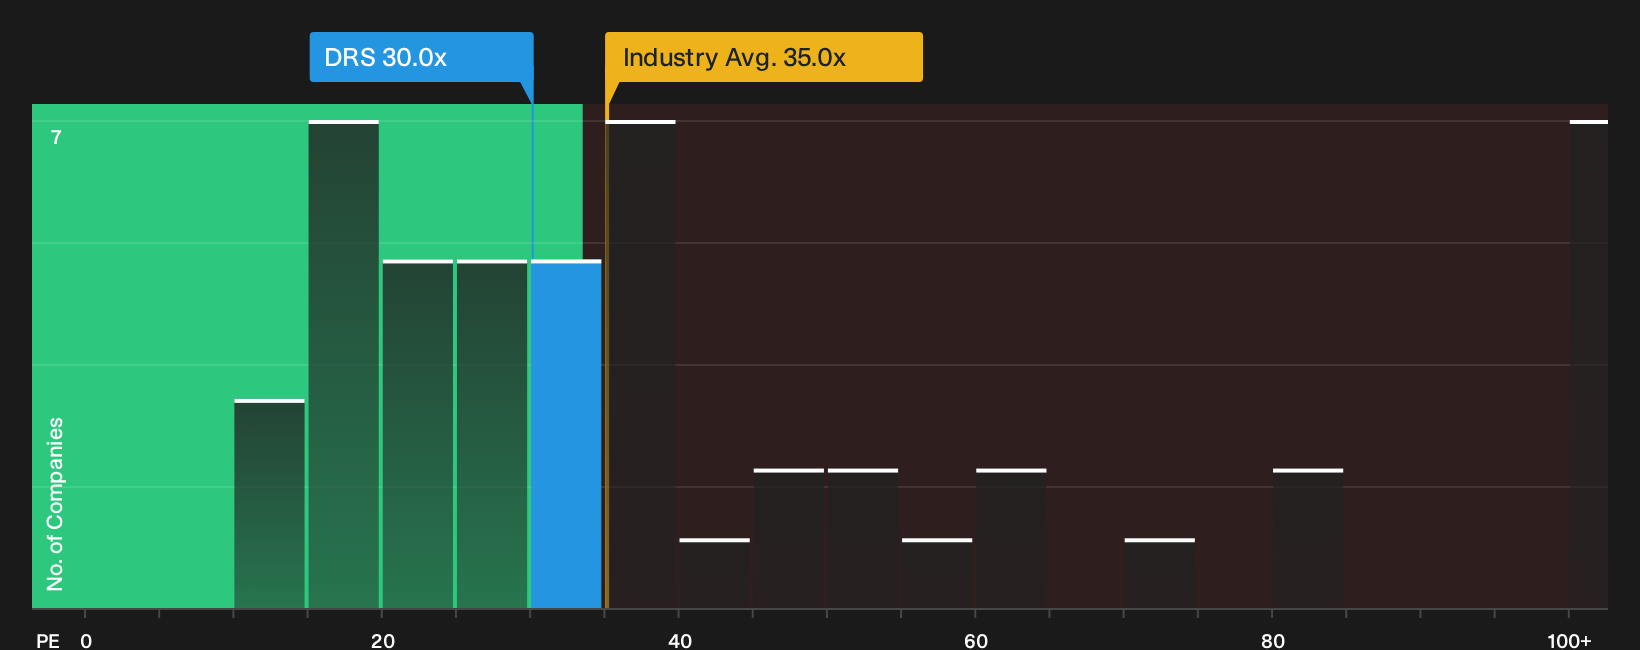
The analyst consensus frames Leonardo DRS as about 33% undervalued using forward earnings and a target P/E of 39.8x. Our fair ratio work paints a cooler picture. At roughly 30x earnings versus a fair ratio of 22.7x and peer average of 24.2x, the shares look expensive instead. Is this a quality premium that persists or a valuation risk that unwinds?
To examine how that gap could narrow in either direction, it helps to see what the numbers indicate about this price in a structured framework, then compare that to your own expectations for revenue growth and margins. See what the numbers say about this price — find out in our valuation breakdown.
Investors cross checking these signals often begin by looking at how P/E compares to the broader Aerospace & Defense group, then work backward to see what earnings path is implied by today’s multiple.
Next Steps
If this mix of enthusiasm and caution around Leonardo DRS feels familiar, let it push you to interrogate the data yourself and act promptly while sentiment is still mixed. To see what optimistic investors are focusing on in the numbers, review the 4 key rewards.
Looking for more investment ideas beyond Leonardo DRS?
If the Leonardo DRS story has sharpened your focus, do not stop here. Broaden your watchlist now or risk missing the next compelling setup.
- Target dependable cash generation and balance sheet resilience by reviewing the list of solid balance sheet and fundamentals (25 results) that meet strict financial strength filters.
- Hunt for potential mispricings by scanning the 29 high quality undervalued stocks that combine quality fundamentals with discounted valuations.
- Zero in on income opportunities by tracking the 8 dividend fortresses built around higher yield payouts with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com