
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Zai Lab (ZLAB) Sets Up ESMO Data Debut, Is The Stock Still Cheap?
ESMO data disclosure puts Zai Lab’s lung cancer program in focus
Zai Lab (ZLAB) is drawing attention after confirming that global Phase 1b/1c data for its antibody drug conjugate zocilurtatug pelitecan in extensive-stage small cell lung cancer will debut at the 2026 ESMO Congress.
The ESMO disclosure sits against a backdrop of strong recent share price momentum for Zai Lab, with the stock up 27.37% over 90 days and a 44.20% year to date share price return. However, the 1 year total shareholder return is still down 17.36%, which suggests investors are reassessing risk and future potential around its pipeline catalysts.
Scan how Zai Lab’s ESMO catalyst fits alongside other high-momentum biotech opportunities by comparing it with 20 high quality undiscovered gems in the same broader space.
Bulls argue Zai Lab’s recent surge corrects an overly discounted pipeline. Bears see a speculative spike on one upcoming ESMO readout. The valuation work now is to test which story current pricing reflects.
Most Popular Narrative: 25% Undervalued
Zai Lab’s most followed valuation narrative pegs fair value at $33.30, above the last close at $24.99. This puts fresh attention on whether current pricing fully reflects its pipeline and China exposure.
Multiple high-potential product launches and label expansions over the next 12-18 months (including VYVGART, bemarituzumab, KarXT, TIVDAK, Tumor Treating Fields), combined with a deep pipeline in oncology and immunology, are expected to significantly increase Zai Lab's addressable market and diversify revenue streams, supporting both top-line growth and future earnings.
See why 12 investors see Zai Lab as 25% undervalued.
Result: Fair Value of $33.30 (UNDERVALUED)
Still, the Zai Lab story hinges on managing heavy reliance on in-licensed assets, as well as regulatory or pricing setbacks in China that could cap margins and delay revenues.
Find out about the key risks to this Zai Lab narrative.
Another View: What Zai Lab’s P/S Ratio Is Telling You
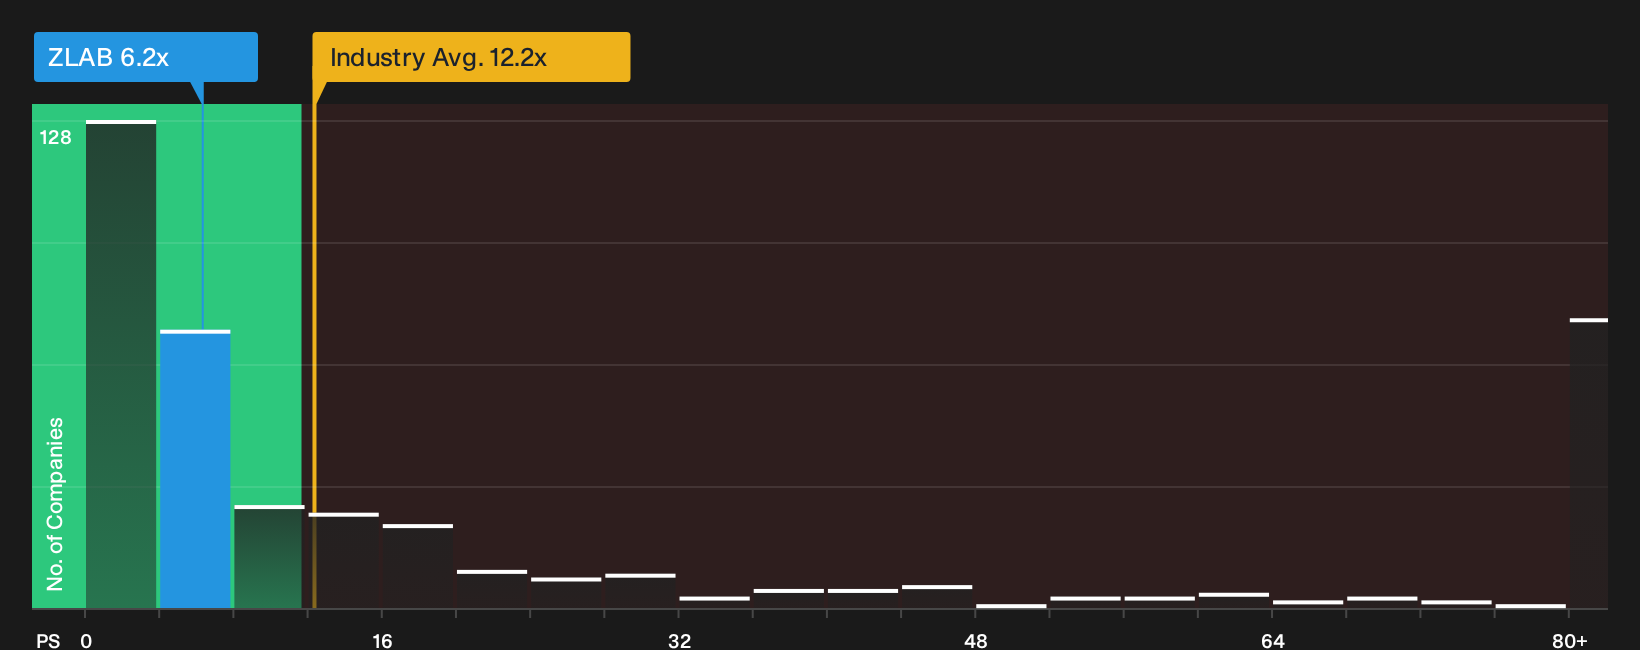
The DCF work points to Zai Lab trading below an estimated fair value, yet the P/S ratio paints a more cautious picture. At 6.2x sales, the stock is cheaper than the wider US Biotechs group on 12.2x, but richer than both peer averages at 5.9x and an SWS fair ratio of 3.4x. That mix of discount and premium raises a simple question for investors: Is this price closer to a safety margin or a crowd getting ahead of itself?
For a closer look at how the current P/S compares to where the market could gravitate over time, and what that means for upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Zai Lab so far. With both concern and optimism in play, move quickly, review the full picture, and weigh 3 key rewards and 1 important warning sign.
Looking for more Zai Lab investment ideas?
If Zai Lab has your attention, do not stop at a single ticker. Cast a wider net and give yourself more options before the next catalyst hits.
- Target resilient compounding potential by scanning companies with strong cash positions and healthy fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality by checking the 29 high quality undervalued stocks that may offer a margin of safety alongside solid business models.
- Prioritize sleep-at-night holdings by focusing on 31 resilient stocks with low risk scores that score well on financial strength and volatility checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com