
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
KBC Ancora (ENXTBR:KBCA) Could Be 18% Overvalued After Full Year Earnings
KBC Ancora (ENXTBR:KBCA) has drawn fresh attention after releasing full year results to June 30, 2026, with net income of €389.37 million compared with €315.43 million a year earlier.
KBC Ancora’s latest figures arrive with the share price at €94.40 and a strong run still intact. The 90 day share price return stands at 11.58% and the year to date gain at 25.37%, supported by a 1 year total shareholder return of 48.32% and a 3 year total shareholder return of 191.83%. This suggests momentum has been building rather than fading, even though the past week’s share price slipped slightly.
Scan beyond KBC Ancora’s strong earnings and momentum to compare it with a curated 178 high quality undervalued stocks that some investors use as a hunting ground for potential mispricings.
After that strong move in KBC Ancora, the live question is where fair value really sits given a share price near €94 and estimates stretching toward €112. How wide is that gap once you unpack the assumptions behind it?
Preferred P/E of 18.7x: Is it justified?
Valuation on KBC Ancora currently hinges on a P/E of 18.7x, which sits above several comparison points and places a clear premium on the shares at €94.40.
The P/E ratio compares the price investors pay today with the earnings the business generates. For a holding entity like KBC Ancora, which owns a stake in KBC Group and reports high quality earnings with forecast profit growth of 11.7% per year, this metric offers a quick way to see how much of that earnings profile is already reflected in the price.
On the fair value side, the SWS model suggests a fair P/E closer to 17.8x. That is lower than the current 18.7x, so the market is assigning a richer multiple than the level this model points to as a potential equilibrium.
Relative to peers, the contrast is even sharper. The same 18.7x P/E is materially higher than both the European banks industry average of 11.6x and the narrower peer average of 7.8x, which indicates investors are paying a substantial premium compared with similar banking stocks.
Explore the SWS fair ratio for KBC Ancora.
Result: Price-to-earnings of 18.7x (OVERVALUED)
Still, the KBC Ancora story can be affected by two pressure points: weaker KBC Group performance and any shift in market appetite for higher P/E premiums.
Find out about the key risks to this KBC Ancora narrative.
Another View on KBC Ancora’s Value
A second lens tells a different story. The SWS DCF model points to a future cash flow value of €77.56 per share, well below KBC Ancora’s current €94.40 level. That gap frames the stock as overvalued on this approach and raises a simple question: Which signal do you trust more, the earnings multiple or the cash flows?
Look into how the SWS DCF model arrives at its fair value.
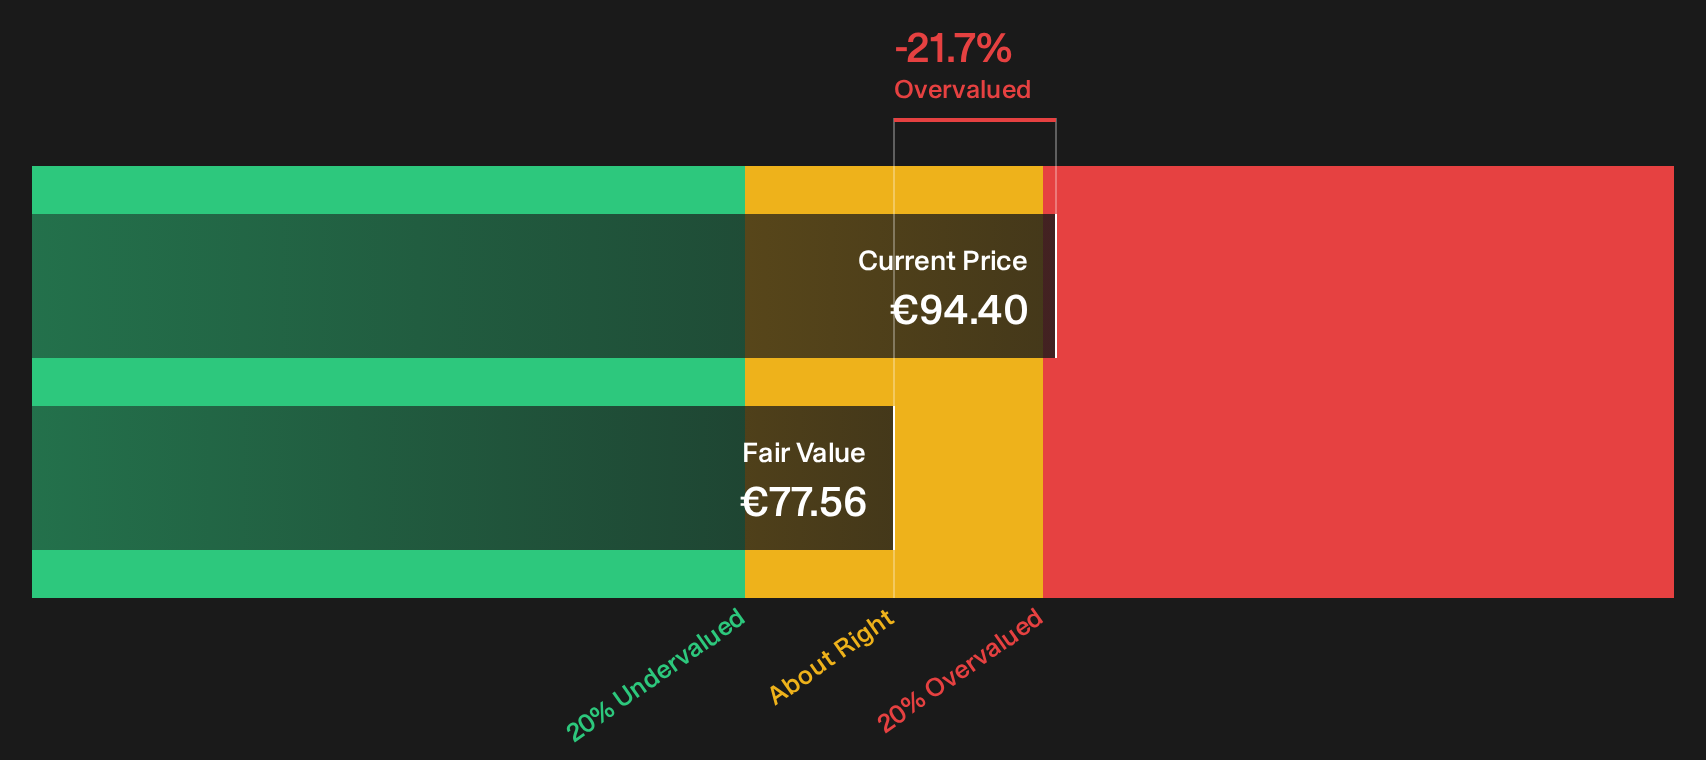
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out KBC Ancora for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 178 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals in the KBC Ancora story so far. If you want a clearer stance, move quickly from headline metrics to the underlying risk and reward balance. To pressure test your own thesis, start with the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond KBC Ancora?
If KBC Ancora has sharpened your focus on valuation, do not stop here. Fresh opportunities often emerge where you are not currently looking.
- Target potential mispricings by scanning a curated 178 high quality undervalued stocks that some investors use when hunting for quality businesses at compressed valuations.
- Strengthen your downside protection by filtering companies with resilient finances through a focused list of solid balance sheet and fundamentals (204 results) that highlights balance sheets built to handle shocks.
- Spot early-stage potential by reviewing a hand picked 618 high quality undiscovered gems packed with companies that have strong fundamentals yet remain off many investors' radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com