
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is QBE Insurance Group (ASX:QBE) Overvalued On Castle Insurance Portfolio Loss?
Castle Insurance portfolio shift puts QBE Insurance Group in focus
QBE Insurance Group (ASX:QBE) has been drawn into the spotlight after Castle Insurance decided to move its national home and contents portfolio underwriting to Canopius from 1 December.
The change means QBE Insurance Australia will no longer underwrite that nationwide book. QBE will, however, remain involved in regional Queensland and Norfolk Island through the Sure Insurance brand, a split that raises fresh questions about future underwriting volumes and related income streams.
Investors have pushed QBE Insurance Group’s share price up to A$25.15 after a 3.20% 1 day share price return and a 14.06% 30 day share price return. The year to date share price return of 26.96% and 5 year total shareholder return of 162.54% point to momentum that has extended well beyond this latest Castle Insurance shift.
Scan how QBE Insurance Group compares on underwriting strength and balance sheet resilience when measured against a curated list of solid balance sheet and fundamentals (12 results).
QBE Insurance Group has just logged a strong run and absorbed a meaningful underwriting shift from Castle Insurance. The next issue is simple: Do the current valuation numbers still point to upside, or has most of it already played out?
Most Popular Narrative: 3% Overvalued
The most followed valuation narrative puts QBE Insurance Group’s fair value at A$24.47, slightly below the last close of A$25.15. That small gap leaves the share price sitting just above what that framework treats as a balanced risk and reward line.
QBE's strong capital position, recent AA credit upgrades, and disciplined risk management give it resilience against industry shocks, preserve stable dividend payouts, and provide optionality to pursue strategic acquisitions or invest in new growth segments, underpinning attractive long-term returns on equity and earnings growth.
See why 57 investors see QBE Insurance Group as 3% overvalued.
Result: Fair Value of A$24.47 (OVERVALUED)
Still, the QBE Insurance Group story can change quickly if soft premium rates collide with higher claims costs, or if large loss volatility flares up again.
Find out about the key risks to this QBE Insurance Group narrative.
Another View: QBE Insurance Group through a cash flow lens
Analysts view QBE Insurance Group as slightly overvalued at A$24.47 on their price target framework, yet the SWS DCF model presents a very different picture. On that cash flow view, A$25.15 is roughly 50% below an estimated future cash flow value of A$49.94, which highlights a markedly different balance of risk. Which framework do you trust more when the gap is this wide?
Look into how the SWS DCF model arrives at its fair value.
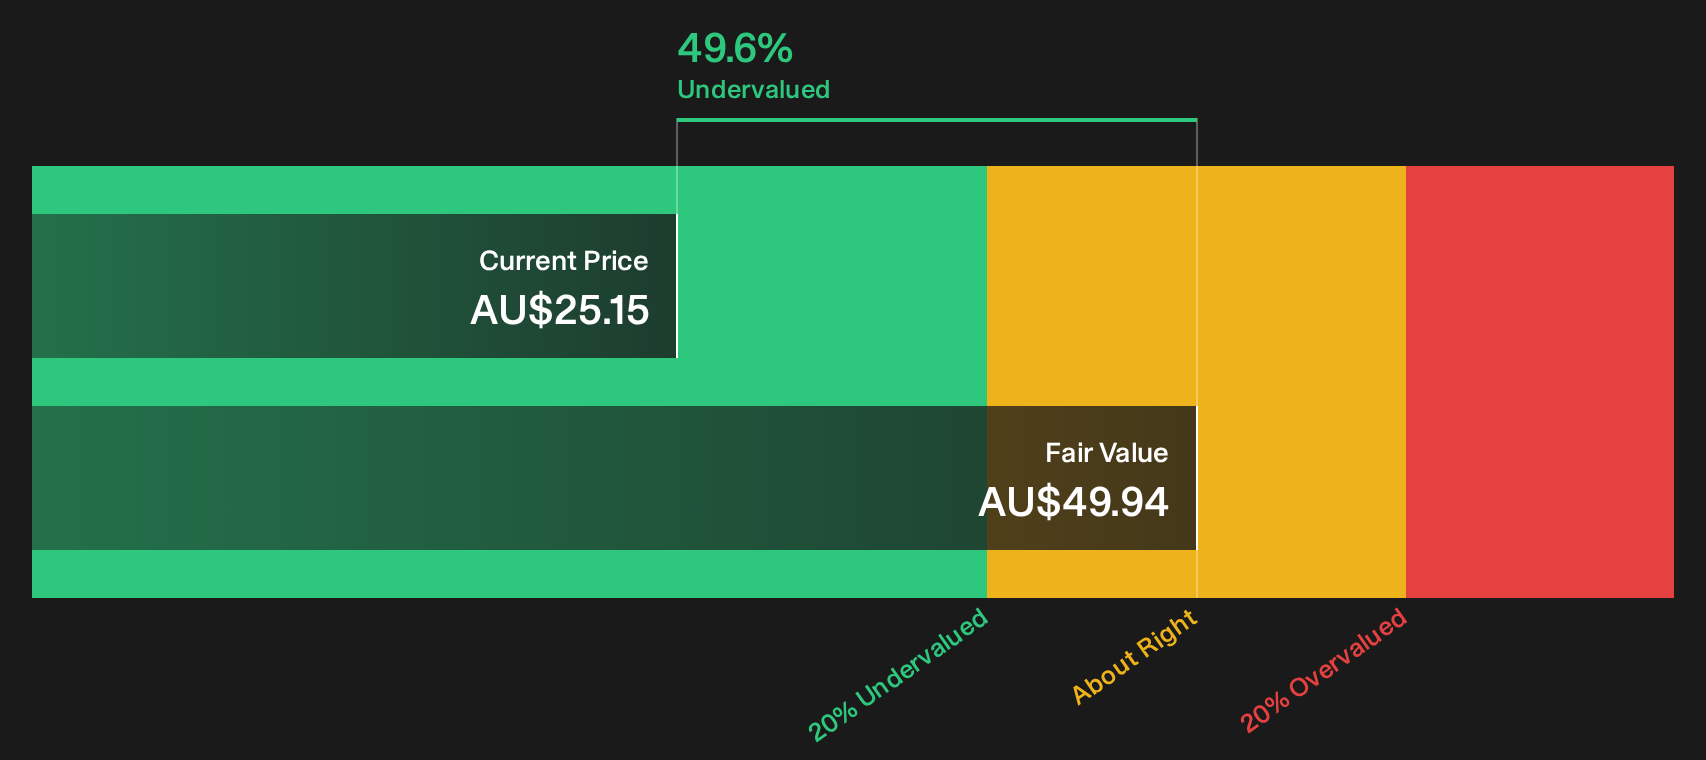
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out QBE Insurance Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on QBE Insurance Group can either push you to sit on the fence or push you to check the data yourself and move fast. To weigh the upside against what could go wrong, start with the 2 key rewards and 2 important warning signs.
Looking for more QBE Insurance Group sized ideas?
If QBE Insurance Group has sharpened your focus, use this momentum and hunt for other opportunities before they move out of easy reach.
- Target dependable income streams by scanning a shortlist of income heavyweights, built around 6 dividend fortresses.
- Hunt for mispriced quality by reviewing a concentrated set of potential value candidates with the 4 high quality undervalued stocks.
- Prioritise resilience first by filtering for companies with measured risk profiles through the 7 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com