
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is National Bank Holdings (NBHC) Still Undervalued As Earnings Guidance Cuts Expectations?
National Bank Holdings (NBHC) moved back into focus after fresh guidance signalled an expected reduction in after tax earnings of about $32.0 million to $34.0 million, or $0.72 to $0.76 per diluted share.
Recent guidance landed on a stock that was already cooling, with the share price down about 9.2% over the past month and roughly 15.1% over the past quarter. However, National Bank Holdings still shows a 7.3% 1 year total shareholder return and about 39.2% over three years, suggesting shorter term momentum is fading as investors reassess earnings risk.
Spot opportunities that may appear more resilient than National Bank Holdings by scanning our handpicked 31 resilient stocks with low risk scores.National Bank Holdings has now seen expectations reset and the share price pull back, which raises a simple question for investors. Is the meaningful upside still in front of the stock or already in the rear-view mirror as valuation comes into focus?
Most Popular Narrative: 18% Undervalued
National Bank Holdings most followed valuation storyline now points to a fair value of $46 per share versus the last close at $37.93. This leaves the guidance cut sitting inside a wider debate about whether the discount reflects temporary earnings pressure or something more structural.
The main thing that has to go right is that National Bank Holdings converts its loan growth, Vista integration, and digital investments like 2UniFi into durable, high quality earnings without eroding its conservative credit profile or near 4% net interest margin.
See why 4 investors see National Bank Holdings as 18% undervalued.
Result: Fair Value of $46 (UNDERVALUED)
Still, concentration in trucking, agriculture and commercial real estate, along with 2UniFi’s earnings drag, could quickly challenge the current valuation story for National Bank Holdings.
Find out about the key risks to this National Bank Holdings narrative.
Another View: What The P/E Ratio Says About National Bank Holdings
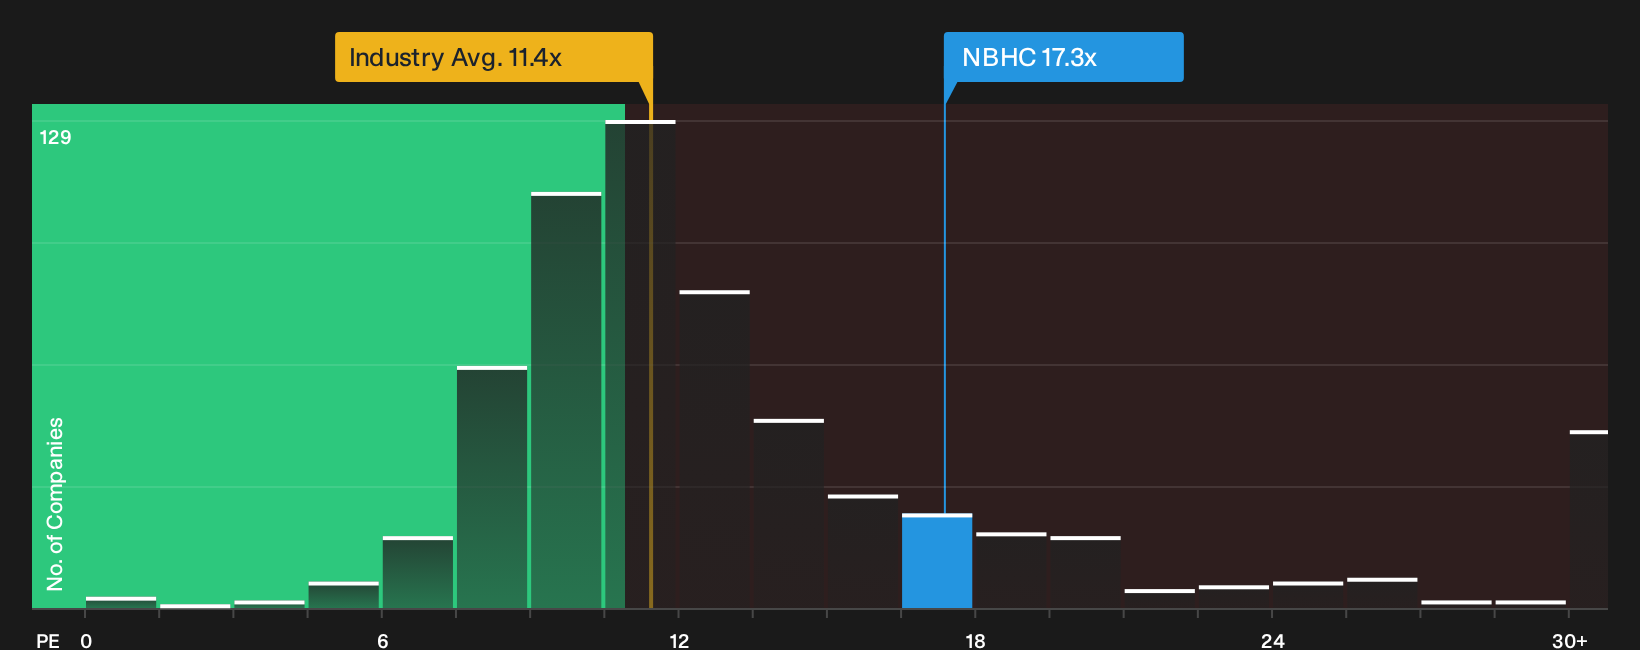
The first valuation story presents National Bank Holdings as meaningfully undervalued, yet the P/E ratio tells a tougher story. NBHC trades on 17.3x earnings compared with 12.4x for peers and 11.4x for the wider US Banks group, while the fair ratio sits at 16.4x. That premium suggests the market already prices in a fair amount of good news, so the key question is whether investors are being compensated sufficiently for that additional valuation risk.
For a closer look at how the current earnings multiple compares with what the numbers imply over time, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around National Bank Holdings can pull you in both directions, so move quickly and pressure test the story against the underlying numbers and narrative. To weigh the trade off between the concerns and the potential upside, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond National Bank Holdings?
If National Bank Holdings is on your radar, consider rounding out your watchlist with a few contrasting ideas that could balance different return drivers, risk profiles, and income needs.
- Explore potential resilient compounding by scanning a curated pool of quality businesses through the 29 high quality undervalued stocks.
- Review companies that combine higher yields with staying power using the 8 dividend fortresses.
- Focus on financially robust businesses to help manage portfolio volatility via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com