
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
App Recall Might Change The Case For Investing In Tandem Diabetes Care (TNDM)
- Tandem Diabetes Care has initiated a voluntary Class II recall of its iOS t:slim mobile app version 2.13 after a pairing issue with Abbott’s FreeStyle Libre 3 Plus CGM blocked automated insulin delivery and forced affected users into manual pump operation.
- The recall, which currently involves 177 beta users across US nationwide distribution, highlights how software reliability in closed-loop systems can directly affect Tandem Diabetes Care’s product execution, regulatory workload, and support costs.
- We now assess how this mobile app recall affecting closed-loop functionality could reshape Tandem Diabetes Care’s broader investment narrative.
Tandem Diabetes Care Investment Narrative Recap
To own Tandem Diabetes Care, you need to believe in growing adoption of its automated insulin delivery ecosystem, from t:slim X2 to Mobi, across both US and international markets. The near term focus is on executing cleanly as the business works toward profitability targets, while keeping price sensitive on a P/S of about 1.1x.
The recent Class II recall looks operationally contained, with 177 beta users and an early release iOS build. It still speaks directly to Tandem Diabetes Care’s biggest near term swing factor: reliable software driven closed loop performance, without safety events that inflate support and regulatory burdens, and without distracting management from commercial rollouts.
The Tandem Mobi international launch into 12 countries sits closest to this recall story. Both depend on tightly integrated pump, algorithm, and sensor software actually working in the wild, not just in trials. Investors are watching how cleanly Mobi is deployed, how quickly clinicians adopt it, and whether support overhead stays manageable.
If Tandem Diabetes Care executes smoothly on Mobi abroad, it strengthens key catalysts such as higher margin recurring supplies and better pricing on direct international sales. Any recurring software issues similar to the iOS 2.13 pairing bug would cut the other way and raise questions on operational discipline just as the company targets improved earnings.
Tandem Diabetes Care's current analyst narrative points to revenue of US$1.4b and earnings of US$63.4 million by 2029, built on an assumed 10.3% yearly revenue growth rate and an earnings swing of about US$158 million from a loss of US$94.5 million today to that projected profit.
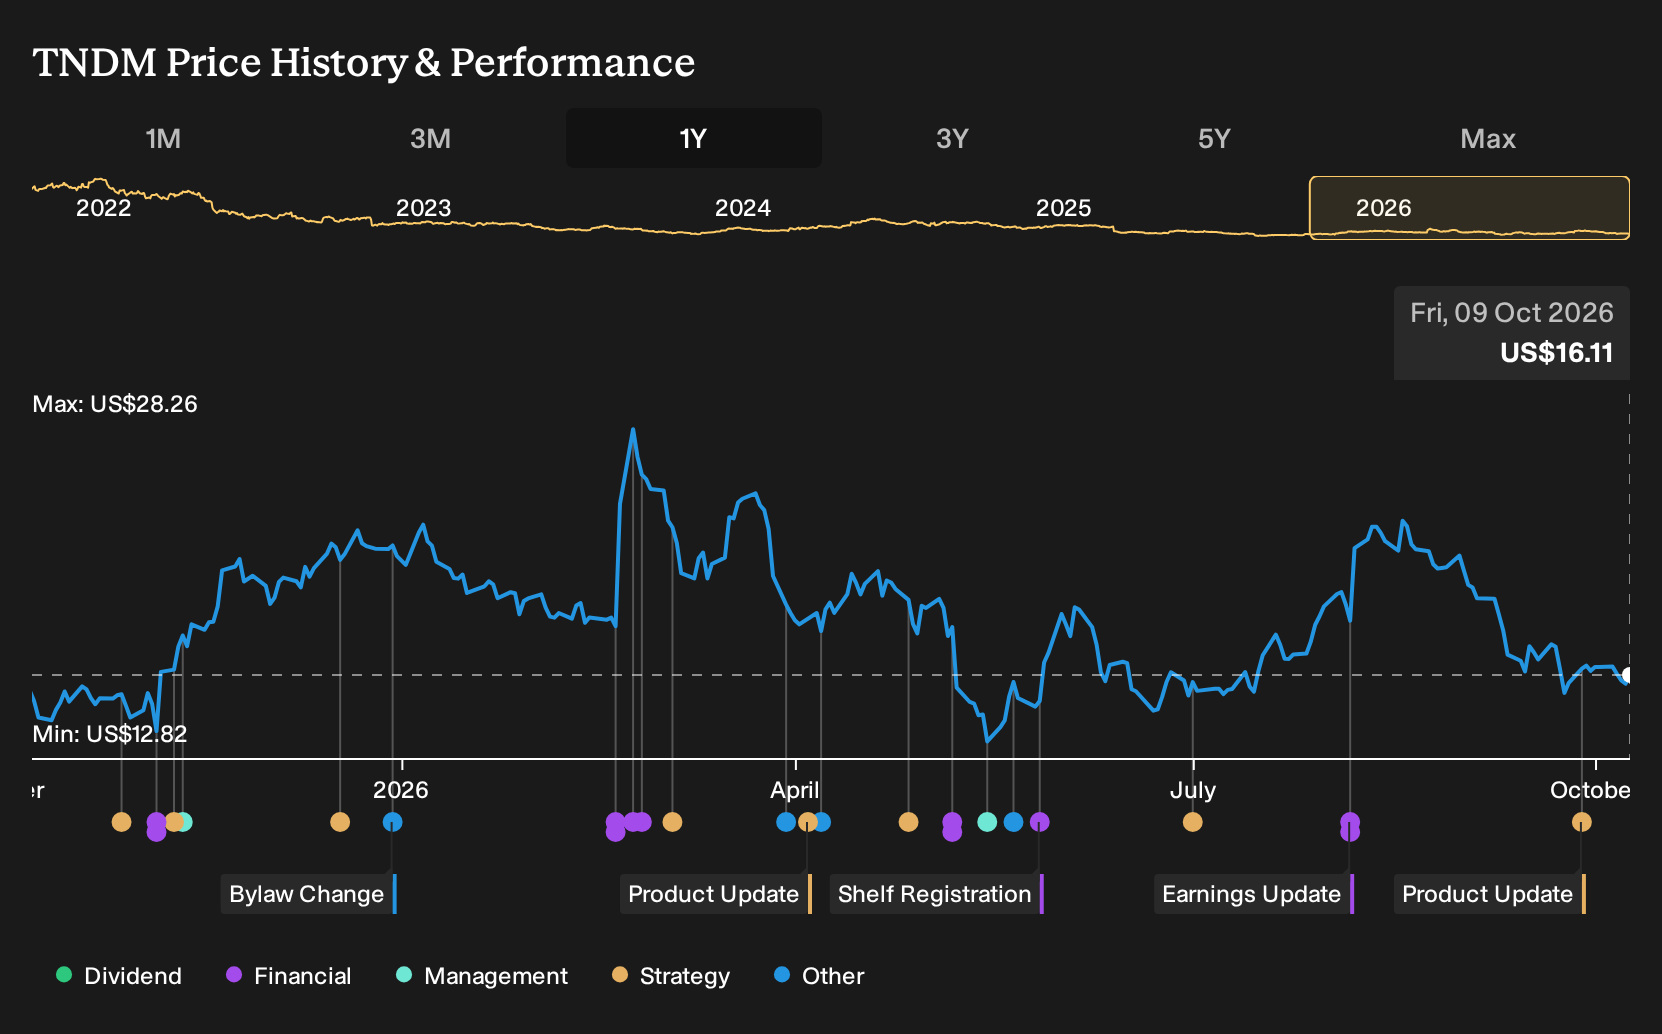
Uncover how Tandem Diabetes Care's fair value signals a 81% potential upside to its current price that could narrow quickly as sentiment around Tandem Diabetes Care shifts.
Exploring Other Perspectives
One alternate view on Tandem Diabetes Care leans heavily on pharmacy channel upside. The most optimistic analysts were modeling about US$1.6b of revenue and US$170.9 million of earnings by 2029, versus consensus at US$1.4b and US$63.4 million. After a software recall like this, those pharmacy driven assumptions may look very different.
Explore 2 other Tandem Diabetes Care fair value estimates, including one that suggests potential upside of as much as 360% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Tandem Diabetes Care research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Tandem Diabetes Care. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tandem Diabetes Care's overall financial health at a glance.
Looking For More Ideas Beyond Tandem Diabetes Care?
If the Tandem Diabetes Care story has you thinking about how to balance risk, quality, and income in your portfolio, it can help to line it up against other opportunities using the Simply Wall St Screener.
- For investors who care most about quality at a reasonable price, compare Tandem Diabetes Care against a wider set of companies screened as 29 high quality undervalued stocks.
- If capital preservation sits high on your list, you can cross check your holdings against our 31 resilient stocks with low risk scores to see which businesses score well on resilience.
- For those hunting for sturdier balance sheets and cleaner fundamentals, broaden your watchlist with a list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com