
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Ambarella (AMBA) Draws Fresh Attention, Is It A Bargain?
Ambarella stock reaction and the recent price context
Ambarella (AMBA) has drawn fresh attention after its latest trading session, with shares closing at $67.43 as of 2 October 2026. The move comes against a backdrop of mixed recent returns and ongoing interest in its AI-focused chip portfolio.
The sharp 7.22% 1 day share price return contrasts with weaker recent momentum. The 90 day share price return is down 6.35% and the year to date share price return is down 10.28%, while the 3 year total shareholder return of 27.59% points to a mixed longer term record.
Scan how Ambarella stacks up against other chip players by reviewing a curated set of 92 AI infrastructure stocks that are poised to benefit from rising demand for AI-focused hardware.
A sharp one day jump, a weaker year to date record, and ongoing losses on the income line put Ambarella in a tricky spot. Does that mix still leave enough upside in the valuation to justify the risk buyers take from here?
Most Popular Narrative: 24.5% Undervalued
Ambarella's most followed narrative pegs fair value at $89.36, above the last close at $67.43, which puts the current share price at a clear discount and focuses attention on how its edge AI positioning might eventually translate into stronger financials.
Sharply increasing demand for AI-powered edge devices, including portable video, robotics (notably aerial drones), and edge infrastructure, has led to a rapid expansion of Ambarella's addressable markets, as evidenced by record edge AI revenue and multiple recent, diversified design wins. This is catalyzing strong, sustained revenue growth and positions Ambarella to benefit further as additional vertical applications for edge AI proliferate.
See why 41 investors see Ambarella as 25% undervalued.
Result: Fair Value of $89.36 (UNDERVALUED)
Still, heavy reliance on volatile IoT demand and concentrated exposure to key Asian partners could quickly undermine the bullish Ambarella valuation story if conditions worsen.
Find out about the key risks to this Ambarella narrative.
Another View on Ambarella’s valuation
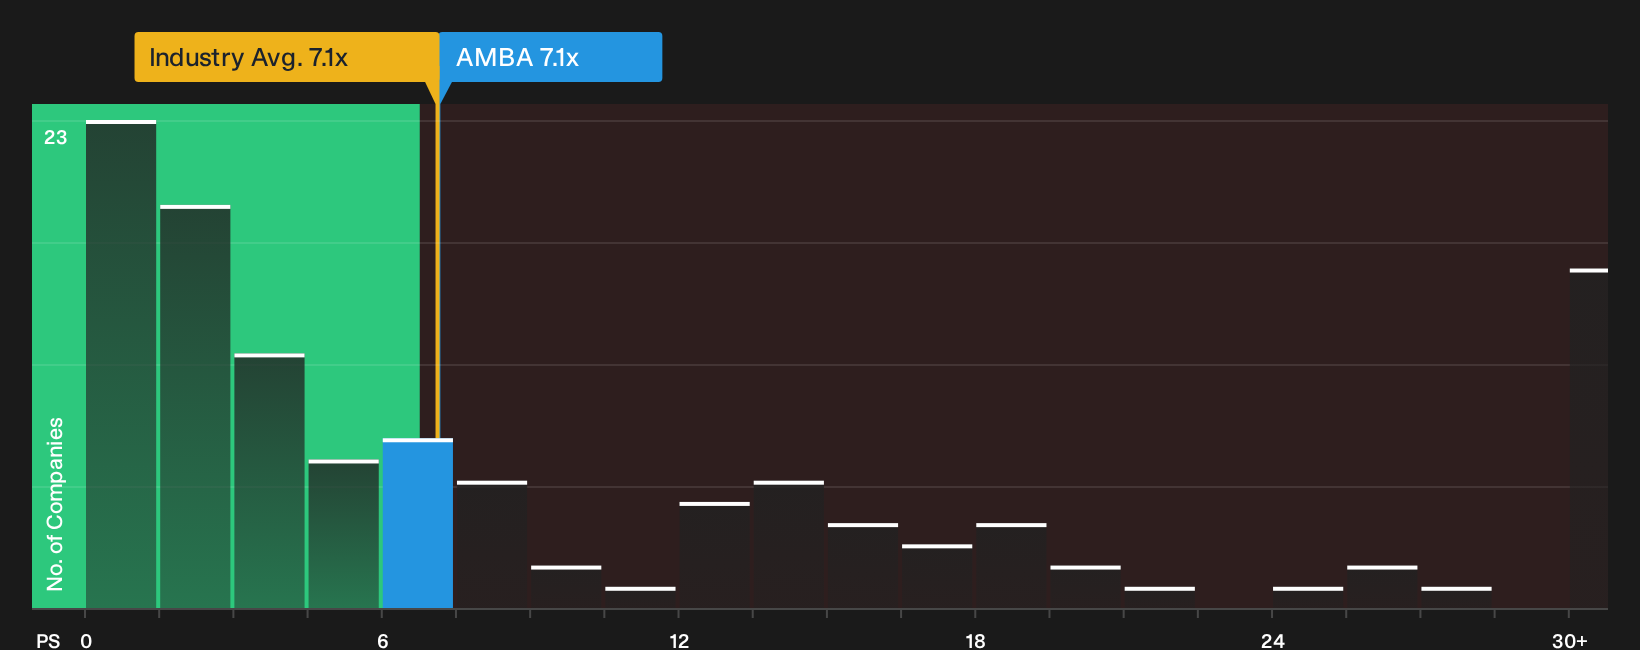
The popular story frames Ambarella as 24.5% undervalued against a fair value of $89.36. A different lens uses revenue multiples. On this measure, the stock trades on a P/S of 7.1x, while the fair ratio points to 5.6x and peers average 4.2x. That gap suggests investors are still paying up. Does that premium feel justified for a business that is unprofitable today?
To see how that pricing stacks up against detailed ratio work, review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Ambarella's valuation and sentiment do not need to leave you stuck on the sidelines. Move quickly, review the data for yourself, and weigh both the potential upside and the vulnerabilities using the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Ambarella?
Do not stop at Ambarella. Broaden your watchlist with fresh ideas that match your risk tolerance, income needs, and quality preferences using focused screeners.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (25 results) that prioritises financial strength and cleaner fundamentals.
- Hunt for mispriced quality with a 29 high quality undervalued stocks that filters for strong businesses trading below their assessed worth.
- Build a defensive core by reviewing a 31 resilient stocks with low risk scores that highlights companies with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com