
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hawaiian Electric Industries (HE) Could Be 3% Undervalued Following Wildfire Liability Relief
Hawaiian Electric Industries (HE) has drawn fresh attention after recent share price weakness, with the stock closing at US$8.76. Investors are reassessing this utility-focused business and its longer term risk and return profile.
Over the past few months, Hawaiian Electric Industries has seen selling pressure build, with the share price return down 15.6% over 30 days and 35.1% over 90 days, while the 1 year total shareholder return has declined 19.6%. This points to fading momentum as investors reassess risk.
Scan beyond Hawaiian Electric Industries and size up other utility and infrastructure players facing similar pressure with our curated list of 43 power grid technology and infrastructure stocks.
For Hawaiian Electric Industries at US$8.76 after a steep slide, the tension is simple. Does waiting for even cheaper levels make sense, or does today’s reset already reflect what you are being paid for the risk?
Most Popular Narrative: 3% Undervalued
At a last close of $8.76 versus a narrative fair value of $9.06, Hawaiian Electric Industries is framed as modestly undervalued, with that gap hinging on how wildfire risk, regulation, and future earnings interact over time.
Recent Hawaii legislation enabling wildfire liability caps, state funding for settlements, and securitization of wildfire safety investments significantly reduces legal and financial risk exposure while supporting large-scale infrastructure upgrades. This is likely to stabilize earnings and improve net margins.
Progress in implementing enhanced wildfire safety measures, supported by dedicated funding mechanisms, reduces future risk of catastrophic losses and strengthens public trust and regulatory goodwill. This may result in more favorable treatment of capital expenditures in rate base calculations, positively impacting future regulated earnings and revenue stability.
See why 16 investors see Hawaiian Electric Industries as 3% undervalued.
Result: Fair Value of $9.06 (UNDERVALUED)
Still, the wildfire liabilities and rising mitigation and insurance costs remain key swing factors that could upset the current Hawaiian Electric Industries valuation story.
Find out about the key risks to this Hawaiian Electric Industries narrative.
Another View: DCF Paints A Harsher Picture For Hawaiian Electric Industries
The narrative fair value of $9.06 suggests Hawaiian Electric Industries is slightly undervalued. A different lens tells a tougher story. The SWS DCF model estimates future cash flows support a value of about $2.88 per share, far below the current $8.76 price.
This gap implies that if cash generation ends up closer to the DCF assumptions than to analyst forecasts, investors are paying a much richer price for each future dollar of cash flow. It raises a simple question: Which yardstick do you trust more, the sentiment in earnings multiples or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
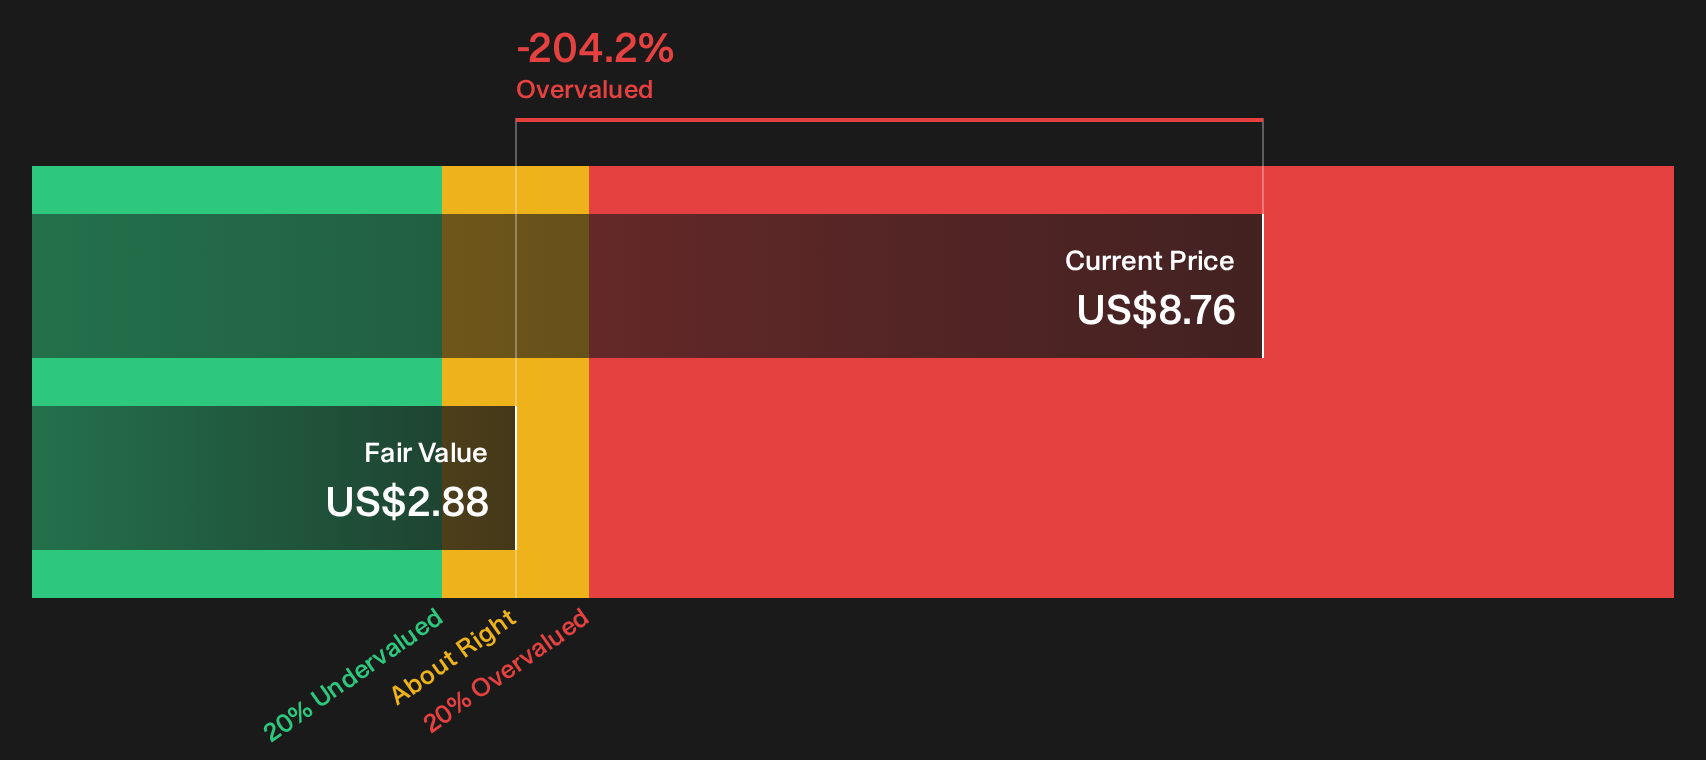
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hawaiian Electric Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages run through Hawaiian Electric Industries right now, with real risks on one side and genuine upside arguments on the other. Act while sentiment is divided by weighing both data points and narrative drivers, then use the 3 key rewards and 2 important warning signs.
Hunting For More Ideas Beyond Hawaiian Electric Industries?
If you stop with Hawaiian Electric Industries, you risk missing other opportunities that might line up even better with your goals and tolerance for risk.
- Target resilient cash generators by scanning a 31 resilient stocks with low risk scores that focuses on businesses with steadier profiles and lower reported risk scores.
- Spot potential bargains early by running through a 20 high quality undiscovered gems packed with stocks that pair solid fundamentals with relatively limited attention.
- Build a sturdier income base by reviewing a 8 dividend fortresses centered on companies offering higher yields with a focus on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com