
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why American Tower Stock Is Moving With The Tower REIT Rally
- American Tower benefited from a past sector-wide rally in communications infrastructure REITs, as investors focused on tower and data center assets tied to long term wireless demand.
- The move highlighted how demand for ground based infrastructure, including potential new deployments to support hybrid satellite and terrestrial networks, can influence American Tower's leasing outlook.
- We will now look at how American Tower's investment narrative lines up with rising interest in tower assets for hybrid wireless buildouts.
Scan beyond American Tower and see how other tower and infrastructure REITs line up for wireless buildouts with the curated 92 AI infrastructure stocks.
American Tower Investment Narrative Recap
To own American Tower, you need to believe that carriers and new entrants keep leaning on its tower and data center footprint to handle heavier wireless and cloud traffic. The key near term swing factor is how quickly leasing on existing sites converts into tenant billings and funds from operations as carrier spending plans turn into amendments and colocations. The SpaceX and Starlink Mobile push into hybrid satellite and terrestrial service could support that thesis if it leads to incremental ground based deployments, but the impact is still developing rather than clearly visible.
The biggest operational risk remains on the financing and churn side. Higher borrowing costs and debt that is not well covered by operating cash flow can cap how aggressively American Tower reinvests or repurchases shares, even with a REIT scale market cap of about US$84.9b. On the revenue line, churn events like the DISH exit or pressure in Brazil show how quickly carrier consolidation, spectrum re farming or weaker 5G densification can offset new leasing and weigh on adjusted EBITDA and AFFO per share.
The most relevant backdrop for this wireless news is the current debate heading into American Tower’s Q3 2026 earnings on 27 October. Expectations for funds from operations to match the prior year quarter put execution firmly under the microscope. That is especially true after the share price pullback and the recent sector wide rally in tower and infrastructure REITs. Investors are weighing whether concerns about slower carrier spending and higher rates line up with the business that American Tower is actually reporting.
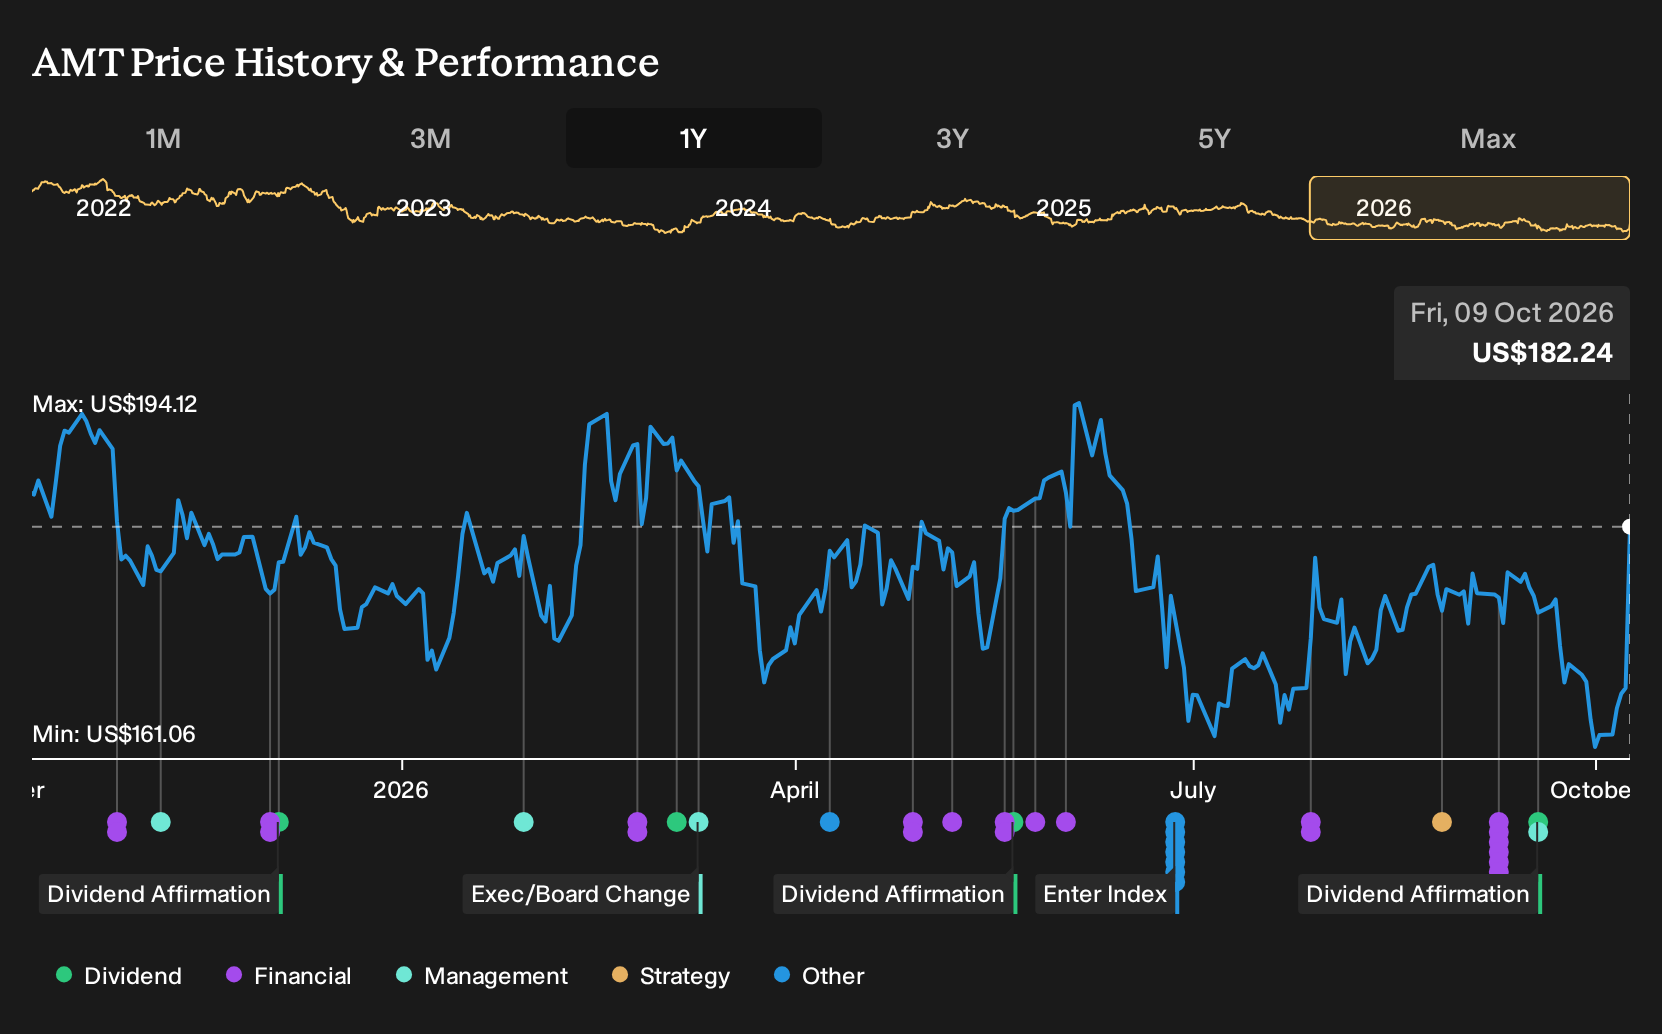
DCF work indicating intrinsic value above the roughly US$182 share price, together with a P/E of 25x versus an estimated fair P/E of 34.2x, means the market is already discounting a lot of that uncertainty into the stock. The SpaceX spectrum deal feeds directly into this set up. A credible hybrid satellite and terrestrial rollout would likely require meaningful ground infrastructure, which could support tower amendments and new leases if American Tower secures that traffic. Execution on those opportunities, while managing churn, interest costs and CoreSite data center demand, is what will matter most over the next few quarters.
American Tower's narrative projects US$12.5b revenue and US$3.8b earnings by 2029. This is based on analysts estimating 4.4% yearly revenue growth and a US$0.4b earnings increase from US$3.4b today.
Uncover why American Tower's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$216 and US$298 per share, which suggests a wide range of outcomes for American Tower. These retail views pre date the SpaceX spectrum deal. You can weigh them against risks around carrier spending, interest costs and CoreSite demand before forming your own view.
Explore 2 other American Tower fair value estimates, including one that suggests it could be worth just $215.70.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own research and judgment.
- A great starting point for your American Tower research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for American Tower. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Tower's overall financial health at a glance.
Looking For More Investment Ideas Beyond American Tower?
If the American Tower story has you thinking more broadly about where to put fresh capital to work, it can help to scan a wider field of candidates that fit different risk and income profiles.
- For readers who want potential mispricing paired with business quality, start with companies that screen as both attractively valued and financially robust through the 29 high quality undervalued stocks.
- If capital preservation and steadier fundamentals sit higher on your list, filter for businesses with resilient balance sheets using the list of solid balance sheet and fundamentals (25 results).
- For those aiming to build a portfolio with stronger income characteristics, focus on issuers offering higher yields with support from underlying cash flows through the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com