
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Raised 2026 Guidance At Insight Enterprises (NSIT) Has Changed Its Investment Story
- Insight Enterprises reported strong Q2 2026 results, with significant growth in infrastructure hardware revenue, cloud gross profit, and core services, and raised its 2026 guidance for gross profit growth to a range of 8% to 10% and adjusted diluted EPS to a range of US$12.20 to US$12.70.
- The new three year One Insight Plan, which targets organic expansion and AI driven efficiency gains under a unified operating model, signals management’s focus on scaling AI ready infrastructure, cloud, and services rather than relying on broad top line acceleration.
- We will examine how Insight Enterprises' investment narrative is reshaped by the higher 2026 profit guidance tied to AI focused solutions.
Compare Insight Enterprises' AI driven momentum with a curated group of infrastructure enablers powering similar trends in 92 AI infrastructure stocks.
Insight Enterprises Investment Narrative Recap
To own Insight Enterprises, you need to believe its pivot toward AI ready infrastructure, cloud and services can keep offsetting softer enterprise hardware cycles and vendor program changes. The raised 2026 profit outlook signals management sees enough demand and internal efficiency potential to support that story, without needing outsized net sales growth.
The key near term swing factor is whether large clients keep funding AI and cloud projects at a pace that supports higher margin solutions and the One Insight operating model. The biggest risk remains that enterprise decision cycles slow again while vendor repricing or program shifts pressure gross margin and blunt the impact of recent efficiency gains.
The One Insight Plan is the announcement that matters most here. Management is tying a unified operating structure and AI driven productivity tools directly to higher 2026 gross profit and adjusted EPS guidance, which makes execution on that model central to how you think about Insight Enterprises over the next few years.
If the new framework really lets Insight push more AI focused infrastructure, managed security and cloud work through a leaner cost base, then operating leverage becomes a core catalyst, not just a hope. If integration drags, or if one off items and vendor changes keep disrupting margins, the case for sustained earnings expansion looks less straightforward.
Insight Enterprises' current analyst storyline points to revenues of US$9.9b and earnings of US$392.5m by 2029, based on assumed yearly top line expansion of 4.9% and an earnings increase of about US$182m from US$210.5m today.
Uncover why Insight Enterprises' fair value indicates alignment with its current price.
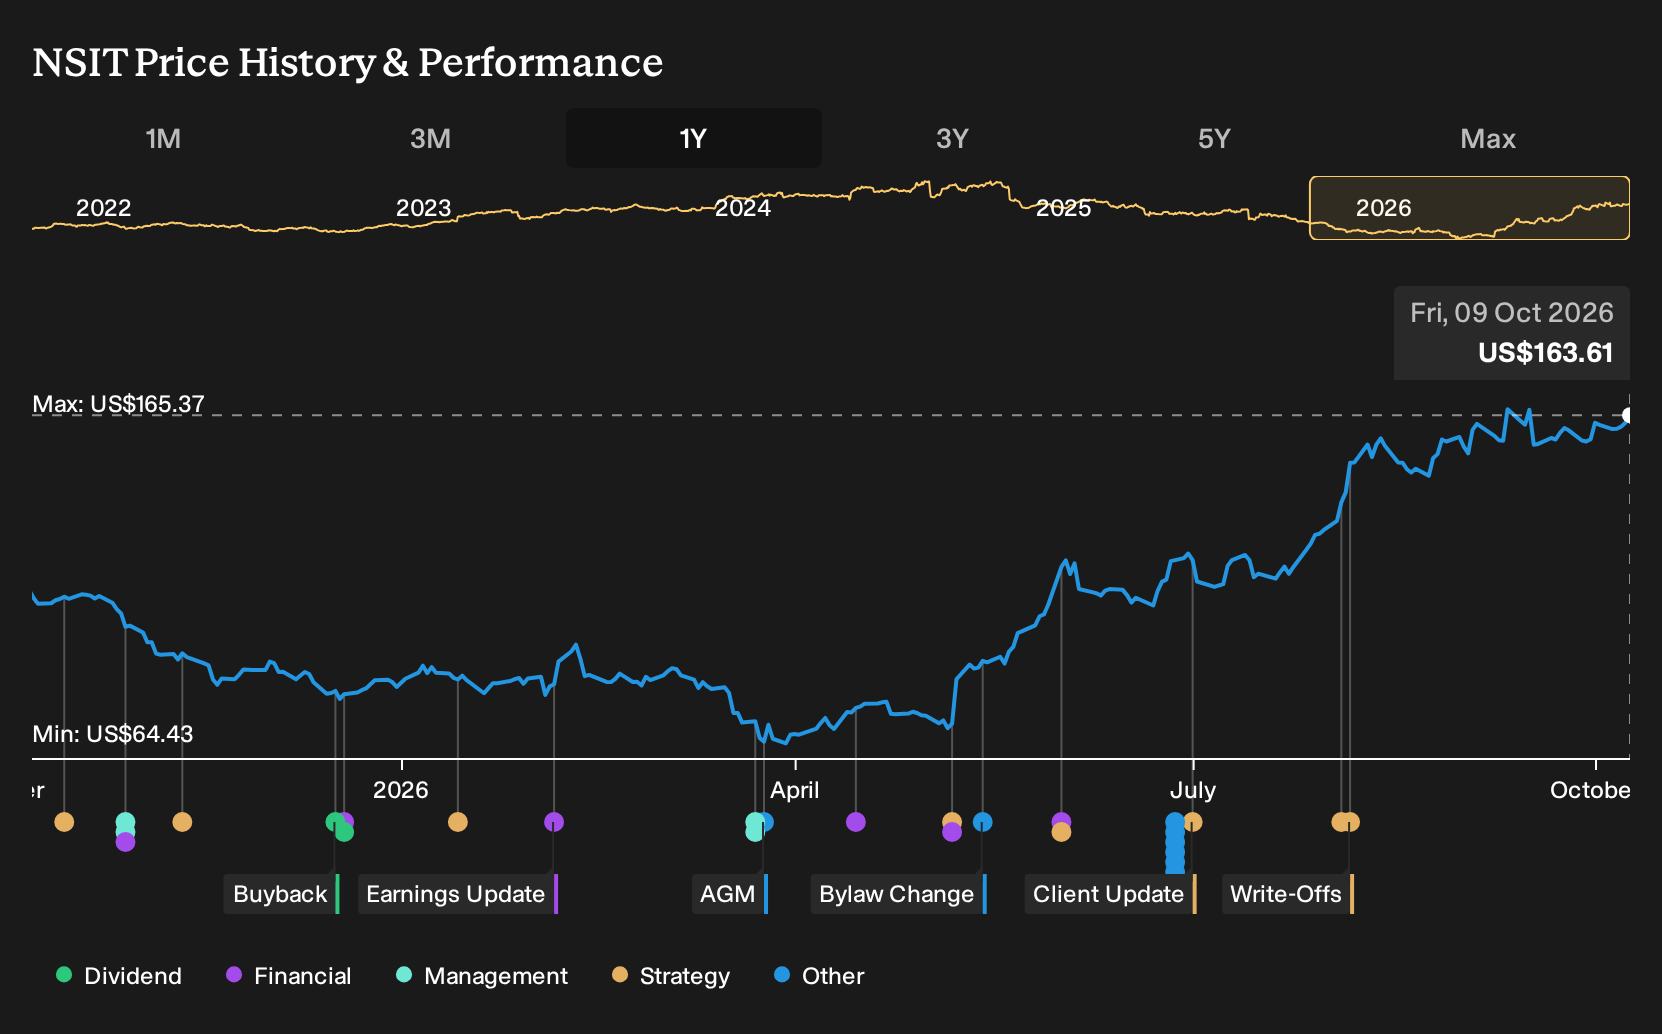
Exploring Other Perspectives
One alternate view leans on balance sheet risk rather than AI upside. The most bearish analysts were assuming revenues of about US$10.1b and earnings of roughly US$420.5m by 2029, but only if Insight Enterprises supports that with heavier debt and buybacks. That is a more cautious storyline. You can compare both sets of assumptions and decide which feels closer to how you see the business, especially now that fresh Q2 2026 news could shift those expectations.
Explore 4 other Insight Enterprises fair value estimates, including one that suggests as much as 33% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Insight Enterprises research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Insight Enterprises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Insight Enterprises' overall financial health at a glance.
Looking For More Investment Ideas Beyond Insight Enterprises?
If the Insight Enterprises story has sharpened how you think about AI focused infrastructure and cash generation, it can help to widen the lens and scan for other businesses that fit your preferred mix of quality, resilience, and upside potential. The Simply Wall St screener can narrow a broad market into a focused watchlist that matches your own risk and return profile.
- If you want companies that already screen well on both quality and valuation, start with a curated group of resilient opportunities through the 20 high quality undiscovered gems.
- If capital preservation and balance sheet strength matter most to you, filter for financially robust businesses using the list of solid balance sheet and fundamentals (25 results).
- If you are building a portfolio around income rather than price moves, focus on consistent cash returns to shareholders with the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com